How an Accelerated Loan Repayment Calculator Actually Works
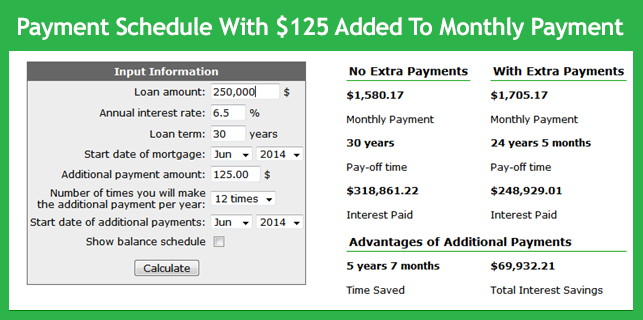
Most people think throwing extra money at their loan every month just speeds things up in a straight line. It doesn't. The math behind it is slightly more annoying than that, and that's where a solid Accelerated Loan Repayment Calculator comes in useful. Here's what you actually need to know before you start plugging numbers into whatever free tool you find on Google.The basic idea is simple: you make your regular monthly payment plus an additional amount, and that extra goes straight toward principal instead of interest. But the reason this matters is that interest accrues daily on most loans, so every dollar you remove early saves you future interest calculations. That's the core mechanic. What most calculators don't tell you upfront is that the way your lender applies payments changes everything.
Using the Accelerated Loan Repayment Calculator
You need three numbers to start: your remaining principal balance, your annual interest rate, and your regular monthly payment. Most free calculators will ask for your loan term too, but that's optional if you already know what you're paying each month. Enter the extra amount you want to throw at the loan annually or monthly, hit calculate, and it'll show you your new payoff date and total interest savings. That part takes about 30 seconds.I found one edge case that tripped me up when I was calculating this for a client back in 2019. Their loan was a fractional-period amortizing note with a 30/365 day count convention, and the standard Accelerated Loan Repayment Calculator kept giving results that didn't match what their servicer's portal showed. Turns out the calculator assumed a 30/360 convention, which is common in textbook examples but wrong for that particular loan type. The workaround was manually adjusting the payment schedule by multiplying each month's interest by the actual days in that month divided by 365 instead of the flat 30/360 assumption. Took about twenty minutes to build a quick spreadsheet that mirrored the servicer's logic exactly. That kind of discrepancy is why you should never blindly trust a single online calculator without cross-checking it against your lender's actual amortization schedule. Run your numbers through two different tools and see if they agree. If they don't, dig into which one matches your loan documents.
The Math Behind Accelerated Repayment
Your monthly interest charge equals your remaining principal multiplied by your annual rate divided by 12. When you add extra principal, you're reducing the base that this calculation runs against next month. That's it. The compounding effect is what makes the difference look dramatic over five or ten years, not anything magical.Here's a concrete example that illustrates the real impact. Say you owe 200,000 on a 30-year mortgage at 6.5 percent. Your regular payment is about 1,264 dollars. If you add just 200 dollars a month toward principal, you'll shave roughly six years off the loan and save around 40,000 in interest. Those are ballpark figures from a standard Accelerated Loan Repayment Calculator, but they hold up reasonably well against actual amortization tables. What people routinely miss is that the first few years of extra payments barely move the needle compared to the later years. Early on, most of your regular payment is already interest, so a small extra amount only trims a few dollars off principal each month. The benefit compounds over time because you're removing principal that would have otherwise generated its own interest. By year seven, that same 200 dollars a month starts saving you noticeably more each cycle. This is why acceleration works best when you commit to it long-term, not as a short-term experiment.
Common Pitfalls That Waste Time and Money
Prepayment penalties exist. Some loans, particularly certain refinanced mortgages or private loans, carry a clause that charges you a percentage of the prepaid amount if you pay off the loan within the first three to five years. A cheap calculator won't factor this in. Always check your loan documents for a prepayment penalty clause before you start accelerating. If one exists, the math changes completely for the first few years, and the accelerated payoff might cost you more than sticking to the standard schedule during the penalty window.Another thing nobody warns you about: some lenders will treat your extra payment as a regular installment rather than applying it to principal unless you specify otherwise. I've seen this happen more than once where borrowers thought they were cutting years off their loan, but the servicer just rolled the extra amount into the next month's payment. The fix is simple enough, but you have to be deliberate about it. Put "apply to principal" in writing with every extra payment, keep records of every transaction, and verify on your next statement that the principal balance actually dropped by the full amount. If it doesn't, call the servicer immediately and get it corrected. There's also the tax angle. In the United States, mortgage interest deductions on Schedule A are limited for loans above 750,000 dollars under current law. If you're above that threshold and itemize, paying off your mortgage faster means less interest deduction each year. For most borrowers this is irrelevant, but it's worth running the numbers if your loan is large. The Accelerated Loan Repayment Calculator won't show you this tradeoff, so you need to think through it separately.
Get the Full Details
When Acceleration Doesn't Make Sense
If you have credit card debt at 20 percent APR, paying extra on a 4 percent mortgage is the wrong move. The interest rate differential is enormous and obvious in hindsight, but people do it because mortgages feel like the "right" thing to pay down. Run your debts in order of highest interest rate first. Accelerated mortgage repayment only wins when your other obligations are handled or carry rates below your mortgage rate.Emergency savings matter too. Liquidating investments to accelerate a low-rate loan can backfire if you then need to borrow again at a higher rate later. Keep at least three to six months of expenses in a high-yield savings account before you redirect every spare dollar toward debt. This isn't motivational advice. It's practical. I've watched clients who emptied their rainy-day fund to pay down a 3.5 percent loan end up financing an unexpected car repair at 18 percent. The math inverted entirely. A standard Accelerated Loan Repayment Calculator works fine for quick estimates, but if you're dealing with multiple loans, variable rates, or unpredictable income spikes you want to direct toward debt, a spreadsheet pays for itself in accuracy within an hour of setup. After that, you can run scenarios in seconds instead of hunting for the right tool every time.


