What You Actually Get When You Download One of These
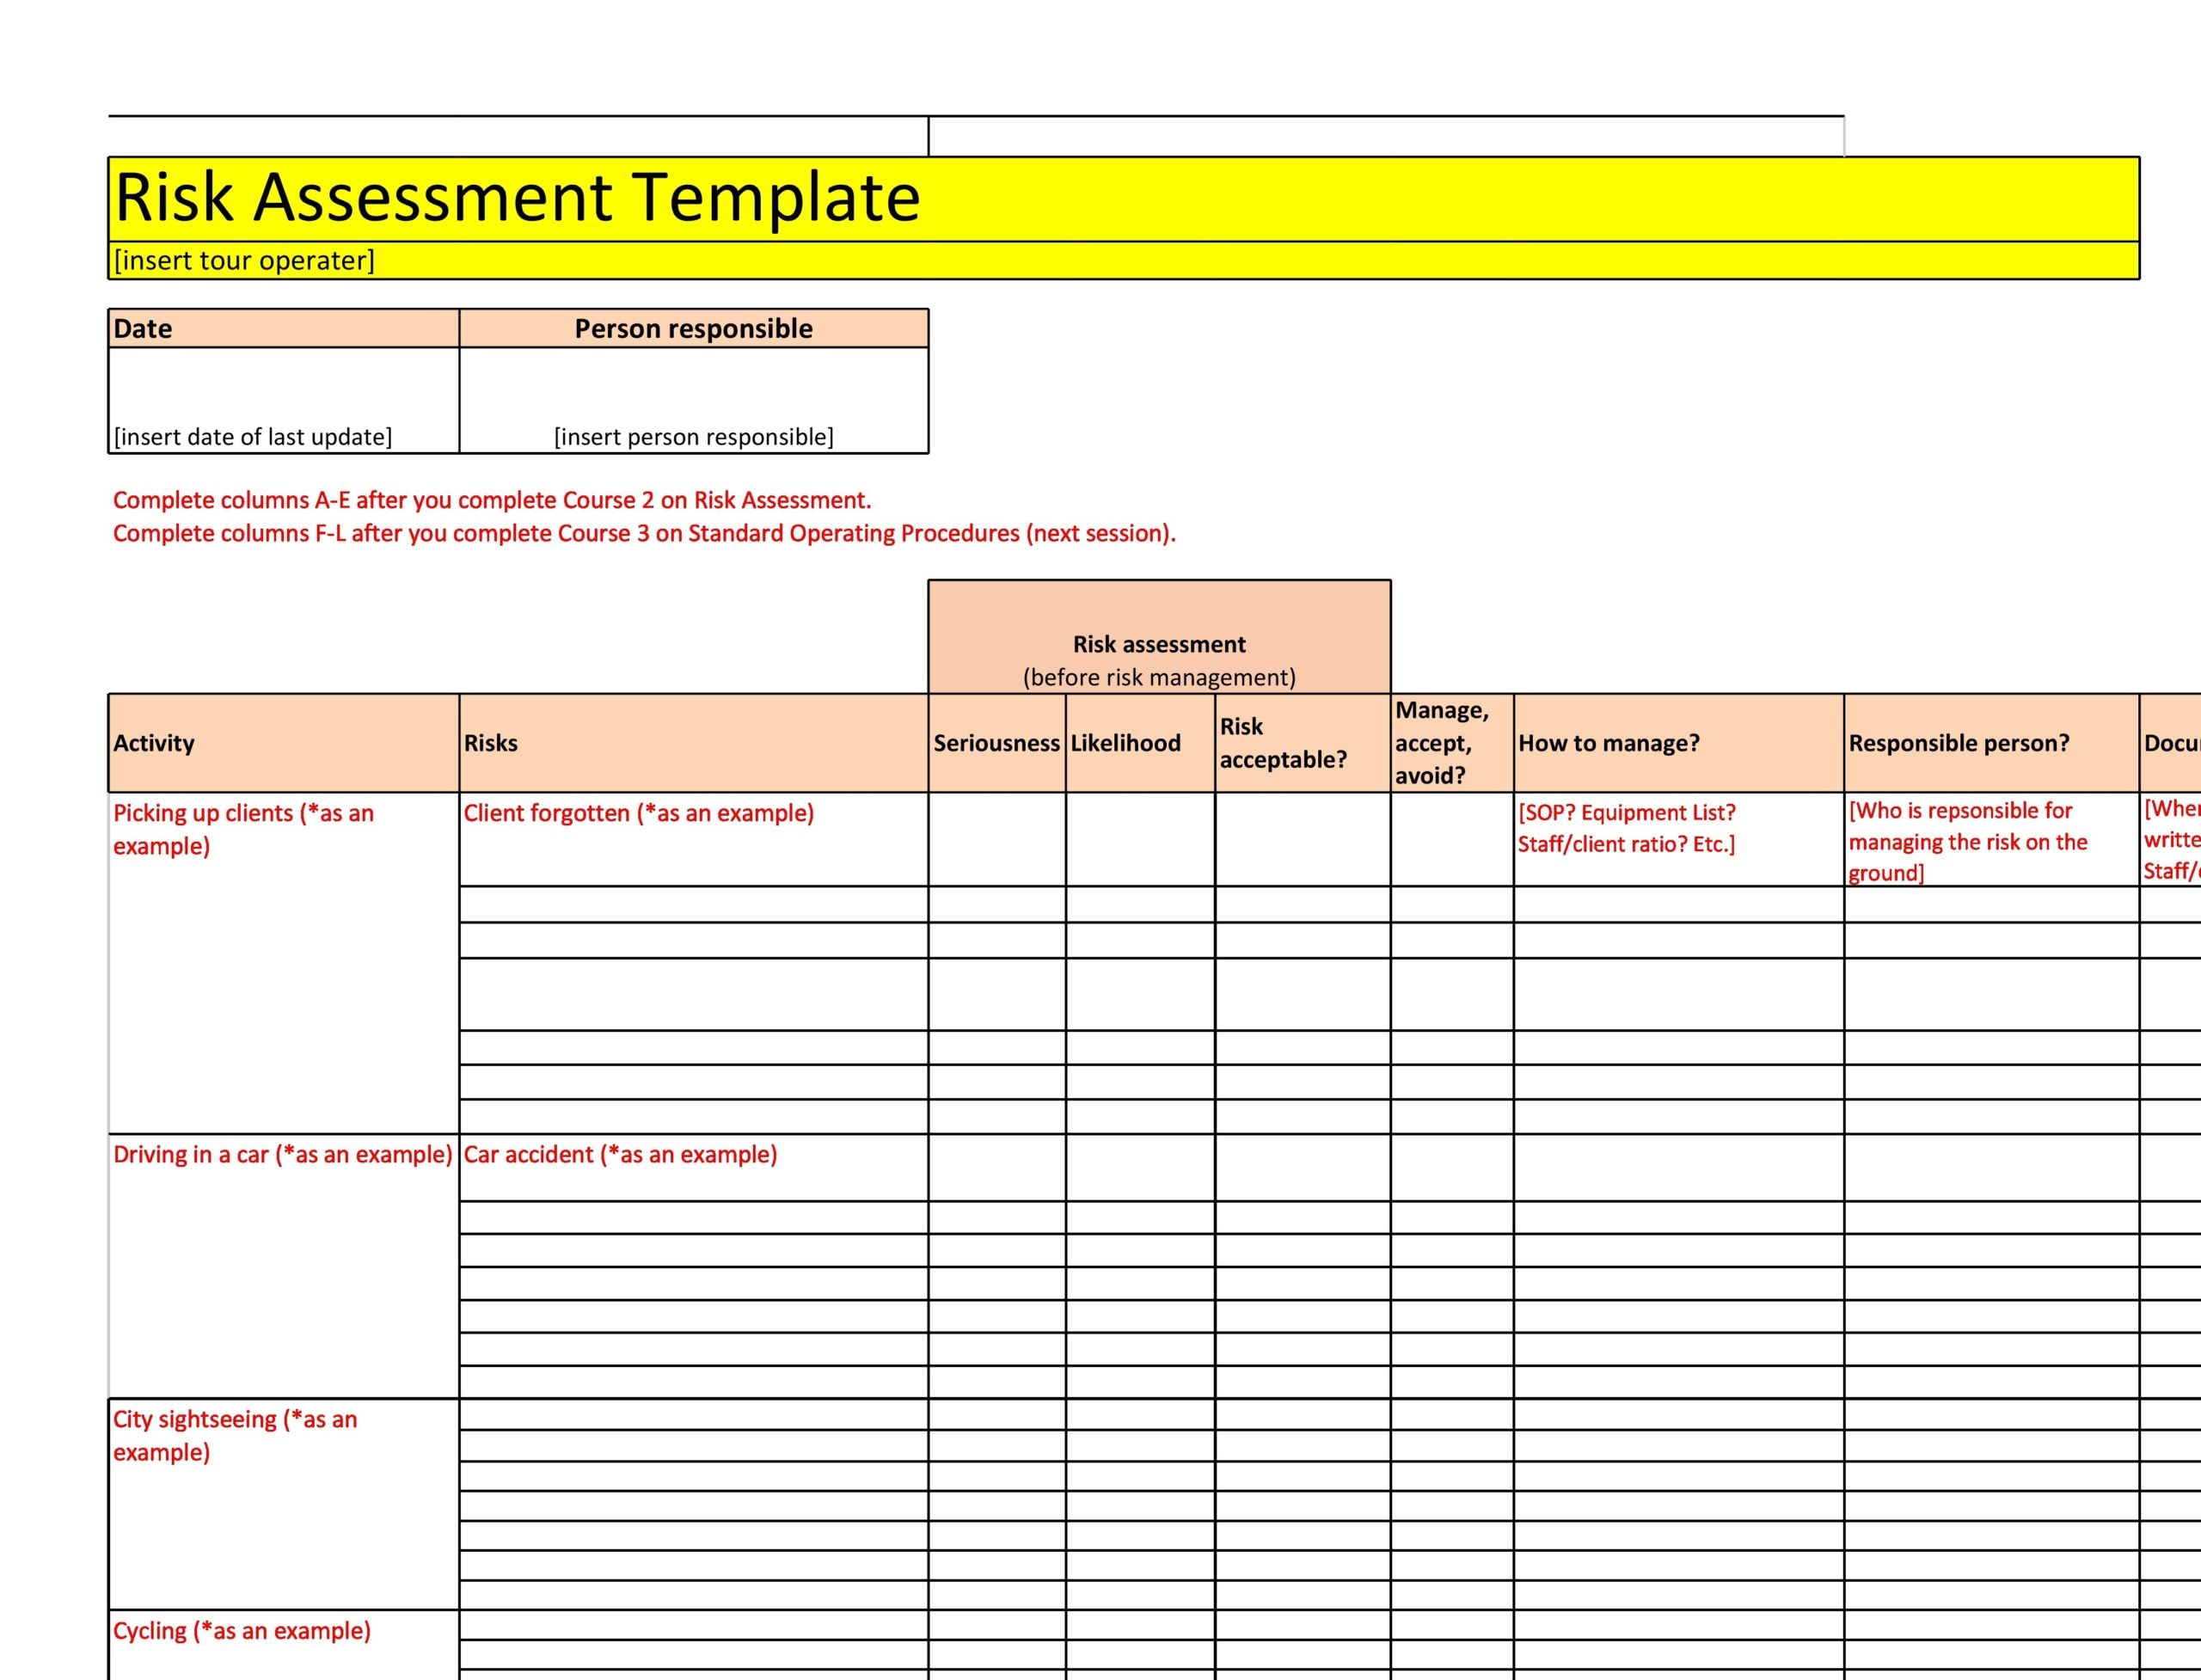
ACH risk assessment templates are basically structured spreadsheets or document forms designed to walk you through the process of evaluating the risk profile of ACH transactions in your business. The free versions you find online tend to cover the same core areas: originator verification, transaction volume analysis, return rate monitoring, customer risk scoring, and compliance mapping against NACHA operating rules. I've used probably a dozen different versions of these over the years, most of them free downloads from banking forums and compliance blogs. The problem is that most of them are built by people who wrote a procedures document once and never actually ran an ACH risk assessment for more than a day. They look comprehensive but miss the parts that matter when something goes wrong at 2am on a Friday.
Where to Find an ACH Risk Assessment Template Free
You can pull one together quickly from a few sources. The NACHA website itself doesn't offer a fillable template, but their rulebook and the Compliance and Risk Management Guide give you the framework. From there, a lot of community banks and credit unions post their internal templates on their websites as part of their public compliance resources. I've grabbed working versions from the FDIC's small bank compliance portal, from the National Bankers Association's member site, and from a few regional Federal Reserve bank training pages. Google searches for "ACH risk assessment template free" will also turn up a lot of generic spreadsheets from compliance software vendors who just want your email address. The ones worth keeping are usually the ones that look ugly. If a template is beautifully formatted with color coding and drop-down menus, it was probably made by a salesperson, not a compliance officer. The useful ones tend to be plain Excel files with basic formulas and a lot of cells that say "enter manual review if threshold exceeded." Here's what I actually use, patched together from three different sources and modified over about four years. The core structure has seven sections, and I'll walk through each one with the parts that actually matter in practice.
The Seven Sections That Matter
Section one is originator profile and verification. This is where you document who is originating the ACH entries, what type of entity they are, how long they've been in business, and whether you've verified their identity through standard KYC processes. Most free templates just give you a checkbox list here. That's not enough. I add a field for "verification method used" and "date of last recertification" because the first time I missed this on an assessment, we had an originator whose corporate status had lapsed two years earlier and nobody had caught it during onboarding. The template flagged the entry types as acceptable but never asked whether the originator's legal standing was current. Section two covers transaction characteristics and volume analysis. You're looking at average daily dollar volume, peak transaction sizes, the mix of debit and credit entries, and the frequency patterns. The counter-intuitive thing most people miss here is that sudden volume changes matter more than absolute volume. A merchant moving from $50,000 per day to $200,000 per day is a bigger red flag than a merchant consistently doing $500,000 per day. The template should have a field for "month-over-month volume change percentage" and a trigger threshold. I set mine at 25 percent change without documented business justification, which typically surfaces about three issues per quarter that would otherwise go unnoticed. Section three is return and rejection rate tracking. This is the section every free template gets right on paper and wrong in practice. They tell you to monitor return rates. They don't tell you which return codes actually matter most or how to weight them. For ACH, the codes that should dominate your attention are R07, R10, R11, R28, and R29. R07 is a return that occurred previously and was resubmitted. That's almost always fraud or a serious process failure. R10 is insufficient funds, which seems mundane until you see a pattern across multiple customers. R11 is customer advisories the account is closed, which is your earliest warning signal for account takeover attempts. R28 and R29 relate to stops and credit advices that can indicate unauthorized origination.
Get the Full Details

I once had a situation where a customer's aggregate return rate was sitting at 1.8 percent, which looked fine on the surface. But when I broke it down by code, 70 percent of the returns were R07 and R10 combinations from the same three originators. That meant we had a small number of bad actors driving the problem, not a systemic issue. A template that only tracks overall return rate would have let this slide for months. Section four handles customer risk scoring. This is where most free templates fall apart because they try to be too simple. The NACHA rules don't give you a point system, so you have to build one that makes sense for your actual operation. I use a weighted model that considers transaction type, volume stability, return history, geographic factors, industry sector, and whether the customer uses prearranged payment and entry (PPD) or corporate credit and debit (CTX) entries. CTX entries carry different risk characteristics because they allow for more complex data formatting and higher values per entry. The scoring scale runs from low to high risk, with explicit criteria for each level. Low risk customers get annual review. Medium risk gets quarterly. High risk gets monthly and requires documented supervisor approval before any process changes are allowed. This is the section where having a real template saves you from arguing with an auditor about why you treated two similar-looking customers differently. If you wrote down the criteria and applied them consistently, you're in a much better position.
Section five covers compliance with NACHA rules. You need to map your processes against the specific rules that apply to your operation. For most businesses, the relevant rules are the Account Verification Rule (Section 2.7.2), the Return Rules, the Entry Verification rules, and the Unauthorized Debit rules under Section 2.7.10. A proper template doesn't just list these rules. It asks you to document, for each rule, what your specific control is, when you last tested that control, and what the result was. I've found that the Account Verification Rule is where most free templates are weakest. Banks and payment processors are required to verify customer account information for certain types of transactions, and the verification standards changed significantly after the 2016 NACHA updates. A template from before 2017 will have outdated requirements. Always check the date on whatever document you download. Section six is the operational controls evaluation. This covers access controls, segregation of duties, encryption standards, file transfer security, and reconciliation procedures. It sounds dry but this is the section that actually prevents incidents. I had a case where our risk assessment showed acceptable scores across every other section, but during the operational controls review we discovered that two employees who should have had separate duties actually shared a single login for the ACH origination system. Nothing bad happened at the time, but it would have made a single disgruntled employee capable of initiating unauthorized debits without triggering any of the standard monitoring flags.
Section seven is the final assessment and remediation tracking. You need a place to document the overall risk rating, any identified gaps, the remediation actions required, the person responsible for each action, and the target completion date. The critical part most templates skip is the follow-up mechanism. A risk assessment that isn't followed up on is just paperwork. I add a field for "remediation status check date" and require that any action older than 30 days without a status update gets escalated automatically.

The Parts Nobody Tells You About
Running an ACH risk assessment with a template is not the same as running an ACH risk assessment in practice. The template gives you structure. It doesn't give you judgment. Here are some things I learned the hard way. First, your template needs a defined assessment period. Some organizations do this annually. For higher-risk operations, that interval is too long. I've seen fraudulent ACH activity go undetected for eight months because the risk assessment cycle was annual and the fraud fell between cycles. If your transaction volume or risk profile has changed materially, you need to trigger an ad hoc assessment regardless of when the last one was scheduled. Second, the template should force you to make decisions, not just collect data. A form that just has blank fields for every metric is a data dump. A form that requires you to select a risk level based on predefined criteria and documents your reasoning is actually useful. When auditors review your work, they're not looking for perfect scores. They're looking for evidence that someone thought about the risks and made deliberate choices. Your template should reflect that process.
Third, consider what happens when your template reveals a problem. I once went through a full risk assessment using a downloaded template and found that our return rate for a particular merchant category had been sitting above our internal threshold for six months without anyone noticing. The template itself didn't solve this, but the act of filling it out forced the issue into the open. The workaround was straightforward but unpleasant: we had to retrospectively review six months of transactions from that category and identify which ones needed to be reversed or disputed. That process took about three days of concentrated work and exposed a gap in our monitoring that I should have caught much earlier.
Limitations You Should Know About
Free templates have real limitations. The most important one is that they're generic. They're built to be broadly applicable, which means they're optimized for neither your specific business model nor your regulatory environment. If you're a credit union in Ohio, the template you found on a national banking association site may not account for state-specific requirements that apply to you. If you're a fintech company processing a high volume of microtransactions, most free templates assume you're dealing with larger, less frequent entries and won't have appropriate thresholds built in. Another limitation is maintenance. A template is only as good as its current version. NACHA rules change. Regulatory expectations shift. A template you downloaded in 2022 may reference rule sections that have been renumbered or superseded. I've spent time correcting templates where the section references were from the 2015 operating rules when we were already on the 2023 version. Always verify the rule citations against the current NACHA Corporate Direct Change of Address (CDCA) database and the latest Operating Rules. The biggest limitation is that a template doesn't replace expertise. I've seen organizations treat the completion of a risk assessment template as the end of the process. It isn't. It's the beginning. The template structures your thinking. It doesn't think for you. If you fill in every field mechanically without questioning whether the numbers make sense or whether the controls you're describing actually exist in practice, you're creating a document that looks compliant and is completely hollow.
A Practical Workflow I Recommend
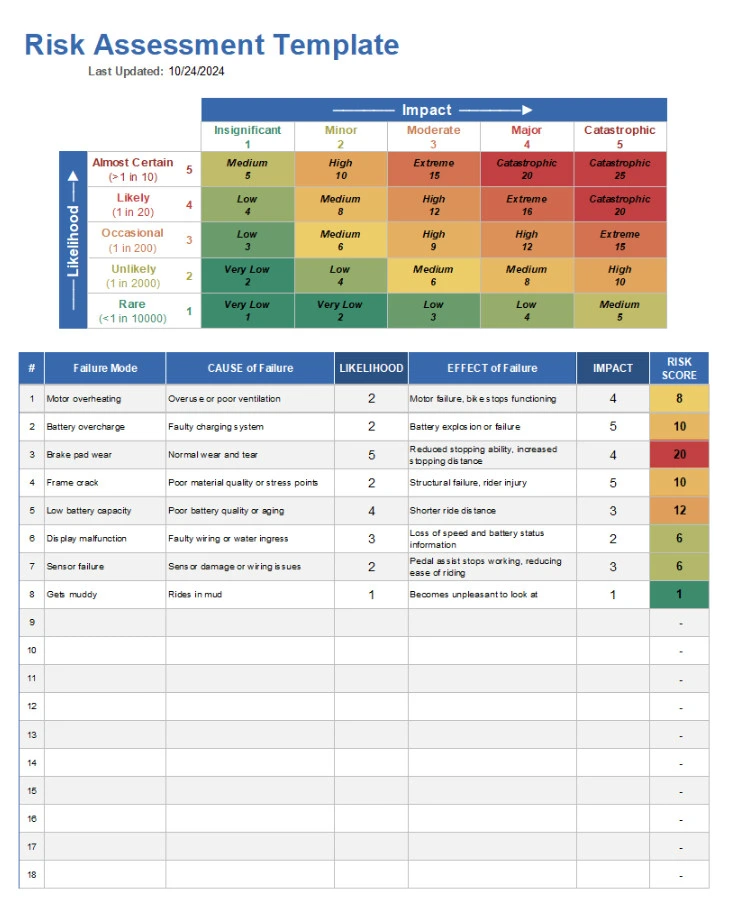
Here's how I actually run a risk assessment with a template, from start to finish. It usually takes one to two days for a medium-complexity operation if you have the data readily available. It can take a week if you're pulling information from multiple systems and departments. Start by gathering your data before you open the template. Pull your transaction reports for the assessment period. Get your return and rejection reports broken down by code. Collect your originator onboarding files. Review your access logs and reconciliation records. Having this information ready means you can fill the template in a focused session instead of stopping every five minutes to chase down a number. Then work through the template systematically, section by section. Don't skip ahead. Each section builds on the previous one, and skipping around creates gaps in your documentation. When you hit a field where the answer isn't clear, write down exactly what you don't know and who can tell you. That's not a failure. That's useful information.
After you complete the template, spend time on the remediation tracking section. This is where the template earns its keep. Every identified gap should have an owner, a deadline, and a measurable outcome. If you can't define the outcome in a way that lets you verify completion, you haven't thought through the remediation carefully enough. Finally, schedule your next review date before you close the document. I recommend a maximum of nine months between full assessments for most operations, with quarterly reviews of the high-risk categories even if you're not doing a full reassessment. The template should have a field for this so it doesn't get forgotten.
Building Your Own Versus Downloading Someone Else's
I'll be straight about this. The first time you build or heavily modify an ACH Risk Assessment Template Free, it's going to take more time than just downloading something and filling it in. But the version you end up with will actually match your operation, and you'll understand every field well enough to explain it to an auditor or a regulator without scrambling. If you do download a template, plan to spend at least a few hours customizing it. Check every rule reference. Verify that your internal thresholds appear in the right places. Add fields for the metrics that matter in your specific environment. Remove the fields that don't. A template with twenty fields you never use is worse than a template with ten fields you actually rely on. The template is a tool. The assessment is the work. Don't confuse the two.