How Extra Payments Actually Change Your Mortgage
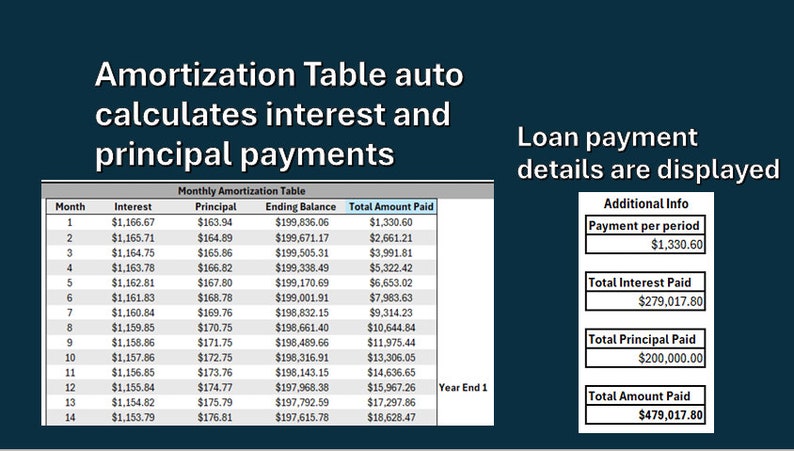
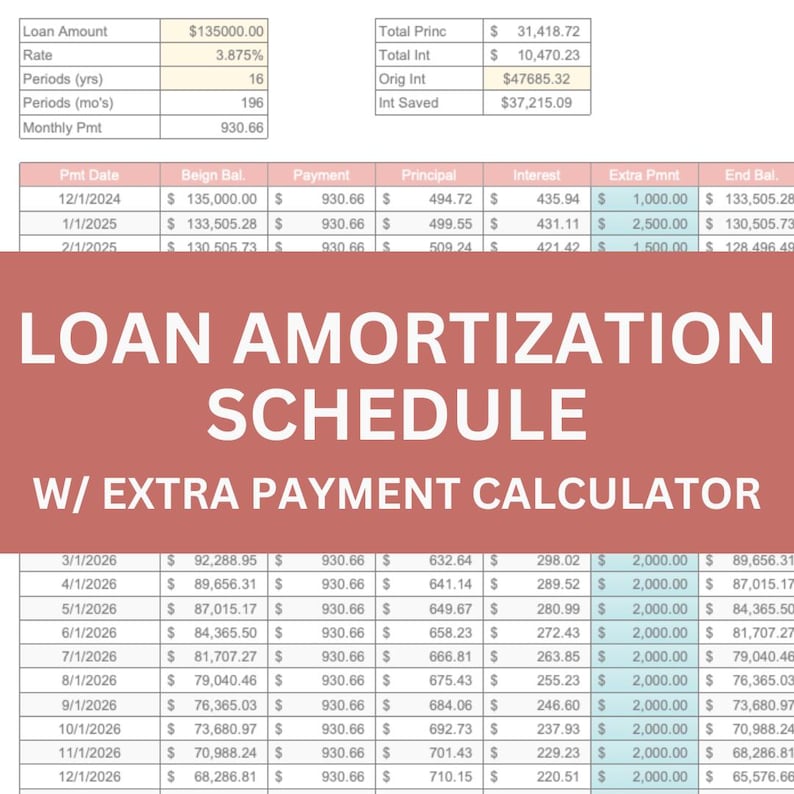
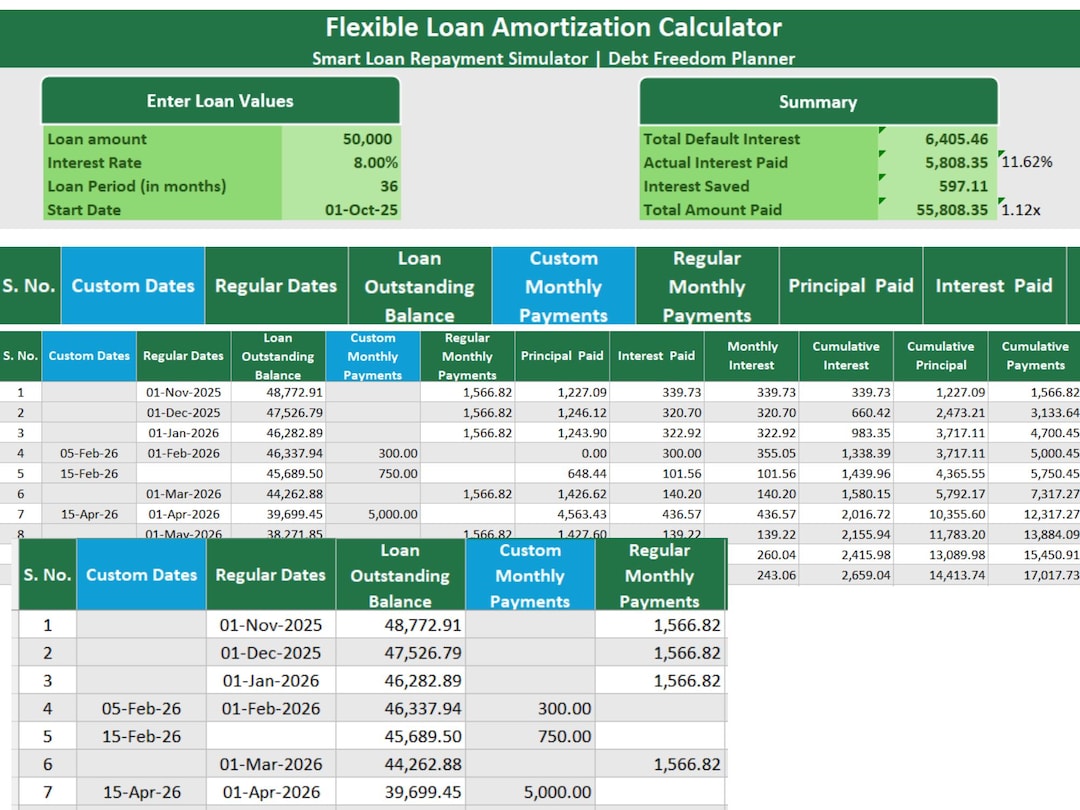
Most people add extra principal payments to their mortgage without really understanding how the amortization schedule responds. The default behavior of most amortization calculators is to keep the same payment amount and the same end date, just shrink the number of payments you need to make. Some calculators instead keep the payment term the same and shorten the loan duration. These produce different results, and if you're not paying attention you'll end up with the wrong expectation about when you'll be debt-free. The basic workflow is straightforward. You enter your loan amount, interest rate, and original term. Then you find the field that accepts additional payments — some calculators call it "extra monthly payment," others label it "additional principal" or "one-time extra payment." You put a number in there, hit calculate, and the tool generates a revised schedule. That's the theory. The reality has a few wrinkles that aren't obvious until you've worked through several of these. First, confirm whether the calculator applies your extra payment to the current month only or distributes it across every payment period. A one-time $5,000 extra payment in month three does something completely different from a recurring $200 extra payment each month, even if the total comes to roughly the same amount over the life of the loan. I spent an afternoon once comparing two calculators that gave me two very different payoff dates for identical inputs because one treated my extra payment as a single bullet and the other spread it evenly across all remaining months. Neither was wrong. They were just answering different questions.
The second thing to check is whether the tool recalculates your monthly payment or holds it constant. When you hold the payment constant and throw extra money at principal, you save more interest over the life of the loan because the higher payments are applied later when the remaining balance is still substantial. When you recalculate the payment downward, you reduce monthly cash flow pressure but you typically save less in total interest. This is counter-intuitive for a lot of people who assume that lowering their monthly obligation is always the smarter financial move. It usually isn't if your actual goal is minimizing total interest paid.
What Happens To the Schedule When You Add Principal
Each additional dollar you pay toward principal reduces the outstanding balance before the next interest calculation runs. Interest on a mortgage is calculated on the remaining principal, not the original loan amount. So every extra payment you make now ripples forward through every subsequent month. The compounding effect works in your favor here, which is why extra payments early in the loan term have a dramatically larger impact than the same extra payments made in year five or six. I've seen people throw an extra $300 a month at a 30-year loan in year one versus year twenty, and the year-one version saved them roughly three times as much in total interest. The revised amortization schedule will show a new breakdown for each payment period. You'll see the principal portion grow and the interest portion shrink faster than the original schedule projected. The exact mechanics depend on how your loan is structured. Most conventional mortgages use a standard amortization where each payment covers interest first and then principal. Some loans have different structures — graduated payment mortgages, option ARMs with payment options, or interest-only periods — and the extra payment behavior can diverge significantly from what a standard calculator assumes. If you have any of these atypical loan types, run your numbers through the lender's own calculator or ask them directly how extra payments are applied. Third-party tools rarely account for the nuances.
Get the Full Details
Edge Cases and Practical Problems
One problem I ran into recently involved a borrower who was making biweekly payments instead of monthly. She added an extra $100 per payment period into an amortization calculator that only supported monthly inputs. The tool gave her a payoff estimate that was off by nearly two years because it didn't account for the compounding effect of 26 half-payments per year versus 12 full payments. The fix was simple once I identified it: convert the biweekly schedule into an equivalent monthly extra payment, then run it through the calculator. Her biweekly $100 extra was actually closer to a $217 monthly extra when you normalize for the payment frequency difference. Using the converted number gave her a schedule that matched what her lender's system produced within a few days. Another issue comes up with loans that have prepayment penalties. Some calculators don't factor those in at all. If you're within the first few years of your loan and your lender charges a penalty for paying down principal faster than a certain threshold, your actual savings could be significantly less than what the calculator shows. I had a client who saw a projected $42,000 in interest savings from extra payments, then discovered her loan had a 2% prepayment penalty on the first $100,000 of accelerated principal paid in year two. The penalty ate about $2,000 of the benefit. It's worth checking your loan documents or calling your servicer before you commit to an aggressive extra-payment plan.
Pitfalls People Miss
The biggest mistake I see is assuming that any extra payment goes entirely to principal. When you're current on your mortgage, an extra payment typically does go to principal. But if you're even one day late, part of that extra payment may be absorbed by the late fee or accrued interest first. Always verify that your payment is being applied correctly by checking your statement after the first extra payment goes through. A few lenders are sloppy about this, especially during the servicing transition period when accounts get transferred between companies. A second common error is rounding the revised payoff date to the nearest whole month without checking whether the final payment is a partial payment. Some calculators will show a payoff date of, say, June 2031, but the last payment in that month might only be $147.33 instead of a full payment. If you're planning to sell the house or refinance, you need to know the exact remaining balance on the payoff date, not just the month. Request a formal payoff quote from your servicer rather than relying on the calculator's final row. There's also the tax implication to consider, though this one only matters for a subset of borrowers. In the United States, mortgage interest is deductible only on interest you actually pay. If extra principal payments reduce your interest expense significantly, your tax deduction shrinks accordingly. For someone in a high tax bracket with a large mortgage, this can offset a meaningful chunk of the interest savings. It's not a reason to avoid extra payments, but it's a factor that changes the net benefit calculation.
When This Approach Doesn't Work Well
Extra principal payments aren't universally advantageous. If your mortgage interest rate is below 3.5% and you have access to investment options that historically return 6% or more after tax, you're likely better off investing the extra money rather than paying down the mortgage. The math is straightforward: a guaranteed 3% return from extra principal payments is inferior to a portfolio weighted toward equities over a long time horizon. The reverse is also true — if your rate is above 6.5%, paying down that debt usually beats most reasonable investment alternatives, especially in a volatile market. Another scenario where extra payments fall apart is when you're barely covering the minimum payment. If your cash flow is so tight that an extra $150 a month would force you to dip into emergency savings or carry credit card debt, the mortgage optimization doesn't matter. High-interest revolving debt is a far bigger financial poison than a low-rate mortgage. Pay off the credit cards first, then return to the amortization strategy.
How to Get the Most Out of Your Calculator
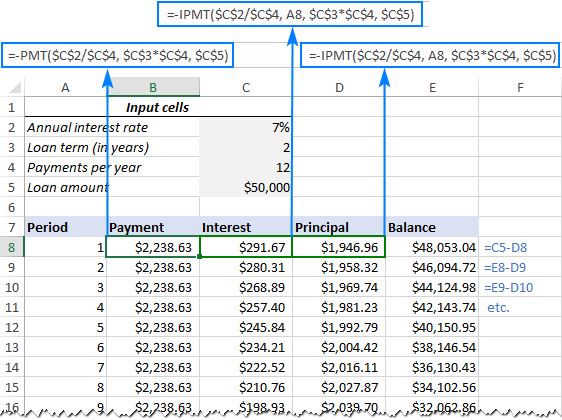
Run multiple scenarios before you commit. Put in your extra payment, note the interest savings and new payoff date. Then try a slightly higher amount and a slightly lower amount. The difference between those three outputs tells you whether an additional $50 per month is worth the lifestyle tradeoff. I usually run three scenarios: the baseline, a conservative extra payment that I'd feel comfortable maintaining for five years, and an aggressive one that would require some sacrifice. The conservative scenario is often the sweet spot because it's sustainable. Aggressive plans look great on paper until real life intervenes — a car repair, a medical bill, a job change — and the whole schedule gets abandoned halfway through. If you want a downloadable tool, search for a spreadsheet-based amortization calculator that lets you input variable extra payments by month. Static online calculators are fine for quick estimates, but they don't handle the case where your extra payment amount changes from month to month. A spreadsheet lets you model a realistic payment pattern — higher extras in bonus months, zero extras in lean months — and still produces an accurate aggregate result. The built-in PMT and PPMT functions in Excel or Google Sheets handle this without any additional cost, and you can adjust the interest rate or term instantly to see how sensitive your payoff date is to small changes. The core principle is simple: every dollar of extra principal reduces the balance that future interest charges are calculated on. How much you save depends on when you make those payments, how large they are, and whether your loan terms allow the full benefit to flow through without penalties or accounting quirks. Run the numbers with your actual loan details, not a generic example, and verify the output against your lender's statement after your first extra payment posts. That verification step alone catches more errors than anything else in the process.