How Biweekly Payments Actually Change Your Mortgage Math
Most people don't realize that switching to biweekly payments doesn't just split the monthly payment in half. It changes the compounding structure entirely, and doing it wrong means you lose most of the benefit without knowing it. Here's the practical reality. A standard monthly amortization schedule charges interest based on 12 compounding periods per year. When you move to biweekly, you're making 26 payments instead of 12, which equals the equivalent of 13 full monthly payments spread across the year. That single extra payment goes almost entirely toward principal, and the effect compounds faster than most calculators show on their surface level.
Setting Up an Amortization Calculator Bi Weekly
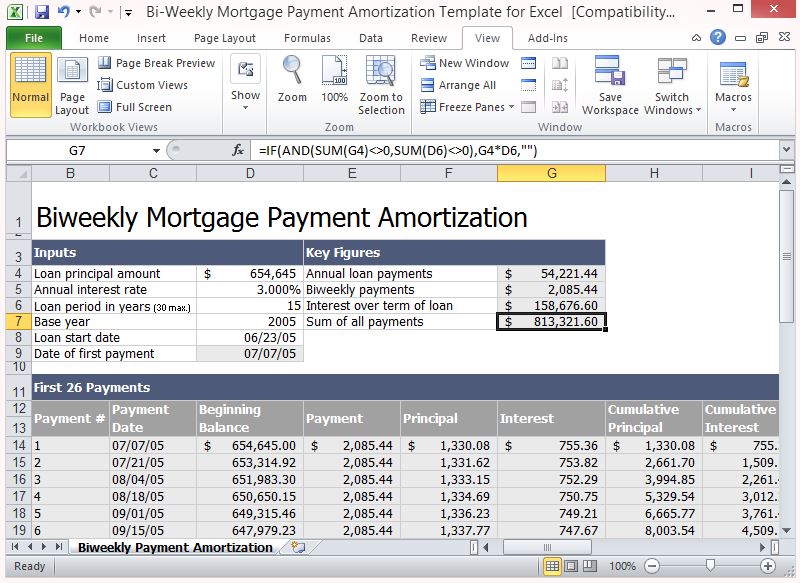
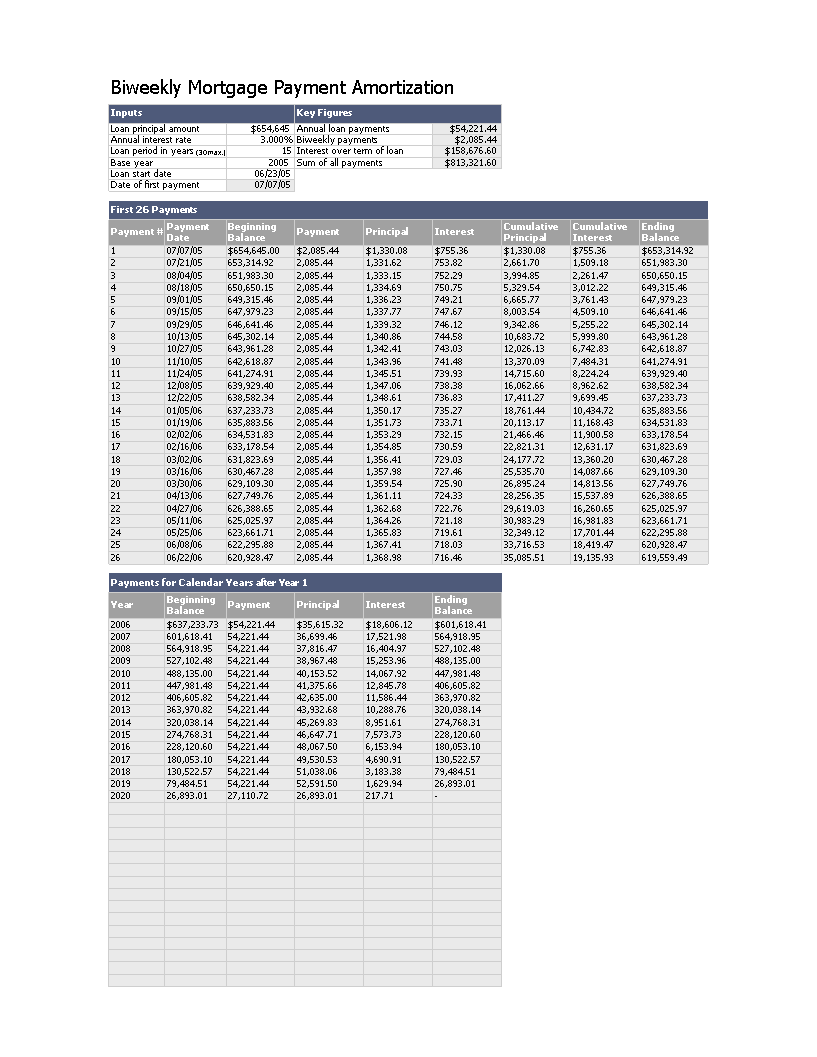
I built my own amortization tool after spending too much time troubleshooting free online calculators that gave wildly different results depending on how they handled the day-count convention. Here's how you actually set it up properly. First, you need to decide between two approaches. The strict biweekly method calculates a payment using 26 periods per year with the rate divided by 26. The half-payment method simply divides the standard monthly payment by two and applies it every 14 days. They produce different results, and the difference matters over a 30-year term. The formula for the strict biweekly approach is the same as any standard amortization, just adjusted for the period. You take the annual interest rate, divide by 26 to get the biweekly rate. Then you calculate the total number of payments by multiplying the loan term in years by 26. The payment formula becomes:
PMT = P × [r(1 + r)^n] / [(1 + r)^n - 1] Where P is the principal, r is the biweekly rate, and n is the total number of biweekly payments. Most free calculators skip this precision and approximate, which is why the numbers often look slightly different when you compare them. Here's a concrete example. Let's take a $300,000 loan at 6.5% annual rate over 30 years.
Get the Full Details

Biweekly rate = 0.065 / 26 = 0.0025 per period. Total payments = 30 × 26 = 780. Plugging into the formula: PMT = 300000 × [0.0025 × (1.0025)^780] / [(1.0025)^780 - 1]. That works out to approximately $740.38 per biweekly payment.
For comparison, the monthly payment on the same loan at standard terms is about $1,896.20. Over 30 years, monthly payments total roughly $682,632 in all payments. The biweekly total comes to about $577,923. That's a savings of approximately $104,700 in interest and the loan pays off in about 25 years instead of 30.
Where People Get Burned
The biggest issue I've seen repeatedly is that not all lenders apply biweekly payments correctly. I had a client who switched to a biweekly program through his bank, and after six months he noticed the principal balance wasn't moving as fast as the amortization schedule predicted. Turns out the bank was accumulating the biweekly payments and releasing them as monthly payments to themselves. He was still making 26 half-payments, but they were being applied at the monthly frequency. Effectively neutralizing the entire benefit. The fix was straightforward once identified. He switched to making the half-payments directly and explicitly instructing his servicer to apply each payment to principal as received, not to hold them in suspense. Many servicers have a "biweekly conversion fee" built into their programs too, ranging from $100 to $300, which eats into your early savings. Another edge case that trips people up involves loans with prepayment penalties. If your mortgage has a three-year prepayment penalty clause that charges two months' interest on any extra principal paid, the biweekly strategy loses its advantage during that window. I ran the numbers on a loan where the penalty structure meant the biweekly savings were essentially zero for the first 36 months. After the penalty period expired, the strategy became viable again, but by then the compounding effect had already been delayed significantly.

The Counter-Intuitive Part Nobody Talks About
Biweekly payments seem like a guaranteed win, but they're not always optimal. The reason is opportunity cost. If you can earn a higher return elsewhere than your mortgage interest rate, accelerating payoff is mathematically inferior to investing the same money. Say your mortgage is at 6.5% and you have a decent taxable investment account earning 8% annually after taxes. The biweekly payments save you 6.5% guaranteed, but you'd make more by investing instead. This is particularly relevant for high-income earners in the top tax brackets where investment returns after tax-advantaged accounts are limited. There's also the liquidity consideration. Money locked into home equity through aggressive biweekly payments isn't accessible without refinancing or a home equity product, and both come with their own costs. I've seen borrowers who accelerated their mortgages only to face cash flow problems when a major expense hit, having to pay high-interest credit card debt because their liquidity was tied up in the house.
The other practical limitation is that some loans don't benefit at all. Adjustable-rate mortgages, especially those with caps and floors, can make the biweekly calculation unpredictable. If your rate adjusts every year and you're in a rising rate environment, the biweekly payment might not cover the increasing interest obligation as the rate resets. Your amortization schedule becomes unreliable because the rate variable is no longer constant.
What to Check Before You Commit
Read your loan documents for prepayment penalty clauses. Even a small penalty structure can erase years of savings. Check with your lender about whether they offer an official biweekly program or if you'll be managing this independently. The independent route saves you the conversion fee but requires discipline to maintain the payment schedule. Run your own amortization schedule rather than relying on the lender's projection. I've seen servicers show projected savings that assume perfect payment timing and no fees, which rarely matches reality. Build your own spreadsheet or use a calculator where you can input the exact terms and see the amortization table month by month. The difference between the projected and actual numbers tells you whether the strategy is worth pursuing. Consider the tax implications too. Mortgage interest is deductible in many cases, and accelerating principal paydown reduces your deductible interest expense. If you itemize deductions, the biweekly strategy might actually increase your effective tax liability in the early years when you're paying down the most principal. Run the numbers with your marginal tax rate included to get the true after-tax cost of the loan.

The biweekly approach works well for people who want forced savings and don't have better investment outlets. It's less ideal for those with higher-earning alternatives or loans carrying prepayment restrictions. The math is clear when you account for all variables, and the shortcut of assuming "biweekly always saves money" is where most people make the wrong call.