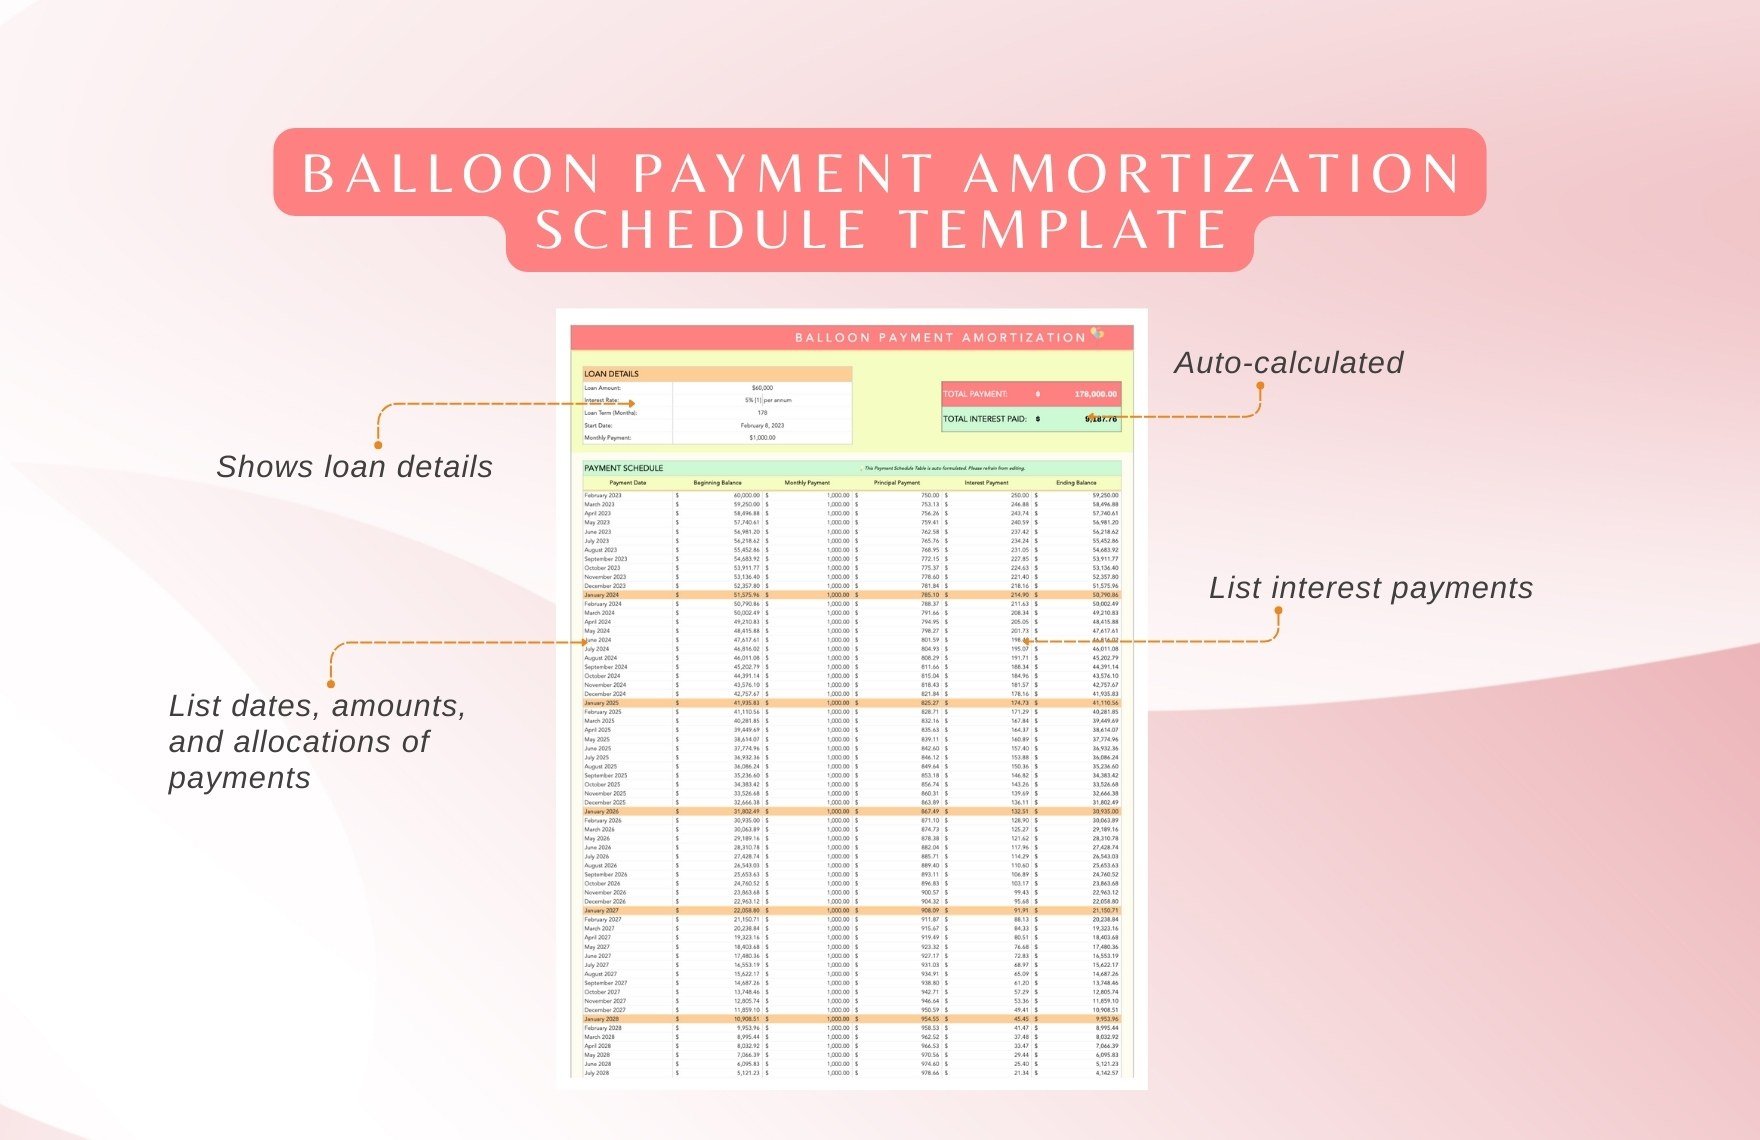
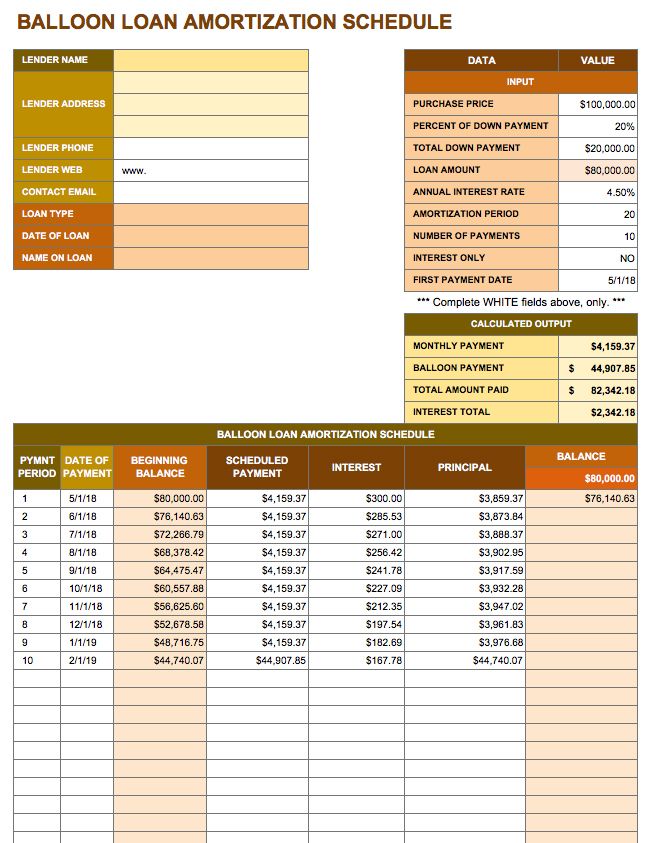
How balloon payment amortization actually works in practice
Most people see a balloon payment schedule and assume it's just a regular loan with a big lump sum at the end. It's not quite that simple. The mechanics are straightforward enough, but the way interest compounds and the principal drops over time creates some quirks that trip people up if they aren't paying attention. Here is how you build one from scratch. Start with the loan amount, the annual interest rate, and the term in years. Calculate the periodic payment using the standard amortization formula, but apply it only to a portion of the principal—typically 80 to 90 percent—spread over the full term. The remaining balance, the part you never paid down through the regular installments, becomes the balloon payment due at maturity. In Excel, you can set this up by using the PMT function on the partial principal, then placing the remainder as a single cell reference at the end of your schedule. The tricky part is making sure the payment calculation and the balloon amount tie together correctly without double-counting interest.
Understanding the Amortization Schedule Balloon Payment Structure
At its core, a balloon payment structure means you make smaller regular payments for a set period, then owe a large chunk all at once. That large chunk is the unpaid principal that your regular payments never touched. Lenders offer this because it lowers your monthly outflow, which makes qualifying easier and improves cash flow during the active life of the loan. Borrowers accept it because they plan to refinance or sell before the balloon comes due. Both sides usually get what they want—if the timing works out. The amortization schedule itself looks mostly normal. Each payment covers interest accrued on the remaining balance plus a small slice of principal. Because you're only amortizing part of the loan, the principal reduction each period is smaller than it would be on a fully amortized loan of the same term. That means more interest costs overall compared to a traditional mortgage-style payoff, even though your monthly bill is lower. You can see this clearly in the schedule: the interest portion stays elevated throughout the life of the loan, and the principal balance barely moves until the final period when the balloon hits. I ran into a specific problem a few years back with a commercial real estate deal where the borrower had structured a balloon payment loan at 7.25 percent over seven years with a 25-year amortization schedule. The monthly payment was calculated on the full 25-year schedule, which made the payment appear affordable. But the balloon was due in year seven, and the property had only appreciated about 8 percent in that window—not enough to cover the refinancing gap. The borrower expected to sell and recoup the difference. They couldn't sell fast enough, and the refinance didn't close because the LTV had shifted unfavorably when rates ticked up. What saved them was a loan modification that extended the balloon date by two years and adjusted the interest-only period. It wasn't elegant, but it prevented a default that would have cost everyone more in the long run. The lesson: always model the balloon date against realistic exit scenarios, not optimistic ones.
One counter-intuitive thing about balloon structures is that the total interest paid can actually be higher than a fully amortizing loan at a slightly higher rate. This happens because the lower monthly payment means less principal gets chipped away early on, so interest accrues on a larger balance for longer. A borrower might save $400 a month and think they're coming out ahead, but over the full life of the loan they could be paying thousands more in interest. You need to calculate the total cost of the balloon structure against a comparable fully amortized loan before deciding which is cheaper. The monthly savings are real, but they come with a hidden tax. Another nuance that people miss is how prepayment penalties interact with balloon schedules. Many balloon loans carry a yield-maintenance or defeasance clause rather than a simple prepayment penalty. That means if you pay off the loan early, you're still on the hook for a significant portion of the expected interest. This is different from a standard Conforming loan where prepayment penalties are rare and usually limited to the first few years. With a balloon structure, the lender is pricing the loan assuming you'll carry it to maturity, so breaking early costs more than you'd expect. Always read the prepayment section carefully before signing. The numbers in the disclosure documents can look reasonable until you run the actual prepayment calculator. Here is a concrete example. You borrow $500,000 at 6.5 percent annual interest with a seven-year balloon and a 25-year amortization schedule. Using the PMT formula on the full $500,000 over 25 years at 6.5 percent gives a monthly payment of roughly $3,442. That payment is what you owe each month for seven years. After 84 payments, you've paid down about $118,000 of principal. The remaining balance—the balloon—comes to approximately $382,000. Your total interest over those seven years is about $109,000, and then you still owe $382,000 as a lump sum. Compare that to a fully amortizing 25-year loan at the same rate: the monthly payment would be the same $3,442, but after seven years you'd have paid down roughly $72,000 more in principal because the amortization is working differently. The balloon structure keeps your payment low but leaves a massive hole at the end.
Get the Full Details
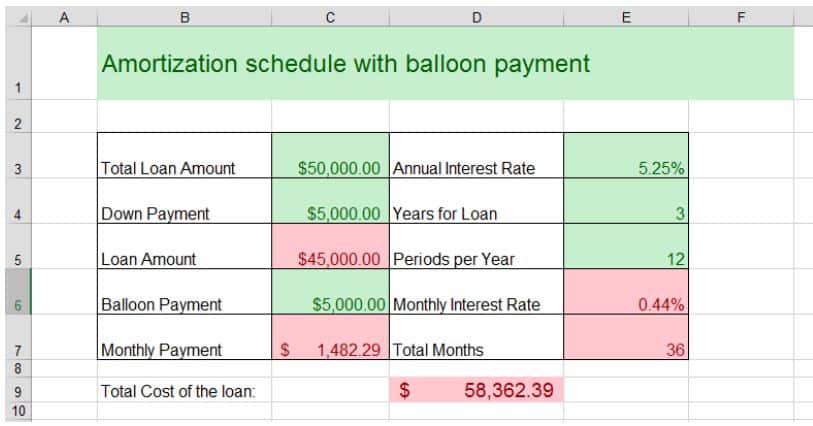
The tools to build and track this are straightforward. Excel or Google Sheets handles it fine. You set up columns for payment number, beginning balance, payment amount, principal portion, interest portion, ending balance, and cumulative principal paid. The PMT function handles the payment. The PPMT and IPMT functions split each payment into principal and interest components. For the balloon, you simply calculate the remaining balance at the due date using the FV function or by tracking the amortization table through the final regular payment. A free tool I've recommended to people on forums before is the balloon payment calculator from Bankrate, which lets you input the parameters and generates a full schedule. For something more customizable, a well-structured Excel template with data validation and conditional formatting for the balloon due date works better for serious analysis. I keep a template on my machine that I reuse—it saves about twenty minutes per loan analysis compared to building from scratch. There are scenarios where a balloon payment structure simply does not make sense. If you cannot reliably refinance or sell before the balloon comes due, the risk of default is real and the consequences are severe. Some borrowers treat the balloon like a deferral when it is actually a trigger event. It is not a payment holiday. It is a maturity. If your exit strategy depends on favorable market conditions, rising property values, or stable credit markets, you are gambling more than you might realize. In tight credit environments, refinancing a balloon loan can become impossible even if your payments have been perfect. I have seen this play out in multifamily and commercial deals where the borrower assumed they could refinance into a conforming loan and instead found no takers because the property didn't meet lender overlays or the debt service coverage ratio had tightened. The balloon wasn't a problem on paper. It was a problem in practice. If you are evaluating whether a balloon structure fits your situation, the most important thing to do is stress-test the exit. Model at least three scenarios: what happens if you refinance at current rates, what happens if you sell at projected appreciation, and what happens if neither works and you have to carry the balloon into a higher-rate environment. The third scenario is the one most people skip. It is also the one that matters most. A balloon payment loan is a tool, not a trap, but only if you understand the mechanics and have a realistic plan for the payoff. Without that, you are just deferring a problem that will come due on a date you can't change.