How to Build an Amortization Schedule With Extra Payments in Excel
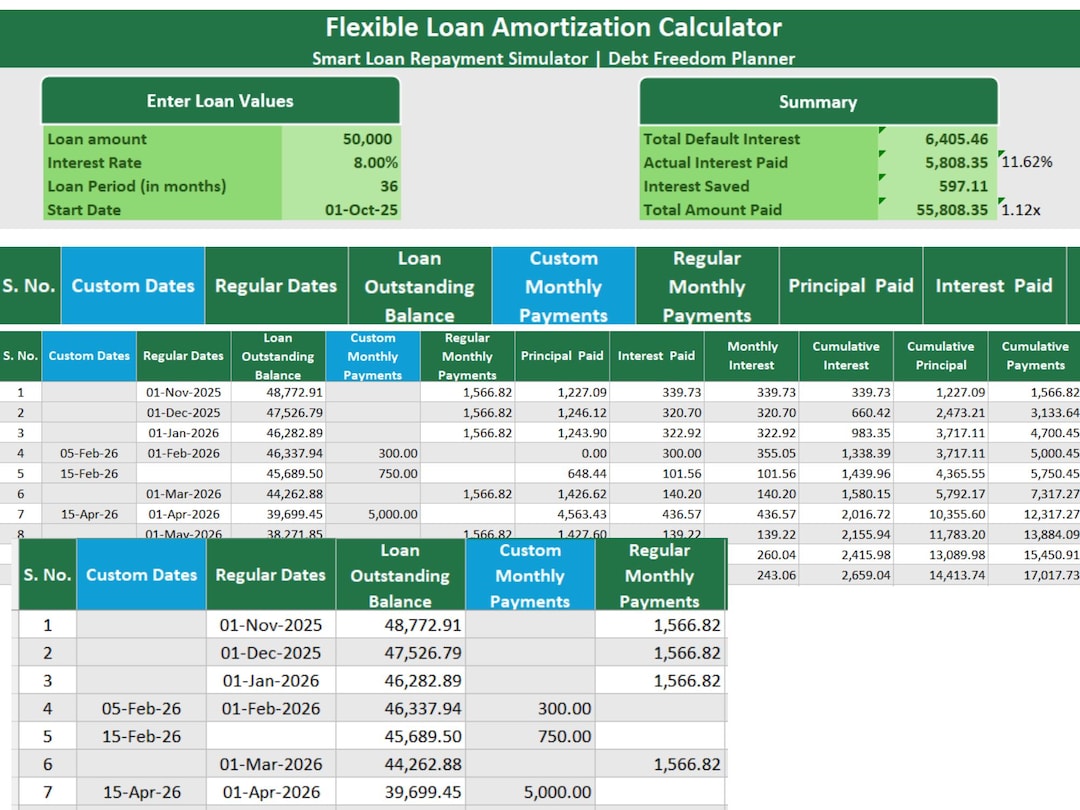
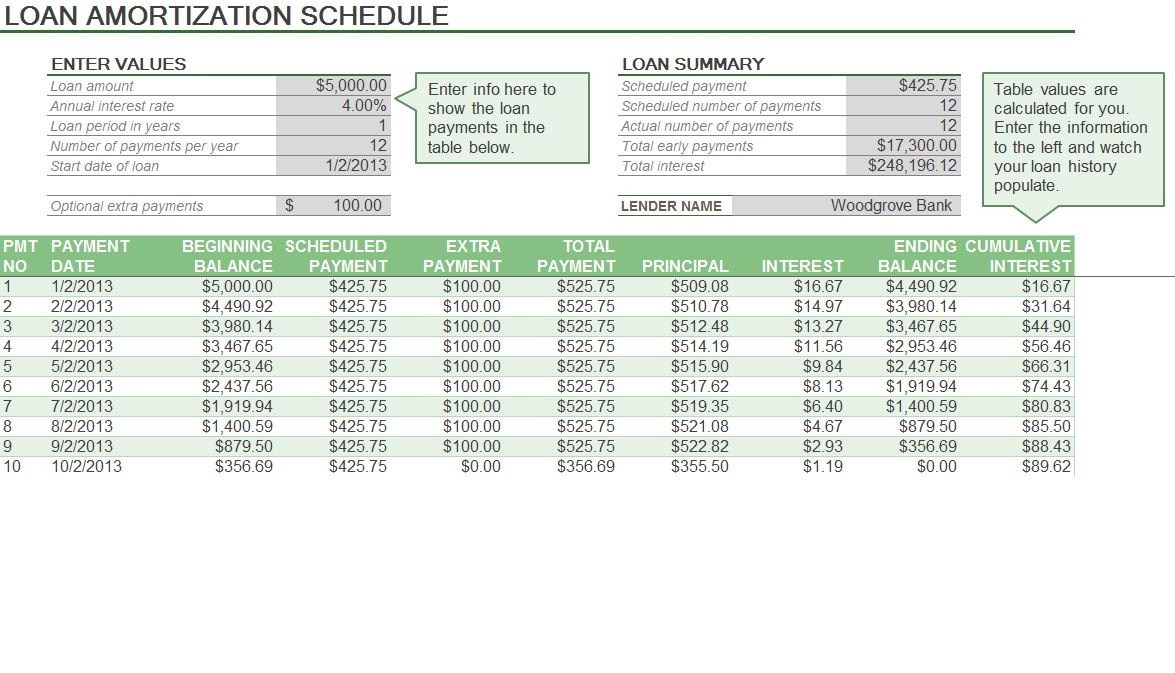
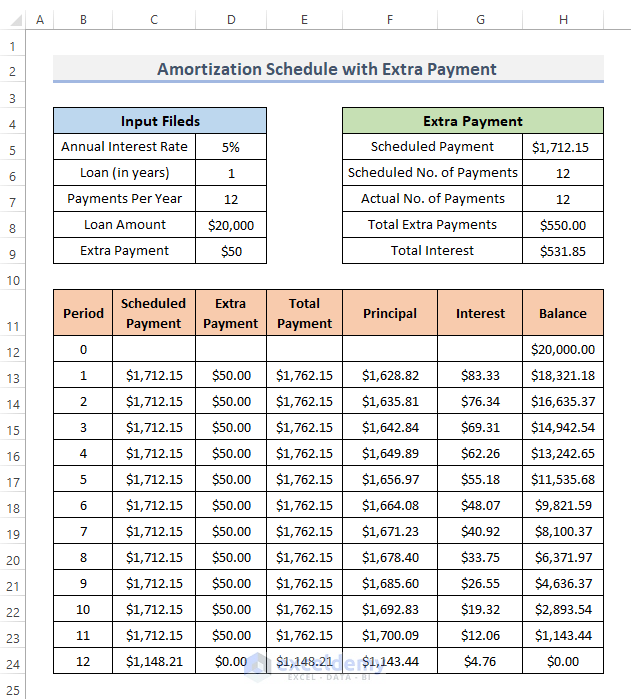
Most online calculators show you what happens when you throw money at a mortgage, but they don't let you model your actual payment strategy. The built-in spreadsheet tools are fine for static scenarios, but they break the moment you want to test different extra payment amounts month to month. I built my own system after spending too many evenings toggling between three different web calculators trying to figure out whether paying an extra $200 in certain months made sense versus spreading it evenly. The core structure is eight columns. You need Payment Number, Beginning Balance, Regular Payment, Extra Payment, Total Payment, Principal Portion, Interest Portion, and Ending Balance. That's it. Everything else flows from there. Set up your constants in separate cells somewhere on the sheet — annual interest rate, monthly interest rate (annual divided by 12), loan amount, and total number of scheduled payments. Don't hardcode values into formulas. Put them in cells and reference them. When you change the interest rate to see what happens, you'll thank yourself later.
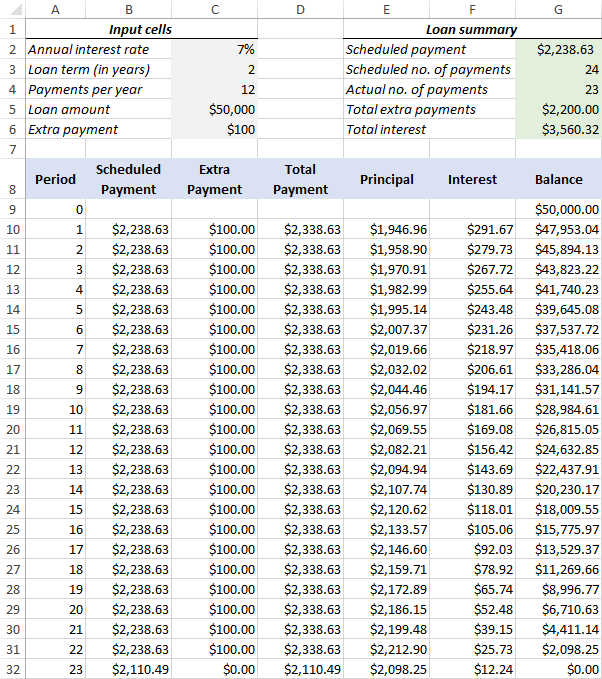
Row one starts with the original loan balance. The ending balance of row one feeds directly into the beginning balance of row two. That linkage is what makes the whole thing work. The interest portion is always beginning balance times monthly rate. The regular payment amount comes from the PMT function. Here's where it gets fiddly: when you add an extra payment, the principal portion is regular payment plus extra payment minus interest. The ending balance is beginning balance minus that principal portion. Simple on paper. Messy when your extra payment accidentally pays off the loan early and the final payment needs to be adjusted. Edge case I ran into: I was modeling a refinanced loan where the borrower made extra payments during the summer months only. The schedule looked clean until month 31, where the remaining balance was $847.32 and the regular payment was calculated as $1,423.18. The formula wanted to overpay the loan by $575.86. My workaround was adding an IF statement in the final row: if the ending balance would go negative, cap the total payment at the beginning balance times one plus the monthly rate. It cost me about ten minutes to implement and saved me from drawing conclusions based on broken numbers.
How Extra Payments Actually Change the Schedule
Most people think extra payments shave time off the loan linearly. They don't. The interest in any given month is calculated on the remaining balance, so every extra dollar goes entirely to principal and immediately reduces the interest base for all future months. The compounding effect is exponential, not additive. I once had a client who was convinced that adding $300 monthly would cut his 30-year loan to roughly 20 years because he did the math wrong — he just divided the total interest by the new monthly payment. The real answer was closer to 23 years. The difference matters when you're making a decision about whether to divert that money toward extra payments or something else. The critical thing nobody explains clearly: the timing of your extra payment matters more than the total amount in many cases. An extra $500 in month one saves significantly more in total interest than an extra $500 in month 180 of a 360-month loan. That's because the earlier payment reduces principal sooner, which reduces interest accrual on a larger number of subsequent months. People tend to dump their bonuses into the later years of a mortgage and wonder why the savings feel underwhelming.
Get the Full Details
Common Pitfalls That Break Your Schedule
The biggest mistake is assuming every extra payment automatically goes toward principal. At many servicers, it doesn't unless you specify it in writing. Some servicers will apply undesignated extra payments to future installments instead of current principal. Your amortization schedule will look beautiful on paper while your actual bank statement tells a completely different story. I've seen spreadsheets prove the math was right while the borrower was still making regular payments on the side. The fix is to verify with your servicer how undesignated payments are handled before you model them into your schedule. Another trap: rounding errors. If you round each monthly principal and interest to two decimal places and then carry those rounded numbers forward, you'll drift from the true balance. By month 60, the discrepancy is usually a few dollars. By month 300, it can be significant. Use full precision in your formulas and round only for display. Excel keeps enough decimal places internally that you won't see the drift unless you force it. A smaller but real issue is prepayment penalties. Some loans, particularly certain refinances or non-QM products, have declining prepayment penalties that eat into the benefit of extra payments in the early years. I worked with someone who modeled aggressive prepayments on a loan with a five-year penalty window and nearly made a costly mistake before catching it. Check your loan documents. If there's a prepayment clause, factor it in or the whole analysis is meaningless.
When This Approach Falls Apart
Amortization schedules with extra payments assume a fixed-rate loan with predictable payments. They don't work well for adjustable-rate mortgages because the interest rate changes, which changes the payment, which changes the entire structure mid-stream. You'd need to rebuild the schedule every time the rate adjusts, and the complexity grows fast. They also don't account for things like escrow shortages, late fees, or partial payments that get held until the next cycle. If your servicer has a practice of holding undesignated payments for two months before applying them, your timeline shifts. I learned this the hard way with a secondary property where the servicer applied my June extra payment toward July's installment instead of reducing principal in June. The schedule I'd built showed a different outcome than what actually happened. Always confirm with your actual servicer, not just what the textbook says. For most people with a standard fixed-rate mortgage, building this schedule in Excel takes about 20 minutes if you've done it before, or roughly 45 minutes the first time. Once it's set up, testing different scenarios — what if I pay $200 extra each month, what if I make one extra payment a year, what if I double the principal in year three — takes about five minutes per scenario. The real value isn't in building the thing. It's in running the variations and actually seeing what changes before you commit money to a strategy that might not do what you expect.