How to Build a Working Amortization Spreadsheet Excel
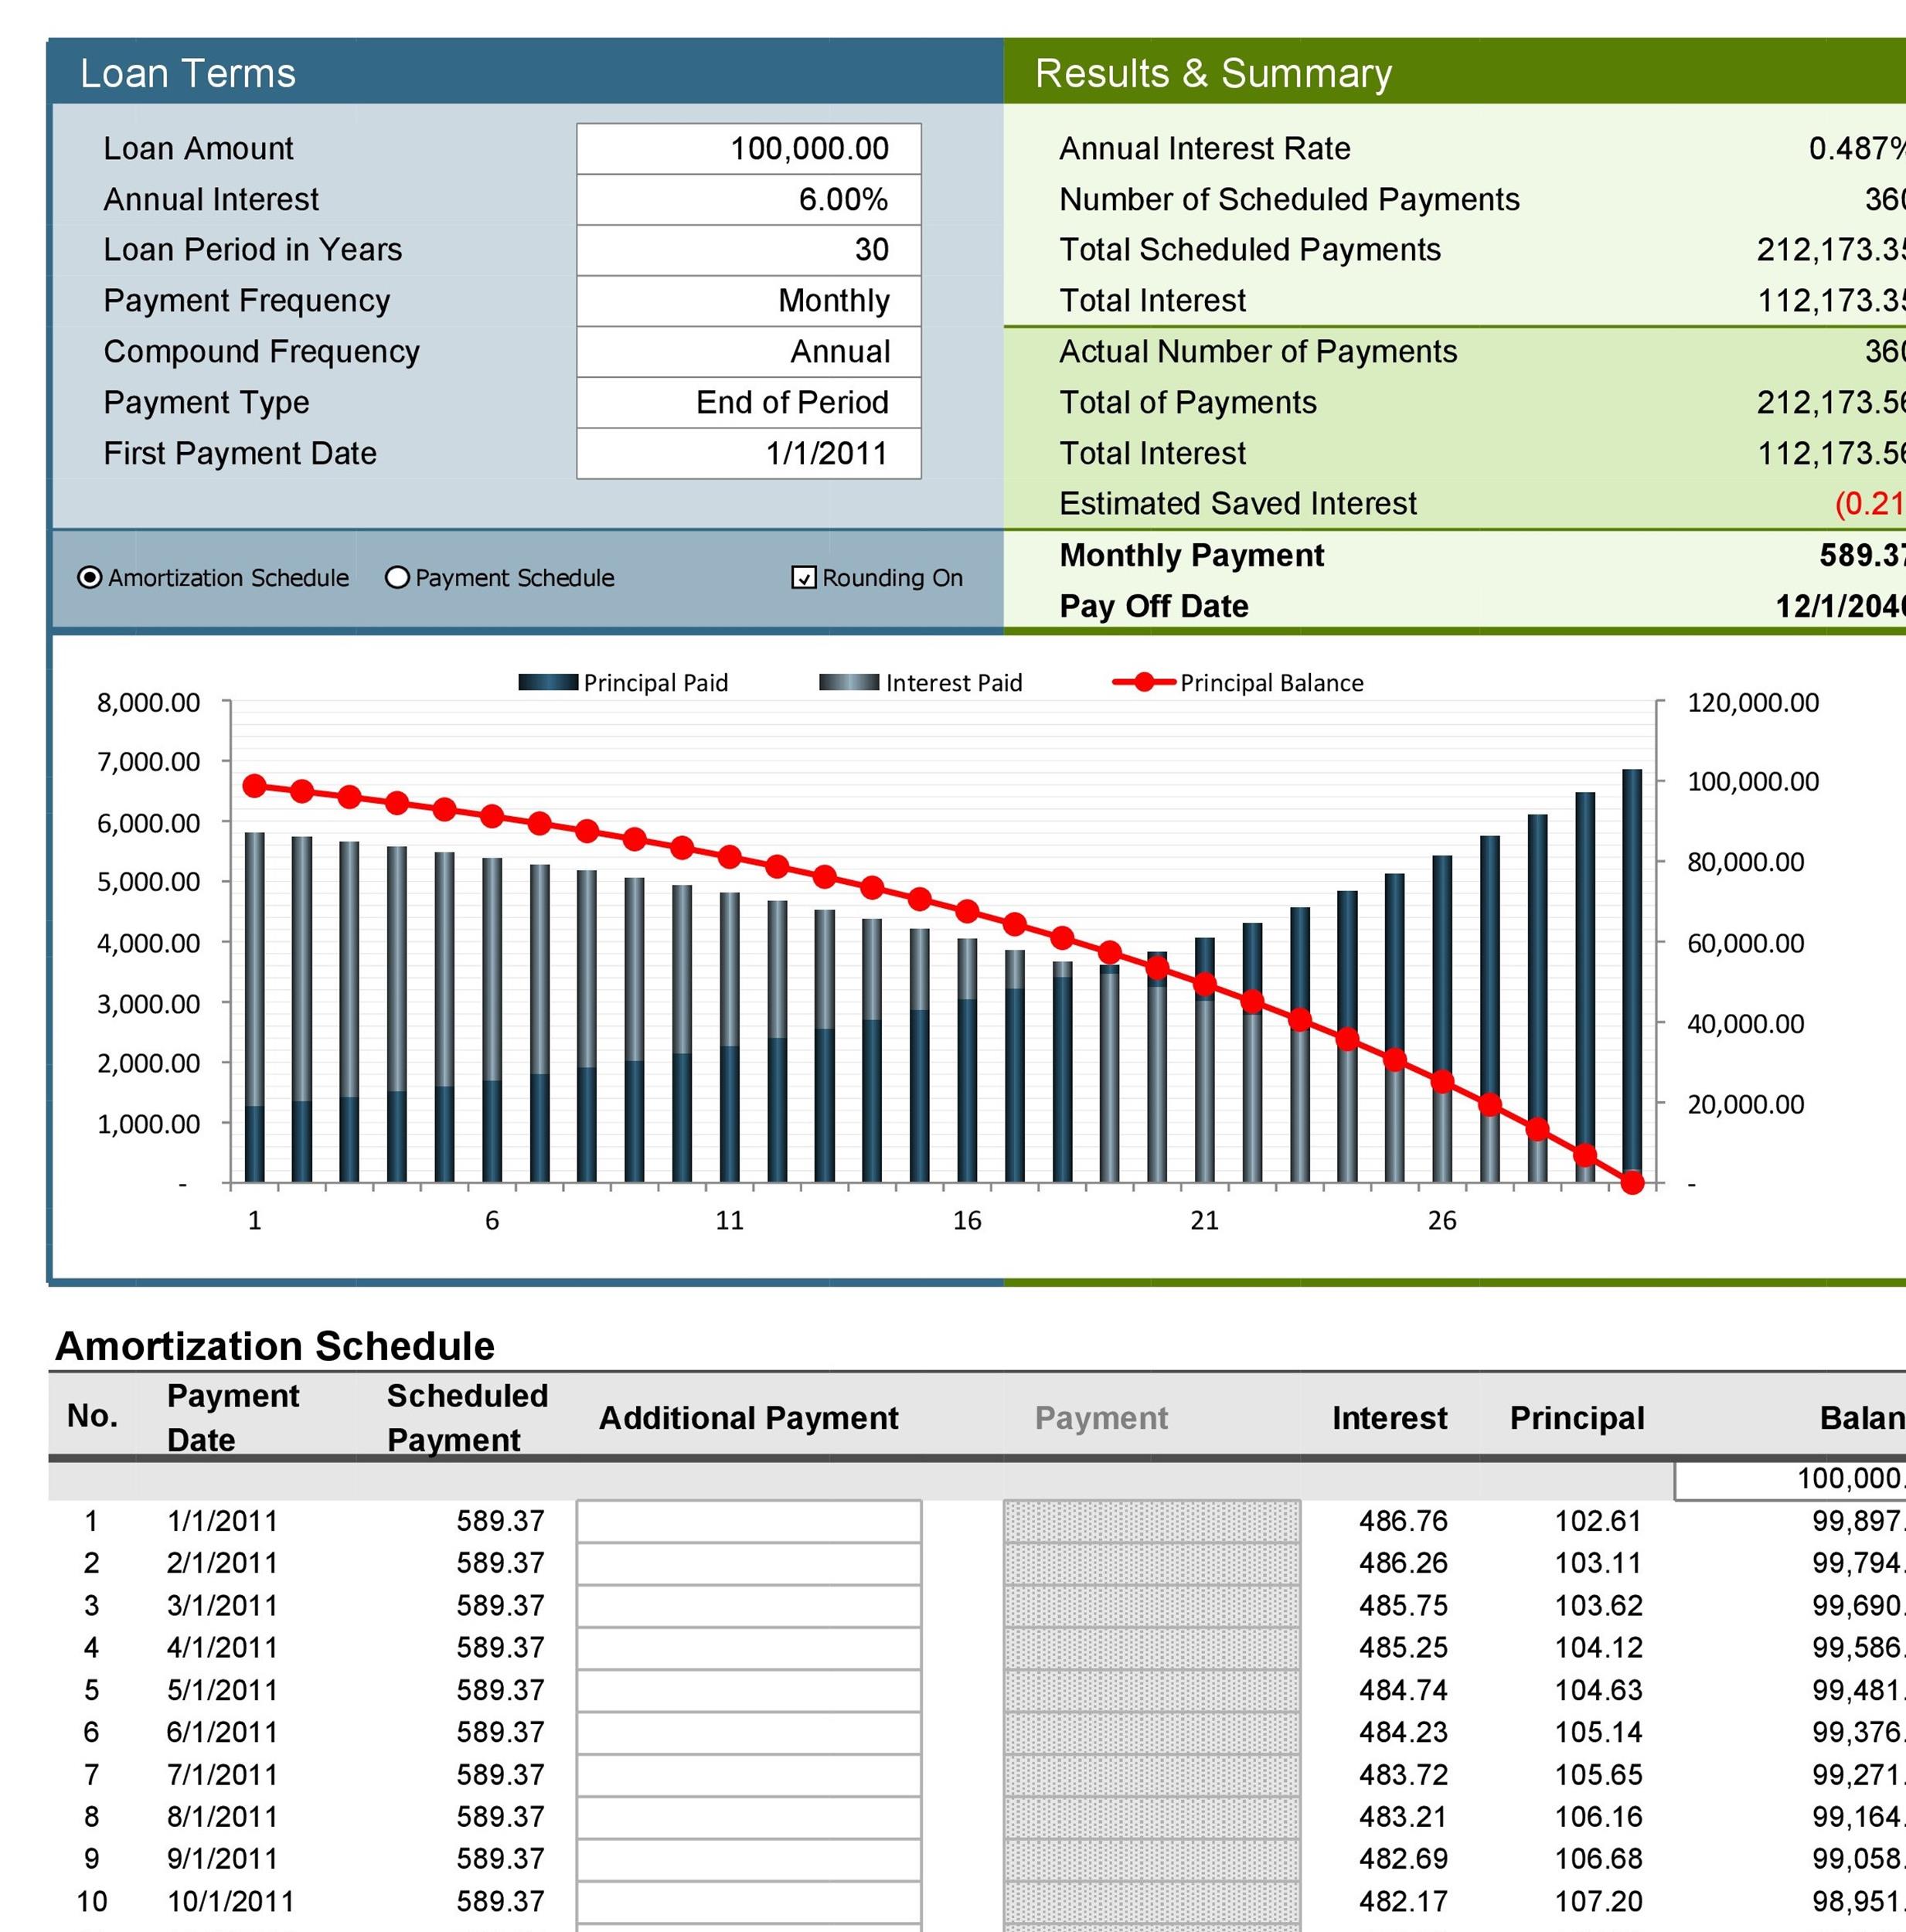
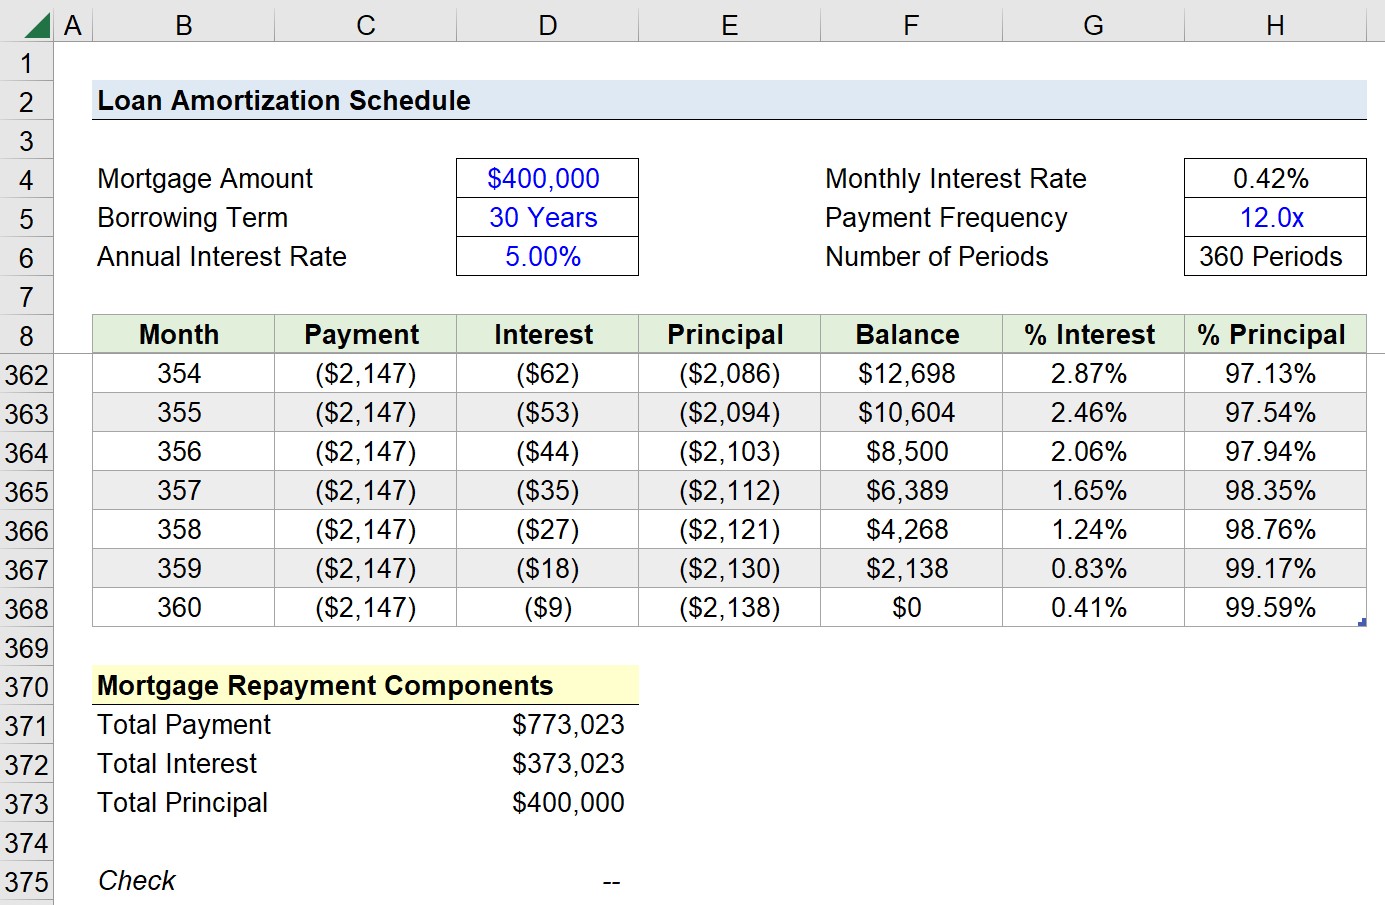
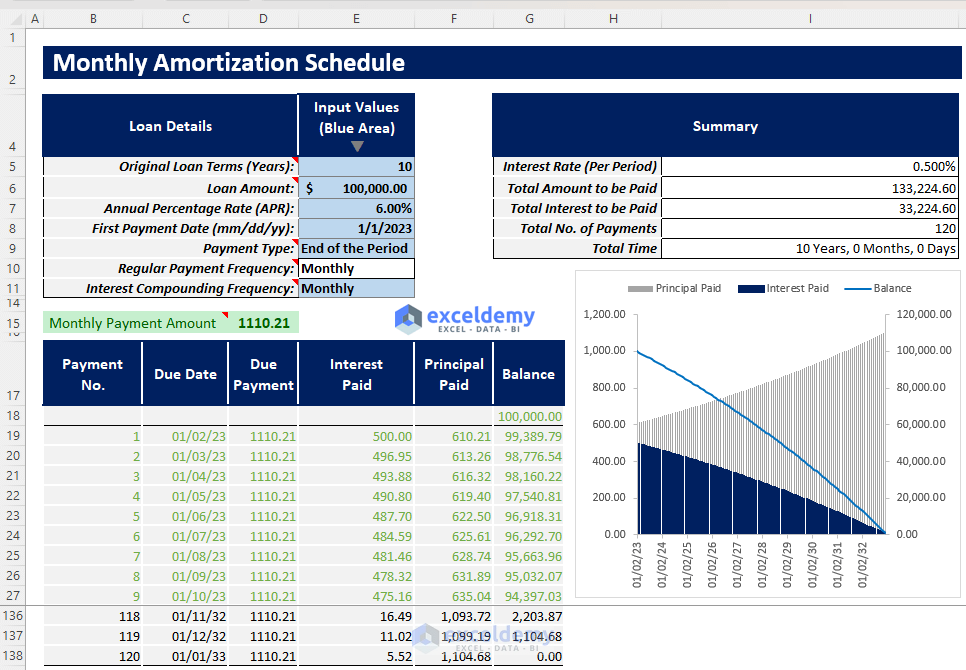
You need five columns and a handful of formulas. The rest is just copying and dragging. Start with these headers: Period, Payment, Principal, Interest, Remaining Balance. That's it. You then need your three loan inputs somewhere at the top — loan amount, annual interest rate, and total number of payments. Label them clearly. The payment formula goes in the Payment column. Use =PMT(rate/12, nper*12, -loan_amount). The negative sign on the loan amount is intentional — it flips the sign so your payment displays as a positive number. Without it, you get a negative payment and spend time wondering why. The principal and interest columns use two separate functions. =PPMT(rate/12, period, nper*12, -loan_amount) gives you the principal portion for that specific period. =IPMT(rate/12, period, nper*12, -loan_amount) gives you the interest portion. They should add up to your total payment every single row, within rounding error. If they don't, your rate or period count is wrong.
The remaining balance column is where most people mess up. Row 1 is your starting loan amount. Row 2 subtracts the principal payment from that balance. Each subsequent row subtracts its own principal from the previous row's balance. The formula in B3 would be =B2-C3, where B is the balance column and C is the principal column. Drag that down for the entire loan term. I spent three hours once trying to debug a schedule where the final balance was off by forty dollars. The issue was that the PMT function returned a rounded figure, and after thirty-six months of payments, the rounding drift added up. I solved it by adding a check formula on the last row: =IF(remaining_balance0.01, 0, remaining_balance). Then I manually adjusted the final principal payment to force the balance to exactly zero. This is called a drop payment adjustment, and it's normal on real loan schedules.
Common Pitfalls That Nobody Warns You About
The biggest mistake is assuming that CUMPRINC and CUMIPMT will work for anything other than perfectly regular payments. These functions calculate cumulative principal and interest between two periods, but they assume equal payments and equal compounding periods. If you have a balloon payment, variable rate adjustment, or biweekly schedule, they give you incorrect results. I learned this the hard way when a client asked for the total interest paid in years two and three of an adjustable-rate mortgage, and my cumulative function was off by several hundred dollars. Another issue is the compounding period versus payment period mismatch. Your interest rate should be divided by however many compounding periods happen per year, not necessarily by twelve. Most personal loans compound monthly, but some commercial loans compound semi-monthly or daily. Using the wrong divisor throws off every single calculation in your schedule. Check your loan documents for the compounding frequency before you start. There's also a subtle problem with very long amortization periods. On a thirty-year loan, the interest portion stays high for a long time. The first few years, you might be paying mostly interest with barely any principal reduction. This is normal, but if you're showing this to someone who expects rapid equity buildup, they'll be surprised. A thirty-year loan at 6 percent pays roughly $1,800 in interest per month in the beginning, with only about $300 going toward principal. That doesn't change until year seven or eight.
Get the Full Details
When This Approach Breaks Down
A standard amortization spreadsheet Excel model works well for fixed-rate loans with equal monthly payments and no prepayments. Once you introduce anything irregular — extra principal payments, missed months, payment holidays, or variable rates — the simple model falls apart. You'd need to either rebuild the schedule row by row with conditional logic or switch to a dedicated loan management tool. The spreadsheet also becomes unwieldy past about sixty periods. Copy-pasting formulas is fine up to thirty years of monthly payments, but anything beyond that and you're managing hundreds of rows manually. For commercial loans with fifteen-year terms or longer that include periodic rate resets, consider using a purpose-built calculator or database instead. The time you save is real, and the accuracy is higher. One more thing that trips people up: tax implications. The interest portion of your payment is what matters for deduction purposes, not the total payment. If you're building this for tax planning, separate those columns clearly and label them. Mixing them up costs you money at filing time, and it's an expensive mistake to make.
If you want a template, search for "amortization schedule template" in Excel's built-in template gallery. Microsoft maintains a basic version that follows the structure I described. It's functional but minimal — it won't handle extra payments or rate changes. For anything beyond a standard mortgage or car loan, you're better off building the model from scratch using the formulas above. That way you know exactly what each cell is doing instead of trusting a black box. The whole process takes about twenty minutes from start to finish if you know what you're doing. Setting it up correctly the first time saves you from having to rebuild it later when you discover the assumptions were wrong. Pay attention to the compounding frequency and the sign convention on your PMT formula. Those two things cause more errors than everything else combined.