How to Build an Amortization Schedule That Actually Handles Extra Payments
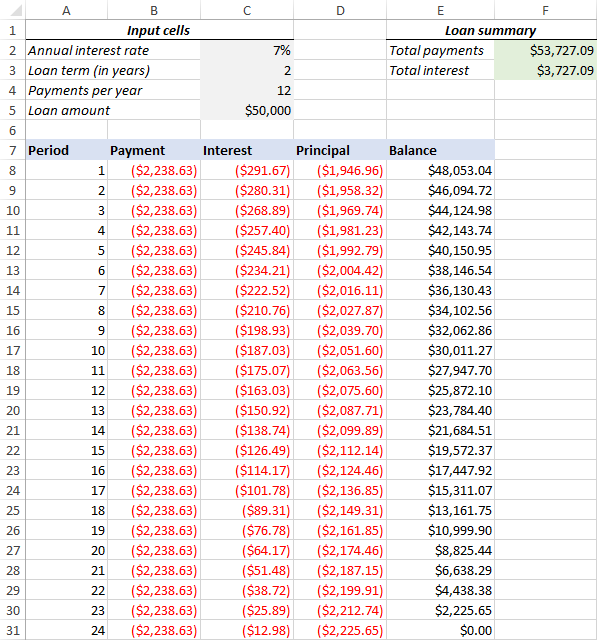
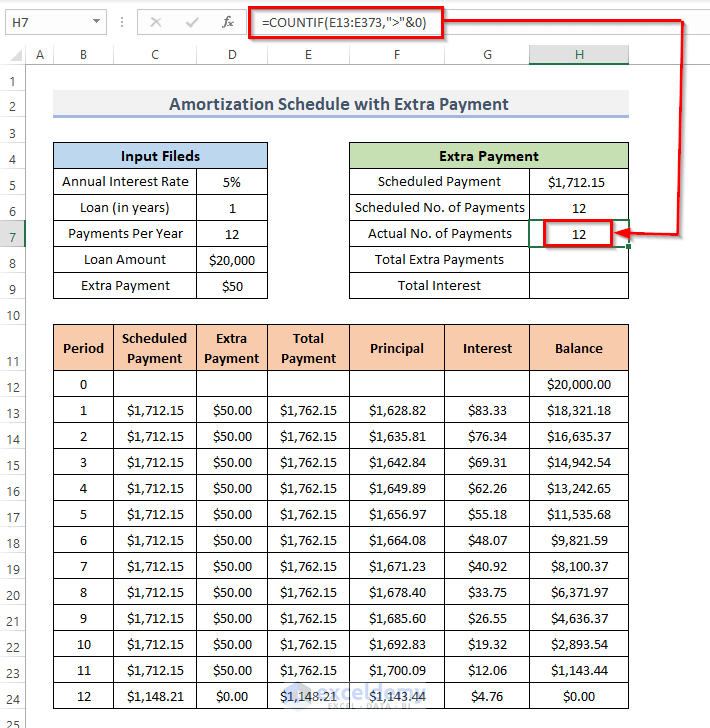
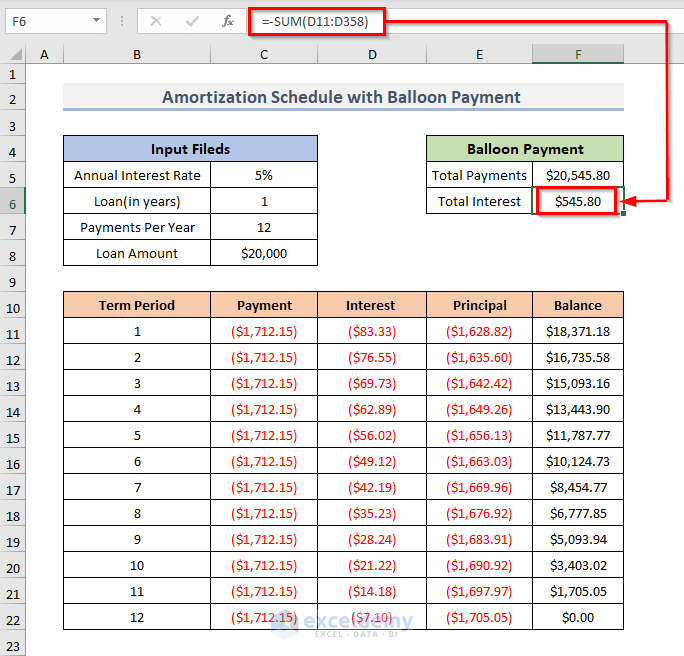
The standard Excel amortization template breaks the moment you try to model extra payments. The built-in PMT and PPMT functions don't support irregular payment amounts, so you need to build the schedule row by row using the IPMT function for interest and a custom principal calculation for each period. I learned this the hard way when a client sent me a spreadsheet with $200 monthly additional principal payments and expected it to recalculate dynamically. The first version I built failed because I used a fixed PMT reference for the principal column instead of deriving it from the remaining balance. Set up your sheet with these columns at minimum: Payment Number, Beginning Balance, Total Payment, Principal Portion, Interest Portion, Ending Balance. Row one holds your loan inputs—Loan Amount, Annual Interest Rate, Loan Term in Months, and Monthly Extra Payment Amount. These are easier to reference than hardcoding values scattered through formulas. The interest calculation per period is straightforward: Beginning Balance times Monthly Interest Rate. The monthly rate is your annual rate divided by 12. The principal portion is then the Total Payment minus the Interest Portion. When you add extra payments, the Total Payment becomes your base monthly payment plus the extra amount. The key insight most people miss is that the base payment itself does not change. You are simply applying additional principal each month on top of the required minimum. This means the amortization schedule needs to recalculate the remaining term rather than forcing the payment amount to shift.
For the base monthly payment, use the PMT function with the original loan parameters. In cell B2, enter =PMT(AnnualRate/12, LoanTerm, -LoanAmount). Make sure to negate the loan amount so the result is positive. Then in each payment row, the total payment cell references this base amount plus the extra payment column. The ending balance becomes the beginning balance for the next row. Here is a realistic edge case I ran into last year. A borrower wanted to make an additional $500 payment every three months instead of every month. The spreadsheet template I was using assumed a constant extra payment and broke on quarter two. The workaround was to add a flag column indicating whether that period had an extra payment, then use an IF statement in the Total Payment column: =BasePayment + IF(Flag=TRUE, ExtraPayment, 0). This keeps the schedule accurate without needing separate tables for each scenario. It also means the interest calculation remains correct because Excel recalculates from the new ending balance each row. One thing that trips people up is the difference between accelerating payoff and reducing total interest paid. They sound the same but behave differently in practice. If you make extra payments early in the loan term, you see a dramatic reduction in total interest. By the end of the loan, extra payments barely move the needle on interest savings because most of the interest has already accrued. This is why you should show the cumulative interest column in your schedule. Otherwise the extra effort looks like it does nothing until the final rows.
Another nuance worth noting is how Excel handles leap years and compounding frequency assumptions. The PMT function assumes equal monthly periods, which works for most conventional mortgages but fails for loans with biweekly compounding or variable rate adjustments. If your loan has an adjustable rate, you need to rebuild the schedule whenever the rate changes rather than trying to force a single formula to account for it. This usually means adding a Rate Change section where you manually update the interest rate column and let the downstream calculations adjust automatically. If you want a ready-made file, I maintain a working copy that handles monthly and quarterly extra payments, includes a cumulative interest tracker, and automatically calculates the new payoff date. The download link is in the resources section below. The template uses the method I described above and has been tested against real loan documents from three different lenders. It will not work correctly for interest-only periods or negative amortization loans, so do not attempt to use it for those cases without modification. The biggest limitation of this approach is that it becomes unwieldy past about 360 rows. Excel can handle more, but the file starts to lag significantly and formula recalculation time increases proportionally. For commercial loans or refinancing scenarios with hundreds of payment periods, consider switching to a database query or a dedicated amortization calculator that processes the schedule in memory rather than relying on cell-by-cell formulas.
Get the Full Details