Why Most Company Analysis Falls Apart Before It Starts
I've spent enough years reading through financial statements and pitch decks to know where the rot usually begins. It's not in the formulas. It's in the assumptions people refuse to question because they're too attached to a conclusion they already want to reach. Analysis Of A Company isn't about running numbers through a model and trusting the output. It's about finding out what the numbers are actually hiding. Let me give you a direct example from a few years back. I was reviewing a mid-cap manufacturing company that everyone liked because it had consistent double-digit revenue growth and a seemingly reasonable P/E ratio. The problem wasn't the growth itself. It was that the accounts receivable balance was growing twice as fast as revenue, and the company was booking revenue on long-term contracts using percentage-of-completion accounting without any real project milestones to back it up. When I pushed for the raw contract data rather than the summarized financials, the picture changed completely. Revenue was being recognized before it was realizable. This is the kind of thing that doesn't show up in any pre-built financial model. You have to dig into the footnotes and cross-reference line items yourself.
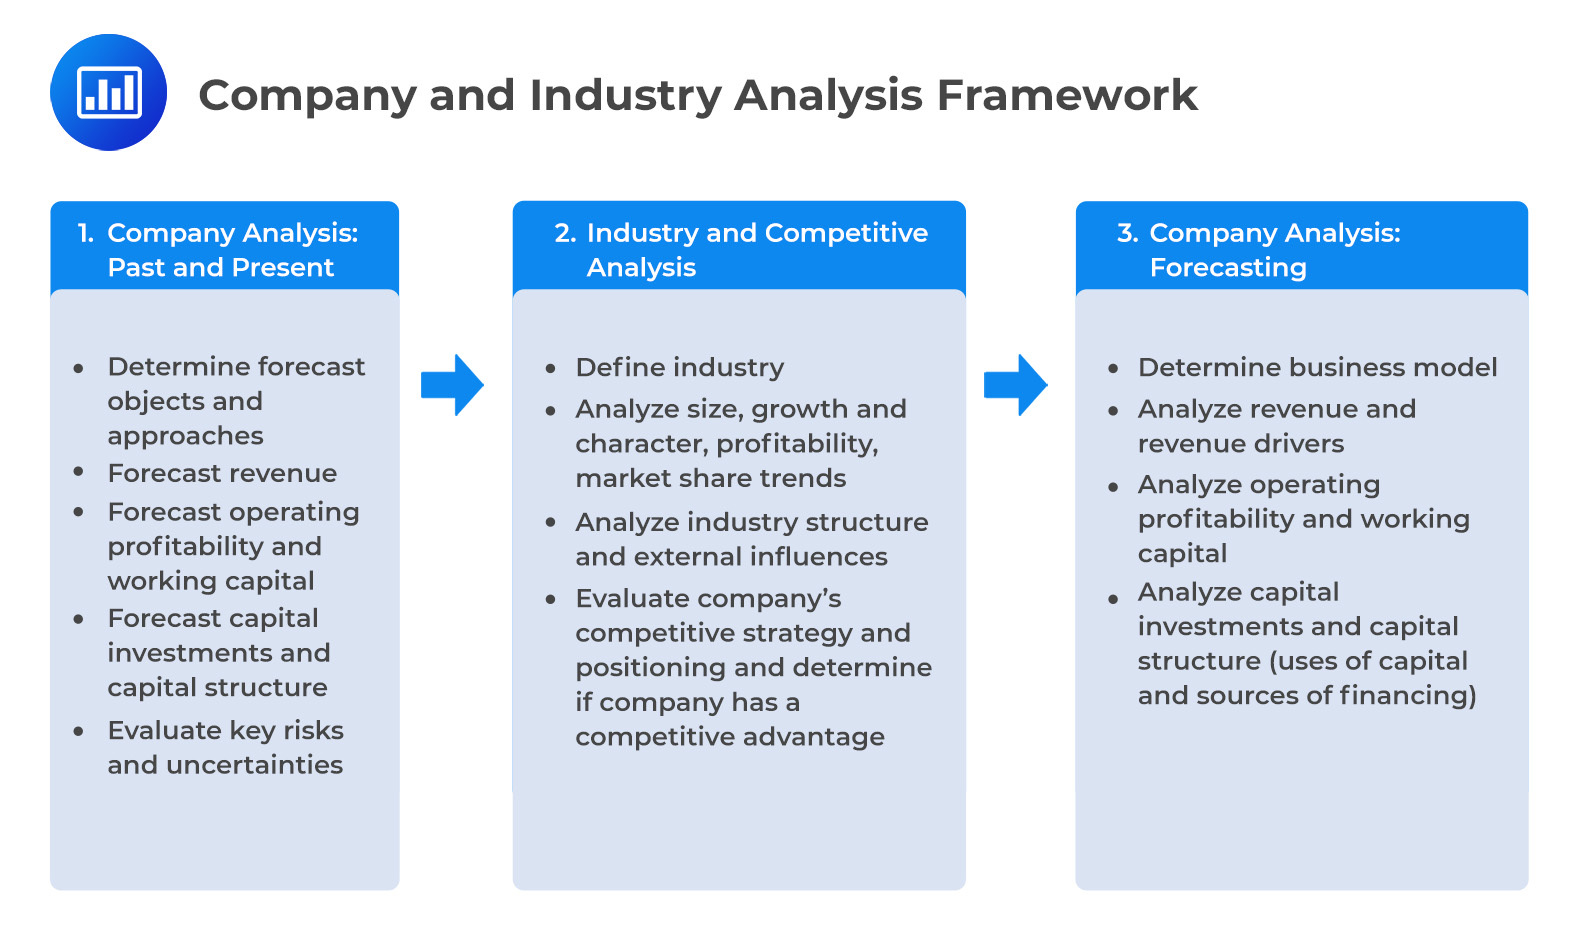
The Core Process of Analysis Of A Company
Start with the three financial statements, but don't treat them independently. The income statement is a narrative that the balance sheet either supports or undermines, and the cash flow statement is the final verdict on whether that narrative is true. I've seen too many analysts fall in love with a company's gross margin expansion on the income statement without noticing that inventory build-up on the balance sheet means those sales might not actually be happening. The cash flow statement resolves this conflict almost every time. The first thing I check is whether operating cash flow tracks net income over a full business cycle, not just the most recent quarter. If they diverge consistently over three to five years, something is off. Revenue recognition policies, aggressive expense capitalization, or off-balance-sheet liabilities are the usual suspects. I don't rely on any single ratio to tell me what's happening. I build a simple table showing revenue growth, operating cash flow growth, and net income growth side by side for at least five years. Patterns emerge quickly when you put them in front of you instead of interpreting them through the lens of a single metric.
Valuation Methods and Where They Break Down
Relative valuation using multiples is the most common starting point because it's fast. EV/EBITDA, P/E, P/B — these are useful for establishing a rough range, but they are terrible at capturing the actual economics of a business. I use multiples as a sanity check, not as a conclusion. If a company trades at a significant discount to its peers, I don't assume it's undervalued. I assume I'm missing something, and my job is to find out what. Discounted cash flow models are the other standard tool, and they suffer from a different problem: they give an illusion of precision. You type in a growth rate and a discount rate, hit enter, and suddenly you have a fair value number. The issue is that small changes in your assumptions produce enormous swings in the output. I built a DCF once for a consumer company where changing the terminal growth rate from 2.5% to 3.0% increased the implied valuation by 25%. That's not analysis. That's rearranging variables until the answer matches what you want it to be. Here's what I do instead. I build a simple unlevered free cash flow projection for three years using only the most conservative assumptions I can justify, then I calculate a terminal value using a low growth rate and a high discount rate. If the company is still attractive under those conditions, I proceed. If the valuation depends on optimistic assumptions to work, I discard it. This approach rarely produces elegant results, but it keeps you from being fooled by your own model.
Get the Full Details
Competitive Positioning and Moats
Everyone talks about economic moats, and almost everyone uses the term loosely. A real moat is something that prevents competitors from eroding returns on capital over time. Network effects, switching costs, and regulatory barriers are genuine examples. Brand alone is not a moat unless it translates into pricing power that competitors cannot challenge. Cost advantage is only a moat if it's structural and persistent, not just a temporary efficiency. When I evaluate a company's position, I look at return on invested capital trends first. Consistent ROIC above 15% with stable or expanding margins usually indicates a real competitive advantage. ROIC above 15% that is declining year over year suggests the advantage is eroding, and the market may not have noticed yet. I also examine the company's capital allocation history. A management team that consistently buys back shares at high valuations or makes acquisitions that destroy value is a red flag regardless of how good the current business looks. I recall analyzing a logistics company that appeared to have a strong cost advantage due to its regional hub network. The numbers supported the thesis on the surface. But when I traced through the capital expenditure requirements needed to maintain that network, the economics were thin. New competitors with different hub strategies could erode the advantage with relatively modest investment. The moat existed in theory but not in practice. This is the kind of finding that requires looking past the headline metrics to the underlying capital intensity and competitive dynamics.
Risk Assessment Beyond the Obvious
The biggest mistake I see in company analysis is focusing on risks that are already known and priced in while missing the risks that aren't. Interest rate changes, commodity price swings, and regulatory shifts are all important, but they're usually reflected in the current valuation. The risks that matter are the ones that could fundamentally alter the business model without anyone in the market realizing it yet. I always ask what would make this company worthless within five years. Not risky. Worthless. For a SaaS company, the answer might be a shift in how enterprises purchase software that bypasses the vendor entirely. For a retailer, it could be a change in consumer behavior driven by technology that makes their core value proposition irrelevant. For a manufacturer, it could be automation or offshore competition that destroys the cost advantage. Identifying these scenarios forces you to think about the business differently and prevents you from accepting surface-level narratives. Credit risk is another area that gets overlooked. I check the debt maturity schedule, the interest coverage ratio, and the terms of any covenants. A company with significant near-term refinancing obligations in a rising rate environment is in a different category than one with long-dated fixed debt. This isn't subtle. The information is in the filings. But it's easy to skip if you're focused on growth and multiples.
Common Pitfalls That Waste Time and Money
One recurring mistake is treating accounting earnings as equivalent to economic earnings. Earnings can be manipulated through changes in depreciation methods, inventory valuation, and reserve estimates. Free cash flow is harder to manipulate, but it's not immune. Companies can delay payables, accelerate receivables, or defer maintenance capital expenditures to boost short-term cash flow. None of these are sustainable. I look at the trend, not the single year. Another pitfall is over-reliance on forward guidance. Management guidance is a tool for managing expectations, not a reliable forecast. I use it as one data point among many, but I don't build an investment thesis around it. The companies that consistently beat guidance often do so by cutting expenses that hurt long-term competitiveness, or by recognizing revenue earlier than they should. Beating guidance is not the same as creating value. The third major pitfall is ignoring the balance sheet entirely. I've seen analysts build elaborate income statement models for companies that were ultimately killed by debt maturities they never accounted for. A company can have beautiful growth and margins and still go bankrupt if it can't refinance. The balance sheet tells you whether the company can survive a downturn. The income statement tells you whether it can thrive during normal conditions. You need both.
Practical Tools and Resources
For gathering financial data, SEC filings remain the most reliable source for U.S. companies. The 10-K contains the audited financials and the notes, which are where most of the important details live. The 10-Q provides quarterly updates, but the quarterly notes are much shorter and less detailed. For international companies, I use the equivalent regulatory filings from the relevant jurisdiction, though the quality and availability vary significantly by country. Several databases and platforms make this easier. Bloomberg Terminal and Refinitiv Eikon are comprehensive but expensive. For individual analysts, platforms like Capital IQ, Morningstar Direct, or even free tools like the SEC's EDGAR system combined with financial data sites like Motley Fool or Yahoo Finance can work adequately. The tool matters less than your ability to question what the data is telling you.
What This Approach Can't Do
Company analysis, no matter how thorough, cannot predict the future. It can only help you estimate the probability of different outcomes based on available information. Markets can remain irrational longer than you can remain solvent, and there will always be companies with attractive fundamentals that stay unappreciated for years. Good analysis improves your odds. It does not guarantee success. The most skilled analysts I know are the ones who are most comfortable admitting when they don't know what will happen next. The goal isn't to be right. The goal is to avoid being dramatically wrong. Most investment losses come from a small number of catastrophic mistakes rather than from many small errors. Rigorous analysis helps you identify and avoid the mistakes that matter. It won't eliminate risk, but it will make your risk decisions intentional rather than accidental.