What Actually Matters When You Look at an Insurance Company
Most people approach insurance company analysis the same way they'd analyze a tech firm, which means they start in the wrong place. A 15x P/E ratio tells you almost nothing about whether a property casualty insurer is attractively priced. The earnings are too dependent on underwriting cycle swings and investment income volatility to be useful on their own. You need to understand the mechanics first, then the numbers follow. Insurance companies produce three sets of financial statements, and they often tell different stories. The statutory statements filed with state regulators are the most conservative. They're what determine capital requirements and dividend capacity. The GAAP statements, found in your typical 10-K, include more assets and show higher reported earnings. Then there's the LOMCR or loss management operating result, which strips out investment gains and accounting adjustments to show what the underwriting business actually produced. I spent about three weeks trying to reconcile differences between these reports for a mid-size regional insurer. The statutory surplus was $2.1 billion, the GAAP equity came in at $3.4 billion, and the LOMCR showed a combined ratio of 94%, while the GAAP operating income looked nowhere near as clean. The gap wasn't fraud. It was mostly reinsurance accounting, deferred acquisition costs, and the fact that statutory reserves use different actuarial methodologies. Once I stopped trying to force them to agree and instead read each one for what it was built to show, the analysis took maybe an afternoon instead of three weeks.
The Core Ratios and Where People Go Wrong
Two ratios get the most attention and usually get misinterpreted. The combined ratio is supposed to tell you whether underwriting is profitable. A number below 100% means the company is making money on premiums before investment income. But here's what the combined ratio doesn't tell you: it doesn't capture the timing risk of long-tail reserves. A property casualty writer might show a 97% combined ratio while simultaneously building or releasing reserves in ways that obscure true profitability. The loss ratio alone is even more misleading. A company might report a 60% loss ratio one year and a 75% loss ratio the next, and an amateur would call that deterioration. What actually happened is the first year had an unusually low large-loss occurrence, and the second year absorbed a single $200 million hurricane claim that skewed everything. Look at the three-year average, and look at the frequency-severity breakdown if the company breaks it out. The expense ratio, written as a percentage of premiums, tells you how efficiently the company operates. Most well-run P/C insurers sit between 22% and 28%. If you see an expense ratio above 30% for a company that isn't running a capital-intensive distribution model, something is probably wrong or they're competing in an overly expensive market.
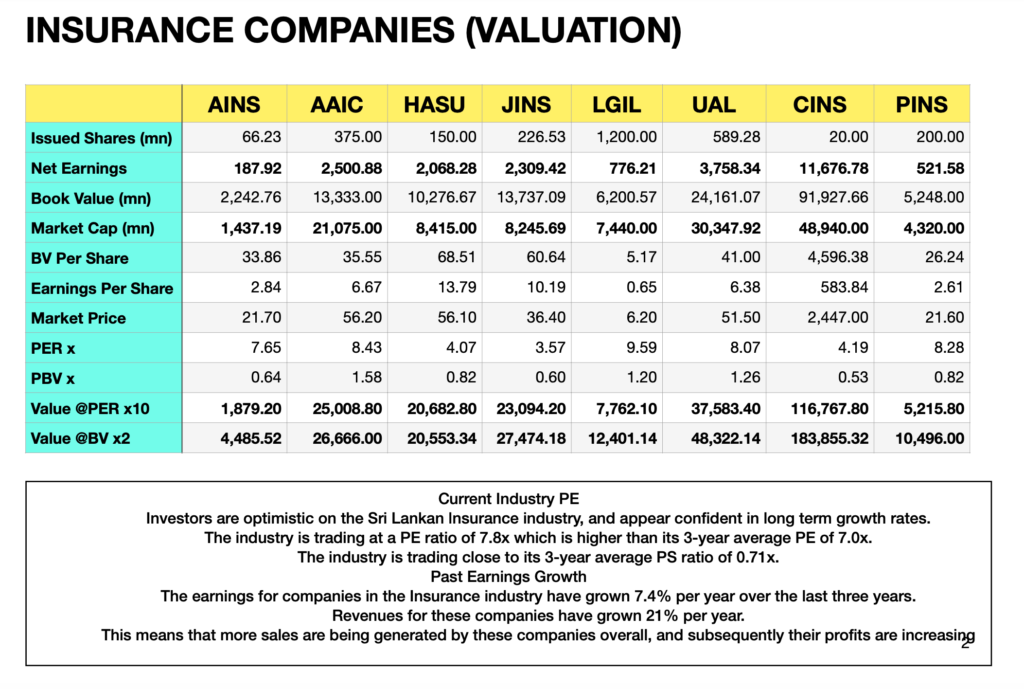
Then there's the price-to-book ratio, which matters more than P/E for insurers. Underwriting profits get buried in earnings fluctuations, but book value is relatively stable year to year. A P/B below 1.0x doesn't automatically mean a bargain. It could mean the market thinks the surplus is eroding through bad underwriting or that the reserves are inadequate. A P/B above 2.0x for a company that can't maintain underwriting discipline is where the real risk hides, because the market is pricing in continued float value that may not exist.
Get the Full Details
Analysis Of Insurance Companies Really Comes Down to Three Questions
The first question is whether the underwriting engine works on a cycle-neutral basis. Look at the combined ratio over at least two full underwriting cycles, which in property casualty typically spans five to seven years depending on catastrophe experience. If a company consistently posts a combined ratio below 98% over multiple cycles, the management team knows what they're doing. Above 100% over two cycles is a warning flag regardless of how good the investment income looks. The second question is whether the balance sheet can survive a bad year. Reserve strength matters here. Look at the statutory surplus, the risk-based capital ratio, and the reinsurance recoverables. I once flagged a company whose RBC ratio appeared healthy at 310% until I dug into the reinsurance section of their annual statutory filing. They had $400 million in reinsurance recoverables from a cedent that was itself financially stressed. The adjusted RBC, excluding that recoverable, dropped to 195%. That's the kind of detail most analysts miss because they're looking at summary metrics rather than the notes. The third question is whether the float is actually creating value. Naumann's rule of thumb says an insurer should be able to underwrite at near breakeven and still generate attractive returns because the float is free or negative cost capital. If the combined ratio consistently runs above 103% and investment yields are modest, the float is a liability, not an asset. The company is essentially paying for the privilege of holding your money.
Reserve Development and the Quiet Profit Engine
Reserve development is where actual insurance profitability gets revealed, and it's also where management can smooth earnings most easily. When an insurer sets loss reserves, they're estimating what future claims will cost. Those estimates are almost always wrong. If the company releases reserves over subsequent years, that release flows directly into earnings and makes the combined ratio look better than the underlying loss experience was. If reserves run unfavorable, earnings take a hit that may not show up until quarters later. The Standard &Poor's reserve development tables, published annually, track exactly this. Look at cumulative unfavorable development over the last five years. A company that consistently releases reserves year after year is either exceptionally skilled at reserving or possibly cooking the books. Consistent unfavorable development is the more common red flag, and it usually means the company was too optimistic when setting reserves initially. On the flip side, some companies use reserve releases as a crutch to meet earnings targets. I worked through a case where a regional insurer's reported combined ratio looked stellar at 95%, but the reserve release contributed roughly 4 percentage points of that improvement. Strip out the release and the actual underwriting result was a 99% combined ratio. Still acceptable, but nowhere near as impressive as the headline number suggested.
Reinsurance: The Double-Edged Sword
Reinsurance reduces catastrophe exposure and stabilizes underwriting results, but it also compresses margins. A company that cedes 40% of its premiums is keeping less of the premium dollar and accepting lower returns on surplus. The key is whether the ceded reinsurance is protecting against tail risk or just being used to manage earnings volatility. There's a difference. Look at the net versus gross written premiums. If net WIP is significantly lower than gross WIP, the company is heavily reliant on reinsurance. Check the counterparty quality of the reinsurers. A high concentration of ceded reinsurance with weaker-rated carriers adds credit risk that doesn't show up in the underwriting metrics. The annual statutory filing's schedule of reinsurance will list this information, but most people don't read past the summary pages. I once passed on a insurer that looked cheap on P/B at 0.8x. The combined ratio was 96%, reserves looked adequate, and the float cost was negative. The deal fell apart when I reviewed the reinsurance schedule and found that 60% of their retrocessional coverage was with a single carrier rated B+. One adverse development event at that carrier could have wiped out years of underwriting profit. The market didn't price that in because nobody was looking closely enough at the retro cessions.

Reading the Management Discussion
MD&A sections in 10-Ks are usually filler, but insurance companies sometimes reveal useful information if you know where to look. The discussion of loss reserve development, the commentary on catastrophe experience, and any mention of changes in reserving methodologies are worth examining closely. Management might say they adopted a new reserving model that improved consistency. That could mean better actuarial practice or it could mean they found a way to set reserves more optimistically. Watch for changes in terminology. When a company starts referring to "core underwriting income" instead of operating income, or introduces new adjusted metrics that exclude items previously included, that's often a signal that the underlying numbers aren't meeting expectations. It's not always deceptive, but it deserves scrutiny.
Pitfalls That Even Experienced Analysts Miss
One common mistake is treating all insurance segments the same. A diversified insurer might have a strong P/C unit offset by a weak life or annuity division. Life insurers face completely different dynamics because their liabilities are interest-rate sensitive in ways property casualty liabilities aren't. The valuation framework for a pure life insurer is fundamentally different. Mixing them together produces incoherent conclusions. Another mistake is ignoring the investment portfolio composition. An insurer with a high concentration of commercial mortgage-backed securities or unrated municipal bonds carries investment risk that isn't reflected in underwriting metrics. The 2008 financial crisis exposed this repeatedly. Companies that looked fine on combined ratio grounds collapsed because their investment books contained toxic assets. Check the schedule of investments in the annual filing for asset quality concerns. Interest rate sensitivity matters more for some insurers than others. Life and annuity writers carry massive duration-mismatch risk. When rates move, the economic value of their reserves shifts dramatically. P/C insurers are less exposed to this, which is why they're easier to value in a stable rate environment but can struggle when rates shift rapidly.
What This Analysis Can't Tell You
Financial analysis of insurance companies has hard limits. Catastrophe modeling is inherently uncertain. A single Category 5 hurricane making landfall in a concentrated market can wipe out three years of underwriting profit in a single quarter. No amount of combined ratio analysis predicts that. Actuarial assumptions can change based on new judicial interpretations, legislative shifts, or emerging claim trends that models haven't captured yet. The method also struggles with specialty lines where historical data is thin. Insurtech products, cyber insurance, and pandemic-type covers don't have enough loss history to produce reliable reserve estimates. Companies writing these lines may appear to have attractive combined ratios simply because they haven't had claims yet, not because the pricing is accurate. If you're evaluating a pure play life insurer in a falling rate environment, the traditional P/B framework breaks down somewhat because book value becomes a moving target driven by discount rate assumptions. In those cases, looking at embedded value or using a discounted cash flow approach tailored to the liability structure gives you a more useful picture than standard insurer multiples.

A Practical Workflow
Start with the most recent annual statutory filing and the latest 10-K. Pull the combined ratio trend over ten years, noting catastrophe years separately. Check reserve development tables for cumulative favorable or unfavorable development. Review the reinsurance schedule for counterparty concentration. Calculate the expense ratio and compare it to peers. Look at the P/B relative to historical averages and peer group medians. Then go back and read the MD&A and the actuarial opinion for context on whatever surprised you in the numbers. This process usually takes me about four to six hours for a first pass on a company I haven't covered before. If the numbers look interesting, a deeper dive into the actuarial methodology and competitor positioning adds another couple of hours. Anything that requires more than a day of research at the preliminary stage is usually a sign that the information isn't transparent enough to make a confident call. The analysis of insurance companies is fundamentally about separating durable competitive advantages from temporary underwriting luck. The metrics exist for that purpose. The challenge is knowing which ones actually move when the cycle turns and which ones just look good on a spreadsheet during a soft market.