The difference matters more than most people think
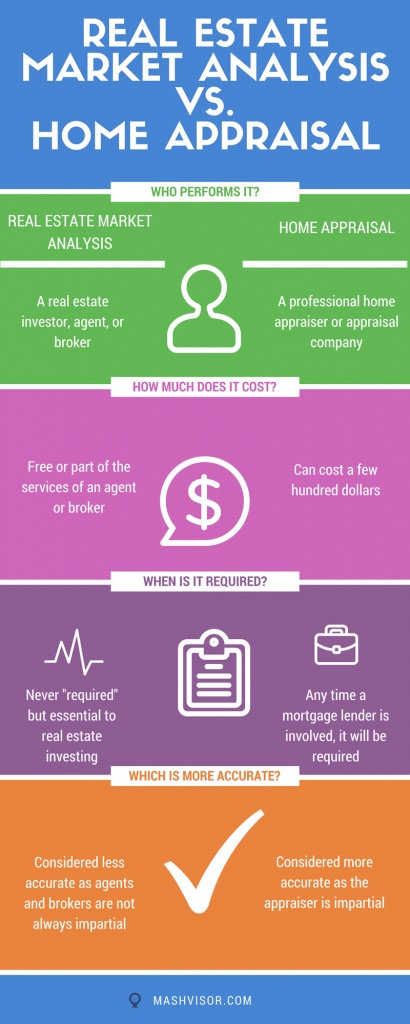
When I first got into valuation work, I treated the two words as interchangeable. That lasted about six months before a client flagged my report and asked why I'd given them a market value number derived from an income approach when the assignment was clearly for liquidation purposes. The discrepancy came from me performing an analysis instead of an appraisal, and the correction cost me a week of my time and the client's patience. They're related but fundamentally different disciplines. Analysis is a process of breaking something down into its component parts and examining how those parts interact. You look at data, you identify patterns, you draw conclusions about what the numbers are telling you. An appraisal takes that finished analytical work and attaches a formal opinion of value to it. The appraisal is the deliverable; the analysis is what supports it. Here's where people routinely mess it up. They'll run a comparable sales analysis and call it an appraisal. What they've actually done is compile data and maybe calculate a mean or median. An appraisal requires standardized methodology, documented assumptions, reconciliation of approaches, and a concluded opinion of value that stands up to scrutiny. The difference between a spreadsheet with formulas and a defensible appraisal opinion is usually about fifteen pages of supporting documentation that nobody reads but everyone demands.
I remember working on a commercial property review last year where the original appraiser had conflated the two entirely. The analysis portion was thorough but the appraisal conclusions were based on three comps from different submarkets with no adjustment narrative. I spent two days reconstructing the market study before I could even begin evaluating whether the value opinion held water. That's the most common failure mode I see in practice. The proper workflow runs like this. You start with the analysis phase where you define the problem, collect relevant data, and apply analytical techniques like regression modeling, discounted cash flow construction, or direct comparison methodology. Once the analytical framework produces a set of value indications, you move into the appraisal phase where you reconcile those indications into a single concluded value. The reconciliation step alone typically accounts for forty to sixty percent of the total effort in a standard residential or light commercial assignment. There's a counter-intuitive point that beginners miss. A more sophisticated analysis doesn't always produce a better appraisal. I've seen complex discounted cash flow models with twenty-two line items produce less reliable conclusions than a straightforward sales comparison approach with six well-adjusted comparables. The analysis is only as good as the input assumptions, and those assumptions are almost always where the real uncertainty lives. Garbage in, garbage out applies to both disciplines equally.
Another thing worth noting is the regulatory distinction. In the United States, a licensed or certified appraiser must follow the Uniform Standards of Professional Appraisal Practice when performing an appraisal. Analysis has no such governing framework. You can perform a rough financial analysis any way you want without violating any professional standards. That flexibility is useful but it's also exactly what makes an uncredentialed analysis easy to challenge in any dispute setting. If you need to actually perform both correctly, here's the practical sequence I use. Begin by writing down the specific question you're answering. Then gather all relevant data before you touch any formulas. Run your analysis using at least two independent methods whenever possible. Document every assumption explicitly with a source. Only after you've completed the analysis should you write the appraisal narrative that ties everything together. Skipping that narrative step is the single most common reason appraisals get rejected during quality control reviews. There are scenarios where the line between analysis and appraisal blurs deliberately. Market studies, feasibility analyses, and highest and best use opinions are analytical products that sit just to the left of a formal appraisal. They use the same tools and techniques but stop short of delivering a concluded value opinion. Knowing where that cutoff happens matters because crossing it without proper credentials can create legal exposure.
Get the Full Details

The downsides of treating them as separate phases are real but manageable. The main bottleneck is time. A proper analysis-appraisal sequence on a standard four-unit residential property takes me approximately six to eight hours from data collection through final reconciliation. When I compress that process by skipping the reconciliation documentation, I cut it to roughly two hours but the resulting appraisal isn't durable under review. The tradeoff is consistent and predictable. For anyone looking to get started with these skills, the core references are the Uniform Standards of Professional Appraisal Practice handbook, the Appraisal Institute's textbooks, and actual reviewed appraisal reports from your local assessment office. Reading completed appraisals line by line teaches you more than any course material because you can see exactly how the analysis transitions into the concluded opinion. That transition section alone is usually where the entire credibility of the document lives or dies. Software tools don't replace the judgment required at either stage. I use Excel for the analytical calculations and specialized appraisal software for the report formatting, but the substantive work happens in your head, not in the program. The tools just automate the mechanical parts that used to take half a day by hand. Modern spreadsheet templates can handle a full sales comparison grid in about ten minutes now versus the two hours it took when I started out doing it manually.
Where this falls apart
Both analysis and appraisal fail when the underlying data is unreliable or incomplete. There's no methodological workaround for bad inputs. If you're working with outdated comparable sales, inconsistent zoning records, or subjective condition ratings, your analytical conclusions will be precise but wrong, and your appraisal opinion will be confidently stated but unsupported. This happens constantly in rapidly shifting markets where the data lags behind current conditions by three to six months. The other failure point is scope limitation. When a client restricts access to property information or limits the types of data you can examine, you can still produce an analysis of what's available but you cannot and should not produce an appraisal. The difference between those two deliverables under restricted scope conditions is the difference between a useful internal document and a professionally defensible opinion. Confusing them is how liability problems start. I recommend keeping a separate analytical workbook alongside every appraisal engagement. The appraisal report contains the conclusions; the workbook contains the reasoning. When a review appraiser or opposing expert needs to challenge your work, the workbook is what either protects you or exposes you. Most people skip building one and then regret it immediately when questions arise.
The relationship between analysis and appraisal is sequential and interdependent. The analysis feeds the appraisal. The appraisal gives the analysis its formal purpose. Treating them as the same thing produces work that looks reasonable at a glance and falls apart under any serious examination. That examination usually comes eventually. If you want downloadable templates for either the analytical worksheet or the standardized appraisal report format, the Appraisal Institute and various state appraisal boards publish their own. Those are the right starting points rather than generic spreadsheet templates found online because they're structured around the actual standards that govern the work.