The Actual Work Of Keeping Business Finances Balanced
Most small business owners think balancing their accounts means running a report and hoping the numbers match. They open QuickBooks or Xero, hit "reconcile," and if the ending balance lines up with their bank statement, they call it done. That is not actually balancing anything. That is just confirming that your software and your bank agree. The real work happens between those two numbers, in the gaps where transactions slip, categorize wrong, or disappear entirely. I learned this the hard way around 2018, running consulting work for a mid-size e-commerce company. Their monthly P&L looked clean every time. Bank reconciliation came back matching. But cash flow was bleeding out quietly. Turns out, one of their payment processors was booking fees in two different accounts, and since the total outflow still matched their bank statement, the reconciliation tool never flagged it. The income went here, the expense went there, and the category drift was invisible to anyone who only looked at the balance column. I spent three weeks rebuilding their chart of accounts with sub-accounts mapped to each revenue stream and each fee type, then set up weekly automated discrepancy reports that compared gross receipts minus fees against actual deposited amounts. This caught the bleed within two weeks. It took me about six hours to build the system that would have saved them $4,000 a month in undetected miscategorization.
What And Balances In Business Actually Looks Like
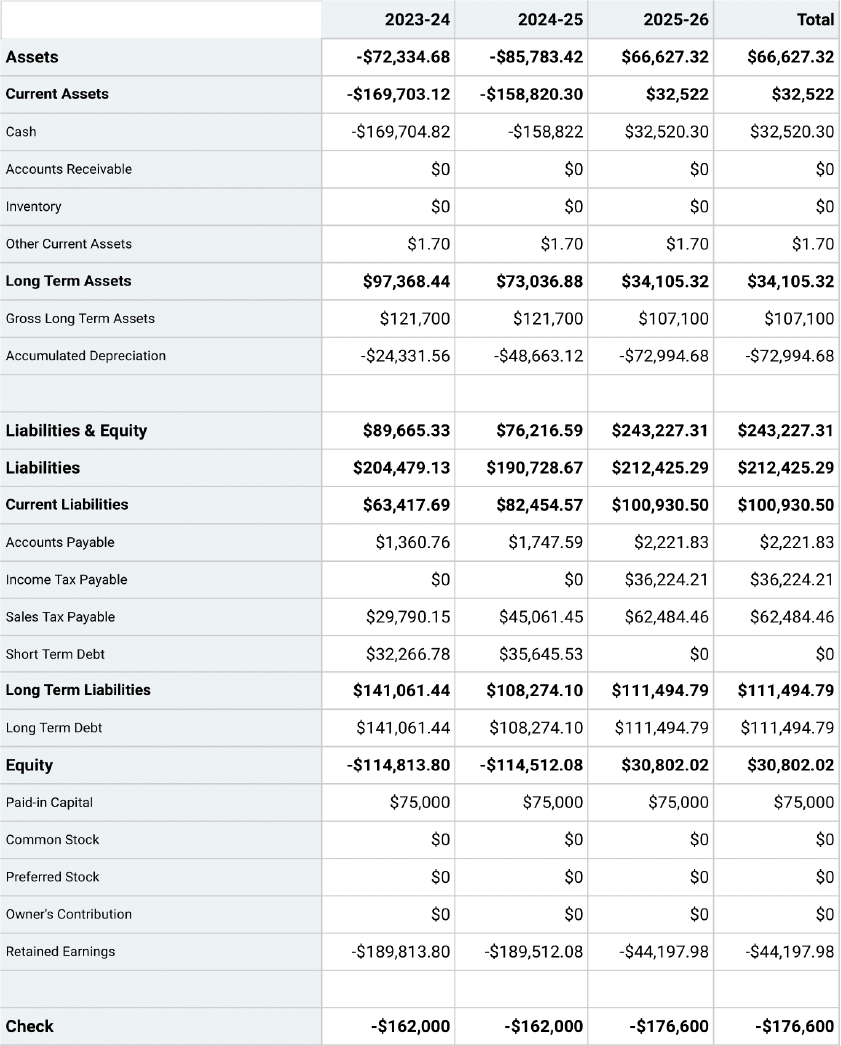
At its core, balancing in a business context means ensuring that what you record, what your bank records, and what you actually have available are all telling the same story. When any one of those three drifts apart from the others, you are flying blind. The accounting identity itself is simple enough — assets equal liabilities plus equity — but the operational reality of maintaining that equation month over month is where people get lost. Here is the practical side most guides skip: balancing is not a monthly event. It is a continuous process that should happen at least weekly, ideally daily for any business processing more than fifty transactions per day. When you reconcile monthly, errors compound. A miscategorized vendor payment in March gets buried under April invoices, May subscriptions, and June refunds. By the time you notice the discrepancy, you are looking at four months of transaction history instead of four days. I keep my clients on a three-layer balancing system. The first layer is daily bank feed matching — automatic where possible, manual exceptions only. The second layer is weekly category audits, where I pull every transaction that moved outside its normal range and check it against source documents. The third layer is monthly reconciliation against the general ledger, which catches everything the first two layers missed. This takes roughly 45 minutes per week for a small business, or about 20 minutes if you have good automation set up. Without it, you are relying on hope.
Common Mistakes That Break Your Balances
The biggest mistake I see is treating reconciliations as a box-checking exercise. You match the closing balance, sign off, and move on. But if your bank statement shows a $3,247.89 ending balance and your book balance shows $3,247.89 because you forced a clearing account to zero with an unexplained adjusting entry, you have not reconciled anything. You have hidden the problem. Those adjusting entries are where actual errors live. If you see more than one or two per month, your bookkeeping process is broken somewhere upstream. Another frequent issue is double-counting revenue or expenses across systems. A business might record a sale in their POS, then again in their accounting software, or record a subscription expense in their bank feed and also manually enter it in the AP module. These do not always show up in reconciliation because both sides of the entry are correct individually. They only create problems when you pull a P&L or balance sheet. The fix is straightforward — pick one system as the source of truth for each transaction type and lock the other to read-only, then run a duplicate detection report monthly. There is also the timing problem, which hits service businesses especially hard. When you bill on the fifteenth but the client pays on the thirtieth, your balance sheet shows an account receivable that may never clear at the expected value. Late fees, partial payments, disputes — these create permanent discrepancies between what you recorded and what actually landed in your bank. I have clients who stopped trying to force every receivable into perfect sync and instead use a small allowance account for estimated timing differences. It is not theoretically clean, but it keeps the balances honest without generating hundreds of minutes of futile reconciliation work every month.
Get the Full Details
Building A System That Stays Balanced
Start with your chart of accounts. Most templates online are generic nonsense designed for a million different business types and therefore work well for none of them. Your chart should reflect how you actually operate, not how an accountant in 1987 wished you would operate. If you have three product lines, three service categories, and a warehouse operation, your account structure should map to that reality directly. Sub-accounts are fine for nesting, but more than three levels deep is just organizational theater at that point. Set up recurring reconciliation schedules with specific owners. "Someone checks the accounts" is not a schedule. I assign each account type to a specific person with a deadline — bank accounts by Tuesday, credit cards by Wednesday, payroll by Thursday. When someone owns the reconciliation, they actually do it. When it is collective responsibility, nobody does it until the end of the month when everything is worse. Automate the parts that can be automated and leave the rest for human judgment. Bank feeds should auto-match whenever there is a clear transaction-to-invoice link. Manual review should only happen when the automation cannot find a match or flags an anomaly. This typically cuts reconciliation time from three or four hours per month down to about thirty minutes, depending on transaction volume and how messy your data entry has been. The key metric is not how fast you reconcile but how often discrepancies surface. If your discrepancies always show up during monthly close, your process is too slow. If they show up within forty-eight hours of transactions occurring, you are doing it right.
One thing to watch for is the ghost transaction — a payment that your bank recorded but your accounting software never saw because it came through a channel you do not feed into your system. Third-party payment processors, Venmo for business, cash payments recorded in a separate app, even interest income that auto-deposits without an invoice backing it. These create balance gaps that look like errors but are actually just missing data sources. The workaround is to maintain a catch-all suspense account where unmatched deposits and withdrawals get held until they can be traced. This keeps your primary balances accurate while giving you a visible home for everything you cannot immediately classify. At the end of each month, every item in the suspense account must either be resolved or documented as a known pending item. Anything older than sixty days is a process failure that needs fixing.