Applied DNA Sciences trades under the ticker APDN on the Nasdaq. The company built its revenue around two main streams. The first is crop protection through Sentinel Seed Technologies, which uses DNA-based markers to protect seed varieties from unauthorized propagation. The second is forensic and identity testing, where they provide DNA testing services for wildlife law enforcement, food authentication, and some municipal forensic work. They also do product authentication, helping brands verify that what they're selling is actually what it claims to be.
The stock has spent most of its life as a small-cap penny type. Volume is thin, spreads are wide, and news moves the price more than fundamentals do most of the time. That matters because the company's revenue tracks are real but not massive. Sentinel alone doesn't generate enough to carry the whole valuation on its own. The forensic side brings in contracts but those tend to be lumpy government or institutional work rather than recurring consumer revenue.
Applied Dna Science Stock and Why It Moves
What makes this particular stock interesting to watch isn't the day-to-day trading. It's the binary events that hit it. A new contract announcement with a major seed company can send shares up twenty percent in a single session. A delay in forensic contract renewals can erase that same gain over the next week. The market doesn't know how to value the company consistently, which creates these violent oscillations.
I started paying attention to APDN around 2021 when I was tracking small-cap biotech plays for a friend's portfolio. We ran into a specific problem that took me a while to figure out. I was trying to calculate the true cost basis for a trade and the execution was a mess. The bid-ask spread on this stock routinely runs three to five cents wide, sometimes wider on light volume days. If you place a market order, you are basically gambling on what price you will actually get filled at. On a $4 stock with a four-cent spread, you are losing one percent before the trade even settles.
The workaround I ended up using was setting limit orders two ticks inside the quoted spread and being patient. You wait. Sometimes you don't get filled that session and that's fine. I also started checking the average daily volume before placing any order. If ADVR was below two hundred thousand shares, I would split my order size in half or walk away entirely. The stock just doesn't have the liquidity to absorb big orders without moving against you.
How the Business Actually Makes Money
Sentinel is their crown jewel right now. The technology works by embedding a unique DNA marker into seeds that can't be seen, can't be easily removed, and can be tested in a lab to prove origin. Seed companies pay licensing fees for this. Farmers who buy the seed also pay a technology fee. The model is recurring as long as the seed is planted, which makes the revenue somewhat predictable once contracts are locked in.
The catch is that adoption takes time. A seed company won't switch to Sentinel overnight because it requires changes to their breeding pipeline and their sales story to farmers. I saw this play out with one of their early adopter clients who reported that it took about eighteen months from initial agreement to full deployment across their major varieties. That's a long sales cycle for a small company to wait on.
Their forensic division serves agencies that need to prove wildlife trafficking or food fraud. These are government contracts and they come with their own set of rules. Procurement cycles stretch over quarters. Bids get delayed. Scope changes mid-contract. I worked with someone who bid on a state-level wildlife forensic contract through APDN's channel and learned the hard way that the RFP had a clause requiring ISO 17025 accreditation for the specific test methods being requested. The company had the general accreditation but not the method-specific one, so the bid was disqualified on a technicality. Make sure you read the fine print before you bet anything on these contracts.
Financials and Valuation Reality
Revenue has been climbing slowly. Recent filings show the company in the fifty to eighty million dollar range annually depending on which year you look at. Gross margins hover around forty percent, which is decent for a testing and licensing business but not spectacular. Operating expenses eat most of what's left, which is why the company has reported net losses in multiple quarters.
The balance sheet is generally clean with modest debt. Cash positions vary by quarter but tend to be adequate for ongoing operations. What worries me is the capital raise history. The company has diluted shareholders before through offerings, which compresses earnings per share and makes valuation comparisons across years unreliable. Always adjust your mental model for dilution when looking at historical metrics.
Valuing APDN is frustrating because standard P/E ratios don't work when earnings are negative. Price-to-sales is the more common metric people use, and it typically ranges from three to eight times trailing twelve-month revenue depending on market sentiment. That range is huge because the company isn't growing fast enough to justify the high end and isn't declining fast enough to justify the low end. It sits in this uncomfortable middle zone where the market can't agree on a fair price.
Counter-Intuitive Things About This Stock
Most beginners look at APDN and think the forensic DNA testing is the main growth driver. It's not. The real margin and recurring revenue potential lives in Sentinel and agricultural licensing. Forensic contracts are real money but they come with higher operational overhead and less predictability. If you're bullish on this stock, your thesis should really hinge on agricultural adoption rates, not courtroom testing volumes.
Another thing people miss is that APDN benefits from anti-counterfeiting trends in luxury goods and pharmaceuticals, but that segment is tiny relative to the overall picture. The product authentication work exists and it's legitimate, but it's not a material revenue contributor. Don't let marketing materials about brand protection inflate your expectations about where the growth will come from.
The Downsides You Should Accept Upfront
This stock has real bottlenecks. Liquidity is the first one. You will occasionally find yourself unable to exit a position quickly without taking a significant hit on the spread. I've held positions where I wanted out and couldn't sell more than twenty percent of my shares in a single day without moving the price against myself.
Second, the company's research and development burn is real. They invest in new test methods and new agricultural partnerships, and that spending doesn't always convert to revenue on the timeline investors hope for. There was a period where they announced three new Sentinel licensing deals and the stock dropped because the market questioned whether those deals would actually produce revenue in the current fiscal year. Announcements and actual cash collection are two different things.
Third, regulatory risk exists on the agricultural side. Gene editing and biotechnology regulations shift between administrations and across states. A change in how DNA-marked seeds are classified could slow adoption or add compliance costs. The company hasn't been directly hit by a major regulatory shift yet, but the exposure is there.
A More Liquid Alternative
If you want exposure to the same general idea but with better liquidity and deeper institutional coverage, look at Thermo Fisher Scientific or Danaher. They serve adjacent markets in forensics and life sciences with far more trading volume and lower transaction costs. You won't get the same small-cap volatility, but you also won't get stuck in a position you can't exit.
If you're set on the direct play, accept that this is a illiquid small-cap with binary news risk and position accordingly. Size it so that being stuck for two weeks doesn't matter. Set limit orders. Watch the volume before you enter. Read the contract details on any forensic bid. The fundamentals are real but the trading experience is rough.
Gallery Applied Dna Science Stock
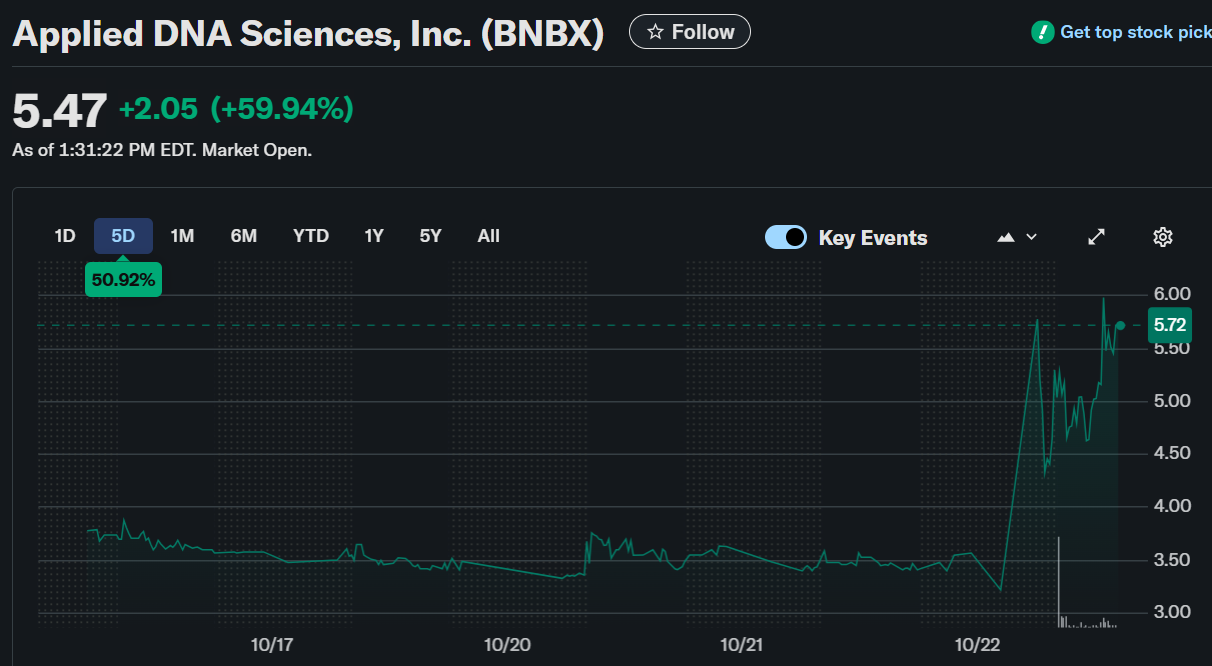
Applied DNA Sciences, Inc. (BNBX) Stock: Soars 35% After $27M PIPE Financing and BNB Treasury ...
APPLIED DNA SCIENCES (APDN) Stock Trade Results | Profit.ly
Applied DNA Sciences Inc (APDN) Stock Analysis: 14.94% Surge & Strategic Restructuring | March ...
Applied DNA Sciences Inc Stock (APDN) Falls Over 5%. Should You Buy the Pullback? - YouTube
😲👀 APDN Stock | Technical Analysis And Predictions | Applied DNA Sciences Stock | create website ...