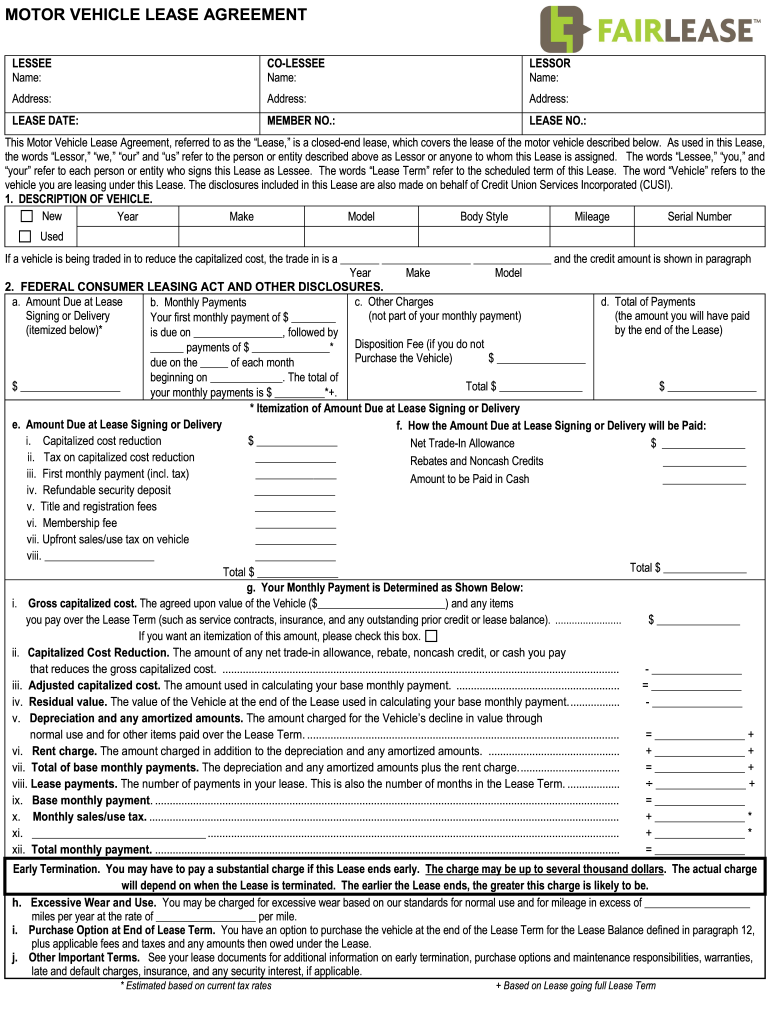
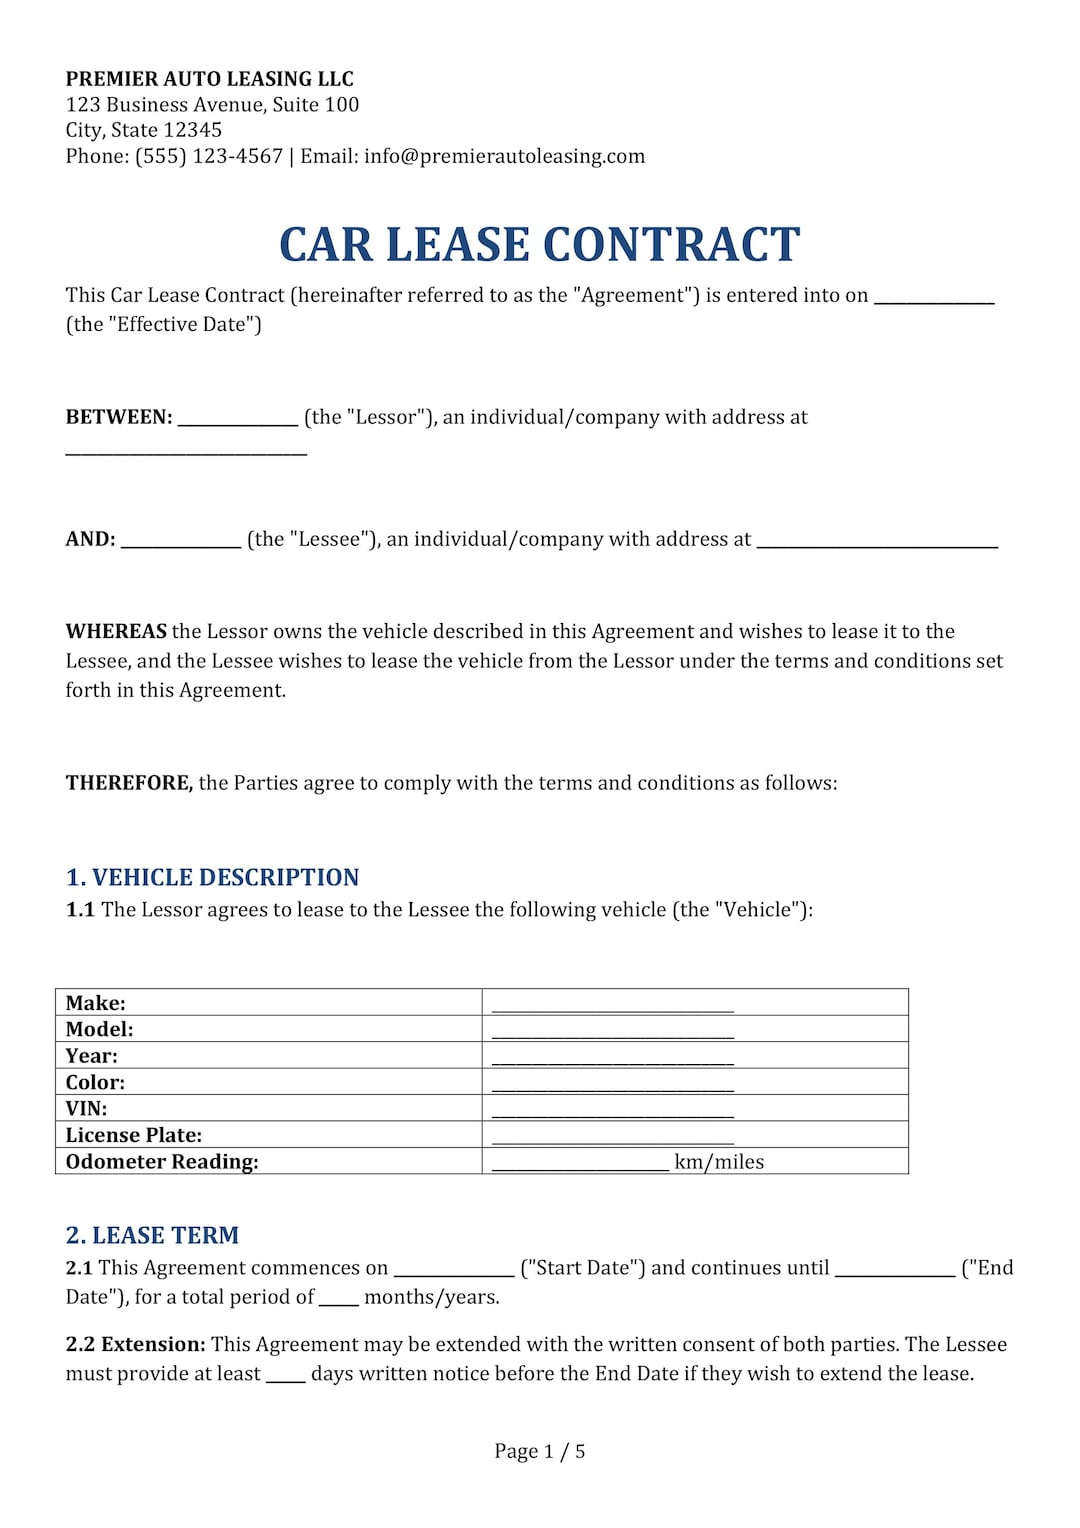
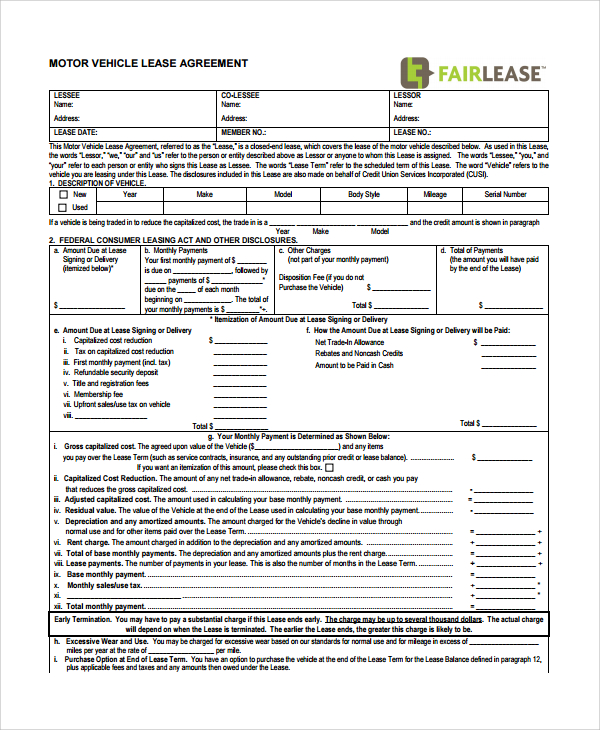
What an Automobile Lease Agreement Actually Is
An Automobile Lease Agreement is a legal contract where one party agrees to let another use a vehicle for a set period in exchange for regular payments. You don't own the car. The leasing company retains the title. When the term ends, you return it — or buy it if the contract allows that. Most people treat it like a rental and miss the fact that these documents carry real financial obligations that go well beyond monthly payments. The structure is straightforward on paper. You, the lessee, get to drive a vehicle. The lessor owns it. You make payments, follow the terms, and hand it back at the end. But the devil is in the fine print, and most lease agreements are written by lawyers who have never had to explain them to a confused customer. I've read enough of these to know which clauses actually matter and which are just noise designed to protect the lessor in worst-case scenarios.
Writing Your Own Automobile Lease Agreement
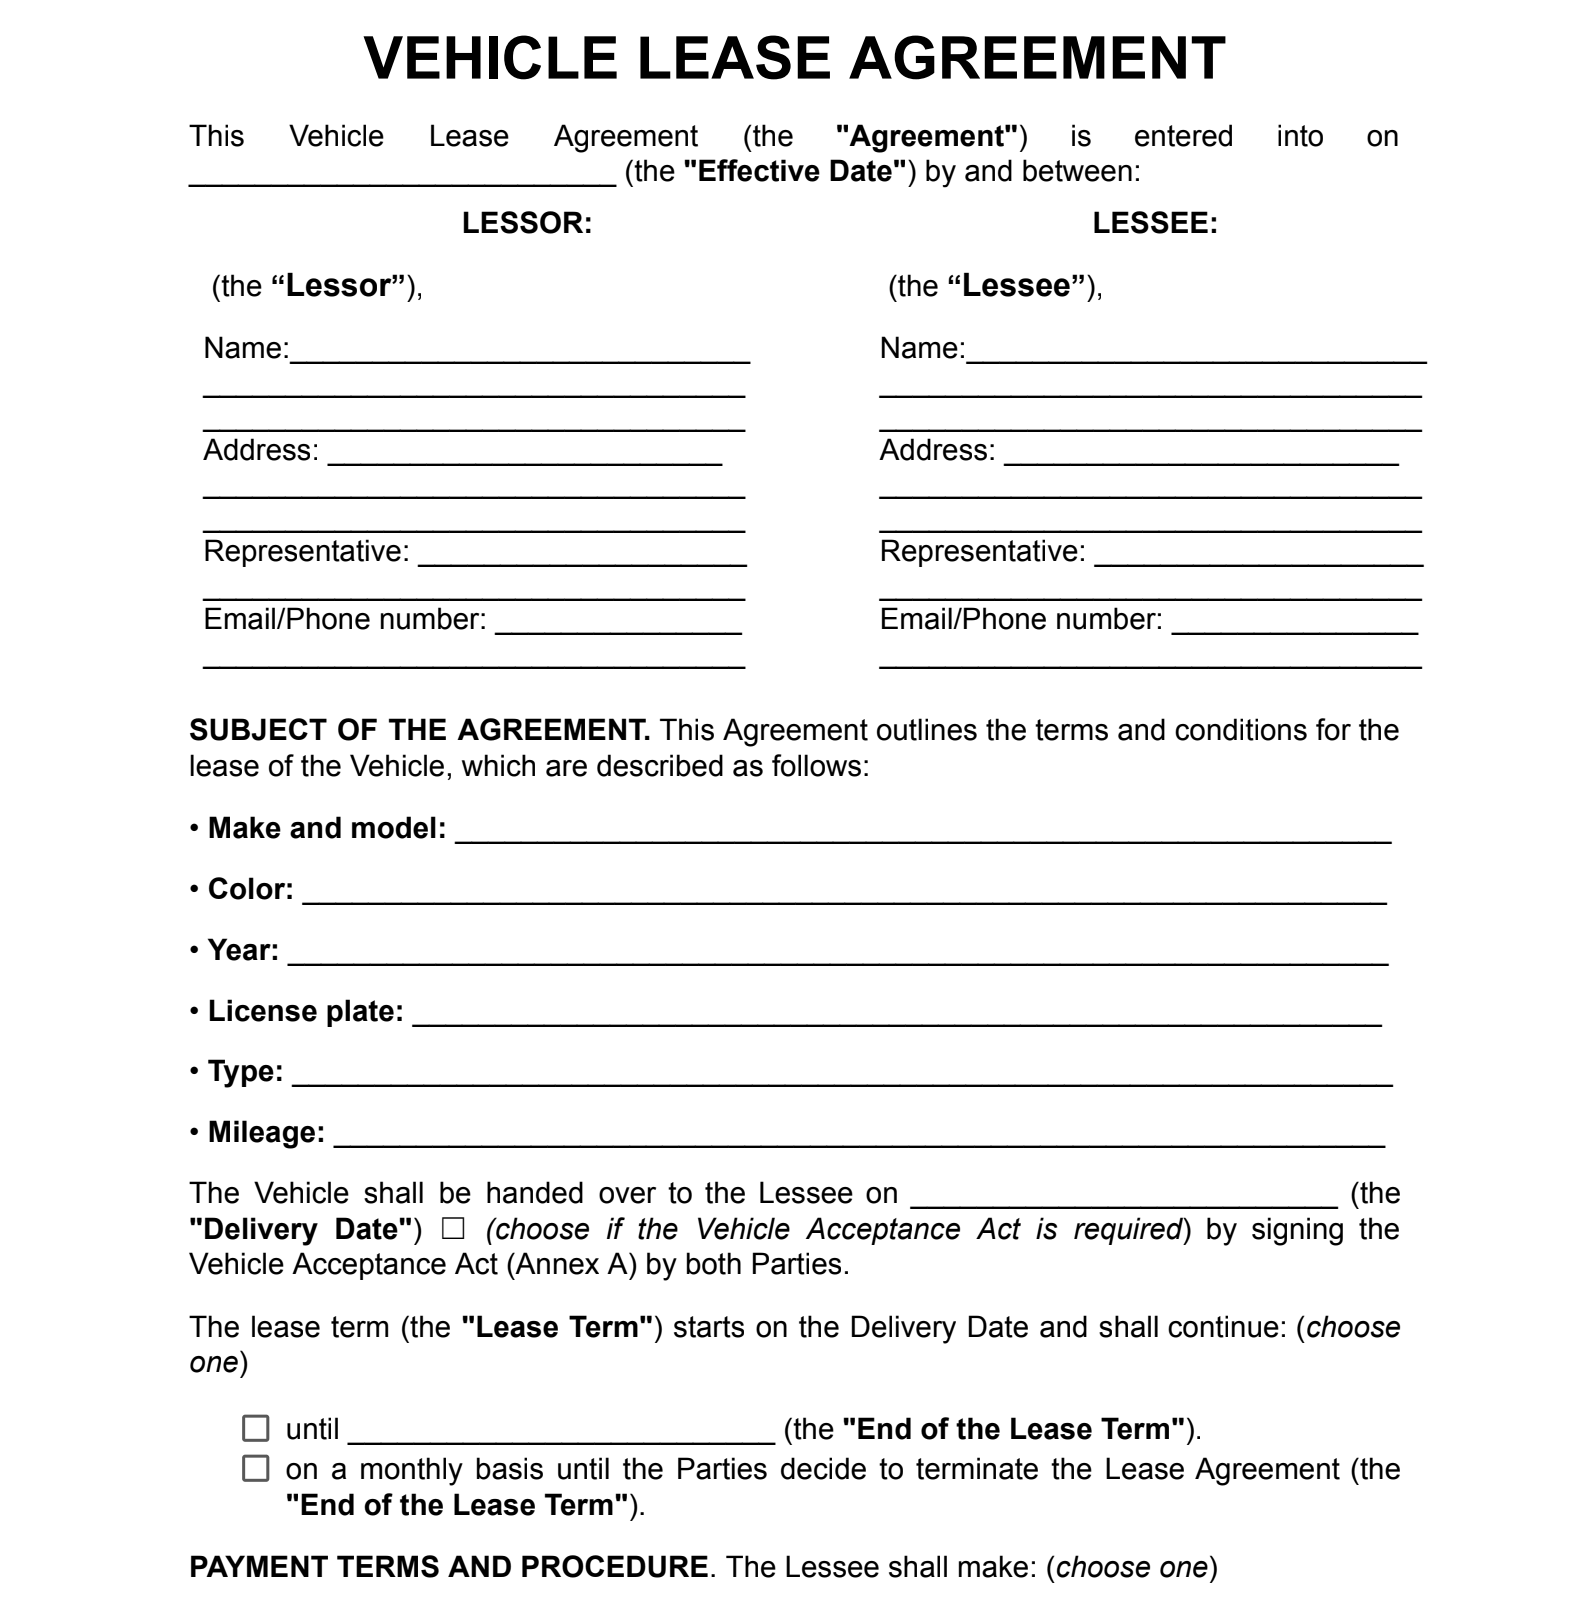
If you're drafting one from scratch instead of using a template, start with the core variables that every agreement needs. Vehicle identification, lease term, payment schedule, mileage allowance, maintenance responsibilities, insurance requirements, and the conditions for early termination or purchase at lease end. Get those right and the rest is mostly standard legal boilerplate. I've spent years reviewing and drafting these for both individuals and small dealerships. The biggest mistake I see is people copying templates they find online without understanding what each clause means. Last year a client of mine signed a lease agreement he'd downloaded from a free template site. It had a residual value clause that defined the purchase option price at the original MSRP rather than the actual depreciated value. He walked away paying nearly three thousand dollars more than he would have under a properly structured agreement. The contract looked fine. It wasn't. Here's what to actually focus on when you're putting one together:
Vehicle Description — Include the VIN, make, model, year, odometer reading at signing, and any existing damage documented with photos. I always recommend attaching a condition report as an exhibit to the agreement. It sounds like extra work but it prevents disputes about wear and tear at return time, which is where most lease disagreements happen. Mileage Restrictions — Standard leases run 10,000 to 15,000 miles per year. Excess mileage fees typically range from 15 to 25 cents per mile. If you're leasing for business use or personal driving that exceeds normal levels, negotiate the allowance up before signing. Changing it after the fact isn't possible. One of my clients exceeded his allowance by 4,200 miles and got hit with an $840 excess mileage charge. He could have saved all of it by asking for 18,000 annual miles instead of 15,000 — the difference in monthly payment was maybe twelve dollars. Maintenance and Repair Responsibilities — This is where agreements vary the most. Some leases require the lessee to perform all maintenance and keep records. Others allow standard dealer maintenance schedules. The key thing most people miss is that failure to maintain the vehicle per the manufacturer's schedule can be grounds for additional charges at lease end, even if the car seems to run fine. Get the maintenance terms in writing and follow them exactly.
Get the Full Details
Insurance Requirements — Most lessors require comprehensive and collision coverage with specific minimum limits. They may also require them to be named as an additional insured party. Don't skip this. If your coverage lapsed for any reason during the lease term, the lessor can declare a default and demand immediate return of the vehicle. Early Termination — This clause is often brutal. Early termination fees can equal several months' payments plus any remaining depreciation. I've seen fees of $3,000 to $5,000 on leases that were only a few months old. If there's any chance you might need out early, negotiate a buyout formula based on remaining payments minus a reasonable early termination discount, rather than accepting whatever the standard clause says. Purchase Option — Many leases include a conditional purchase option at the end, sometimes called a bargain purchase clause. If there is one, the price should be clearly stated and tied to the residual value. Without this clause, you have no right to buy the vehicle at lease end regardless of its condition or market value.
Common Pitfalls That Cost People Money
Lease-end fees are where most people lose money. The excess wear and tear charges are poorly defined in most agreements. "Normal wear and tear" means different things to different people. I've resolved disputes over tire tread depth, minor scratches on door handles, and stained upholstery by pointing back to the condition report filed at signing. If it wasn't documented, it didn't exist from the lessor's perspective at the start of the lease. Another trap: automatic lease renewal clauses. Some agreements state that if you continue using the vehicle after the term ends without signing a new agreement, the lease automatically converts to a month-to-month arrangement at the same payment rate. Those rates are often higher than what you originally agreed to. Always give written notice of your intent to return or renew at least 30 days before the end date. There's also the issue of tax treatment. Lease payments are generally not deductible as a business expense in the same way purchase costs might be, though business-use deductions do apply proportionally. Consult a tax professional if this is for business purposes. The rules changed enough in recent years that old advice about lease deductibility may no longer apply to your situation.
When a Template Isn't Enough
Free templates work for simple situations — a straightforward individual lease between friends or a one-off transaction. But if you're a dealer, a fleet manager, or doing this repeatedly, you need something more robust. A proper Automobile Lease Agreement should account for assignment clauses, sublease restrictions, default remedies, and dispute resolution procedures. Most free templates skip all of these because they're written for a single transaction between two parties who probably won't sue each other. The workaround I use is to maintain a master template library with different versions for different use cases. Individual consumer leases, commercial fleet leases, and lease-purchase agreements each have different clause structures. I started the process cold once and spent about 40 minutes getting it right. After that, customizing a template for a new situation takes maybe 15 minutes depending on how unusual the terms are. One technical detail that trips people up: the difference between a capital lease and an operating lease. A capital lease is treated as a purchase for accounting purposes. An operating lease is just a rental. The classification affects how the lease appears on financial statements and what tax treatment applies. If you're leasing through a business entity, get this right from the start. Getting it wrong can create accounting issues that take months to correct.
Significant Limitations You Should Know About
No lease agreement, however well drafted, can fully protect you from a lessor who decides to interpret the terms aggressively. The language might be favorable on paper but enforcement happens in collections departments and arbitration proceedings, not in courtrooms for the most part. Most agreements include mandatory arbitration clauses that limit your ability to pursue legal action. Lease agreements also create a power imbalance by design. The lessor writes the contract and they have legal counsel. The lessee usually doesn't. This isn't a conspiracy — it's just how these contracts work. You can level the playing field somewhat by negotiating specific terms before signing, but you can't negotiate the entire framework. The lessor will not change the fundamental structure of the agreement. If you find yourself in a situation where you need to terminate early due to financial hardship or a change in circumstances, the agreement likely has no provision for leniency. The terms are the terms. Your only real options are to sell the lease to another party (if assignment is allowed), buy out the remaining payments, or absorb the early termination penalty. There's no legal mechanism to force the lessor to be reasonable about it.
For most people, a well-structured standard lease from a reputable leasing company is the safest path. The terms are standardized, the risks are known, and there's precedent for how disputes get handled. Custom-drafted agreements carry more risk because there's no established interpretation of their unique clauses. If you do use a custom agreement, have it reviewed by someone who understands automotive leasing specifically, not just general contract law.