- Conventional fixed-rate mortgages: Most commonly 30 years, though 15 and 20 year terms are available
- FHA loans: Available in 15, 20, and 30 year terms
- VA loans: Typically 15 or 30 years
- Jumbo loans: Usually 30 years, but 15 year terms are also common
How Loan Length Affects Your Payments
The length of your loan term directly impacts two things: your monthly payment and the total interest you'll pay over the life of the loan.
With a 30-year mortgage, your monthly payment is lower because the principal is spread across more months. However, you'll pay significantly more in interest over the life of the loan. A borrower with a $300,000 mortgage at 6.5% interest would pay approximately $1,896 per month and around $382,000 in total interest over 30 years.
With a 15-year mortgage, your monthly payment is much higher—roughly $2,600 per month for the same loan—but you'll pay far less in interest. That same $300,000 loan at 6% would cost about $2,625 monthly and only $172,000 in total interest. You'd save over $200,000 in interest by choosing the shorter term.
Factors That Influence Your Choice
Your ideal loan length depends on several practical considerations:
Current income and stability: If you're early in your career or have variable income, a 30-year term keeps payments manageable. Higher earners often choose 15-year terms to build equity faster.
Interest rate environment: When rates are low, locking in a 30-year fixed rate can be smart, even if you plan to pay extra toward principal. You get the safety of lower required payments while still having flexibility.
Financial goals: If you want to be debt-free before retirement, a 15-year mortgage aligns better. If you plan to invest the difference between 15-year and 30-year payments, some people prefer the longer term.
The Math Behind Different Terms
Here's a comparison showing how average house loan length changes your finances:
| Loan Amount | 15-Year Term | 30-Year Term |
|-------------|--------------|--------------|
| $250,000 | ~$2,100/month | ~$1,498/month |
| $250,000 | Total Interest: ~$127,000 | Total Interest: ~$299,000 |
| $400,000 | ~$3,360/month | ~$2,396/month |
| $400,000 | Total Interest: ~$205,000 | Total Interest: ~$462,000 |
The numbers show why average house loan length matters so much. Over 30 years, you could pay nearly double in interest compared to 15 years on the same loan amount.
Common Misconceptions
Many borrowers assume they must commit to one term for the entire loan. Some lenders offer hybrid options or allow you to make extra payments toward principal without penalty. If you start with a 30-year mortgage but can afford higher payments later, you can still pay it off early.
Another misconception is that shorter terms are always better. While you save on interest, the higher monthly payment might strain your budget or prevent you from investing elsewhere. Sometimes the math favors the longer term with strategic extra payments.
When to Choose a Longer vs Shorter Term
Choose a 15-year mortgage if:
- You have a stable, high income
- You want to own your home outright sooner
- You can afford the higher monthly payment without hardship
- You're close to retirement and want to be debt-free
Choose a 30-year mortgage if:
- You need lower monthly payments to qualify
- You plan to sell the home within 7-10 years anyway
- You want flexibility to invest elsewhere
- Your income is variable or you're early in your career
The Bottom Line
The average house loan length in America is 30 years, but that doesn't mean it's the right choice for everyone. Your decision should balance current affordability with long-term goals. Run the numbers with your specific loan amount and interest rate, then choose the term that fits your financial reality—not just what sounds good on paper.
If you qualify for a 15-year term and can handle the payment comfortably, the interest savings are substantial. If not, a 30-year mortgage gives you breathing room, and you can always make extra principal payments when your finances allow.
Gallery Average House Loan Length
Trajectory of average household loan size | Download Scientific Diagram
Trajectory of average household loan size | Download Scientific Diagram
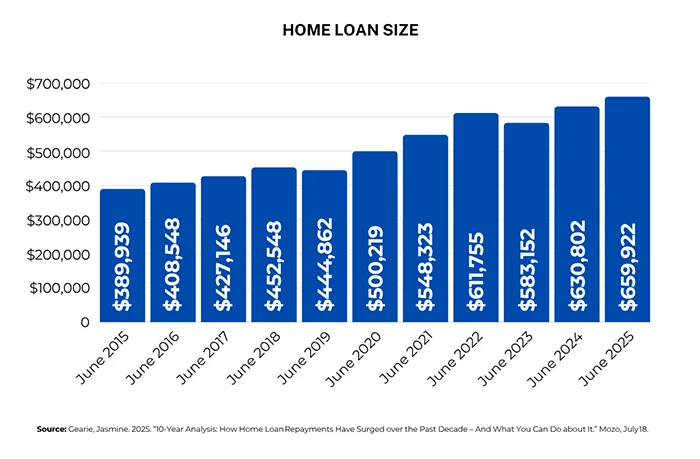
Resources: Average home loan up 69% – but so are the savings from switching | The Loan Company
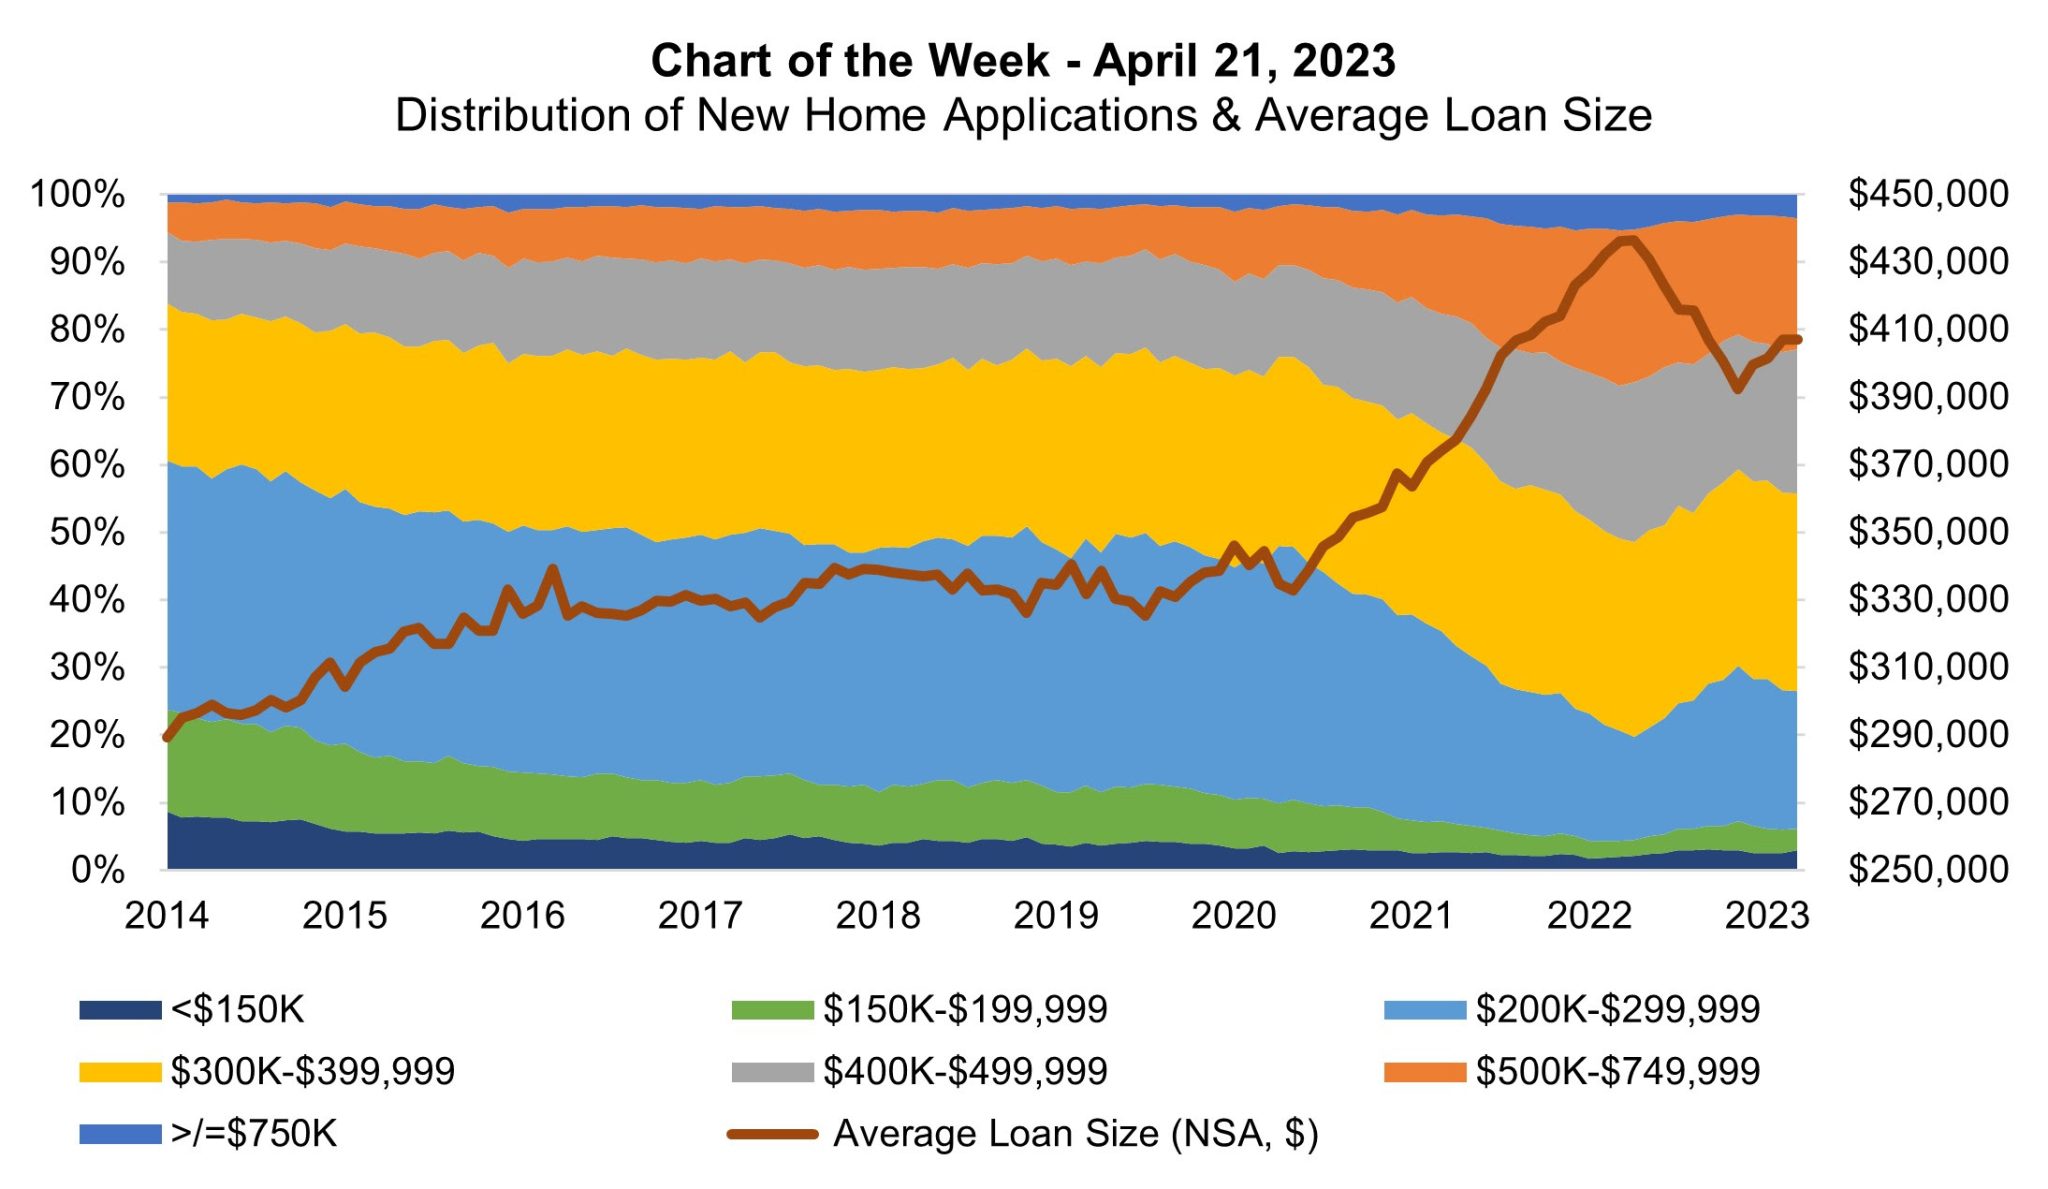
MBA Chart of the Week: Distribution of New Home Applications & Average Loan Size (Apr 21 2023 ...
MBA Chart of the Week Apr. 21, 2023-New Home Applications, Average Loan Size - MBA Newslink