Getting the Ba Ii Plus Business Analyst to Actually Work for You
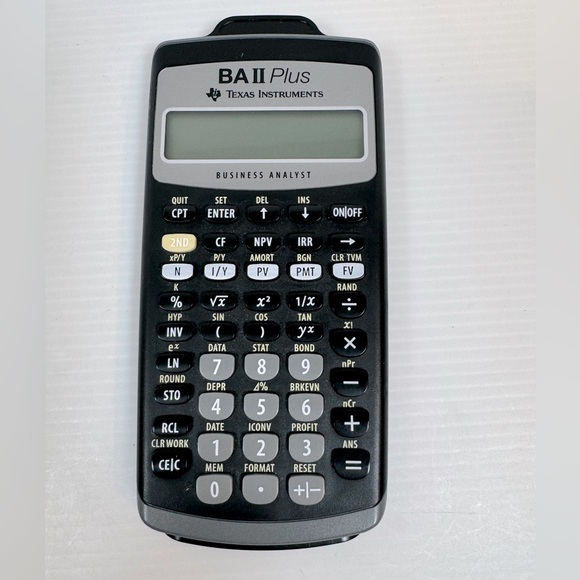
The BA II Plus is one of those calculators that shows up everywhere—CFA exams, corporate finance classes, actuarial tests. Texas Instruments makes it, and it's been the default handheld financial tool for decades. If you're sitting down to learn it, you'll find the learning curve steeper than it looks on paper. Not because the math is hard, but because the interface fights you until you understand what it's actually doing. I spent years building cash flow models and pricing debt in a way that made me realize most people never actually understand their calculator. They memorize keystrokes without grasping the underlying mechanics. That approach breaks the moment a problem doesn't match the textbook example. And it always does.
Learning the Ba Ii Plus Business Analyst the Right Way
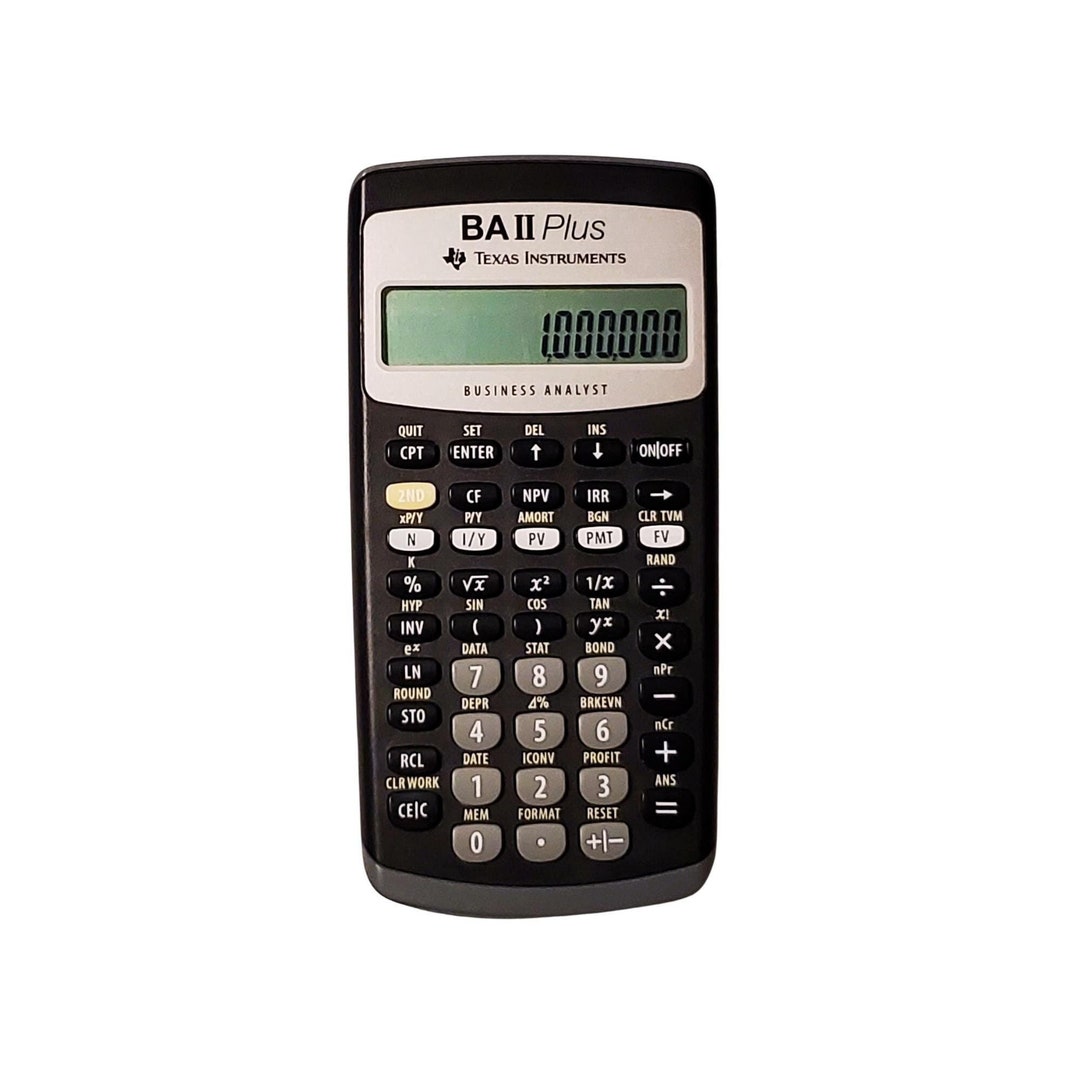
Start with the TVM keys. Time Value of Money. N, I/Y, PV, PMT, FV. These five buttons are the backbone of literally everything you'll use this calculator for. Most beginners just punch numbers into them blindly. Instead, learn what each variable represents and how they relate. If you can explain why changing N affects PV without looking at the manual, you're already ahead of 80 percent of people walking into an exam room with one. The second thing that matters is understanding calculator modes. The BA II Plus has two date formats, BGN and END for annuity timing, and you can set decimal places independently of display precision. I once spent twenty minutes trying to figure out why my bond price was off by nearly four hundred dollars before realizing the calculator was set to BGN mode instead of END. A single button press fixed it. This kind of thing happens to everyone. Just check your mode first. For cash flow work, the CF worksheet and NPV/IRR functions are where most people struggle. You enter cash flows using the CF key, then calculate NPV by specifying the discount rate separately. The IRR key does its own thing. A lot of users confuse the two and then wonder why their answers don't match the answer key.
Here's a practical workflow I use when building scenarios: clear the registers first with [2nd] [CLR TVM] or [2nd] [CLR WORK]. Then enter your data methodically. Don't trust memory. Don't assume the calculator remembered what you typed last week. It doesn't. Every fresh problem starts from scratch. When working with bonds, switch to the Bond worksheet. Press [2nd] [BOND]. You'll enter the settlement date, redemption value, coupon rate, yield to maturity, and frequency. The calculator gives you the price and dirty price. This part is genuinely useful once you know how to read the outputs correctly. The accrued interest portion trips a lot of people up because they forget to account for it when comparing to market quotes. Another area where the BA II Plus shines is statistical and regression work. Press [2nd] [DATA] to enter paired x and y values. From there you can get means, standard deviations, correlation coefficients, and even run linear regression. It's not pretty. The interface is clunky. But for quick analysis in an exam setting where you can't use a spreadsheet, it's functional. I used this extensively during my CFA Level I prep when practice questions asked for beta estimates from small datasets.
Get the Full Details
One counter-intuitive thing about this calculator that nobody emphasizes enough: the I/Y key stores the interest rate as a percentage, not a decimal. If your annual rate is 8 percent, you type 8, not 0.08. Typing 0.08 will give you a result that's off by a factor of one hundred. This mistake cost me a wrong answer on a practice exam and a very uncomfortable hour of recalculating everything by hand to verify. Here's another nuance that advanced users miss. The BA II Plus handles uneven cash flows natively through the CF worksheet, but it does not handle deferred annuities gracefully unless you adjust your approach. Say you have a annuity that starts three years from now instead of one. You can't just shift the N value. You have to calculate the present value at the start of the annuity and then discount that lump sum back to today as a separate step. I ran into this on a corporate finance project where we were valuing a lease with a rent-free period. The straightforward TVM approach gave a wildly wrong answer until someone pointed out the deferment issue. For depreciation calculations, the DDB and SLN functions are surprisingly capable. Double-declining balance and straight-line are both built in. You enter cost, salvage, life, and sometimes period. The SLN function is trivial. DDB requires you to understand that the declining balance method accelerates depreciation in early years, which matters for tax planning scenarios.
There are also some limitations worth knowing before you rely on this tool. The BA II Plus has a finite register system. If you run out of space in the CF worksheet, you can't go back and edit without clearing and re-entering. I've had this happen during timed exams and it costs real time. Keep your entries clean. Double-check before you move to the next cash flow. Another weakness is that the calculator does not store formulas. You cannot program it the way you might with a HP 12C or a programmable calculator. If you find yourself doing the same calculation repeatedly, you're stuck entering it every time. This isn't a dealbreaker for most users. But if you're doing heavy portfolio work with repeated metrics, it gets tedious fast. The display is also monochrome with limited resolution. Large numbers wrap awkwardly. Negative signs can be easy to miss. When you're crunching numbers under pressure, a misplaced negative sign on a PV entry flips your entire answer. I learned to always verify the sign convention makes sense before moving on. Positive PV with negative FV, or vice versa, depending on whether you're receiving or paying. Getting the direction wrong is the most common error I see.
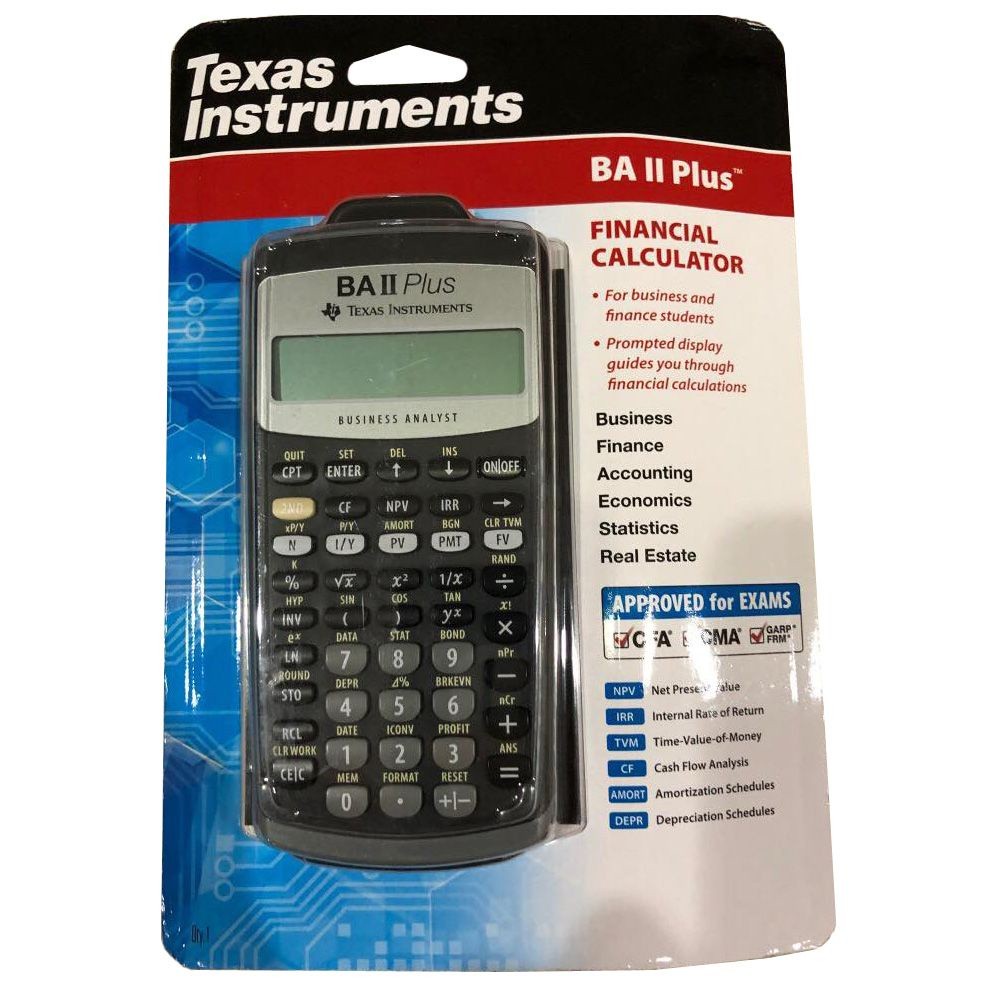
If you need something more powerful, the HP 12C remains the alternative that professionals tend to prefer. It has a RPN input system that many find faster once you get used to it. It's also programmable. But the BA II Plus is cheaper, more widely available, and accepted in most exam settings where the HP 12C is not. Know your constraints before choosing. For actual purchase, the TI BA II Plus Professional is the version most people want. It includes a built-in cash flow spreadsheet and some additional financial functions. Regular model stops short of that. Prices typically run between forty and seventy dollars depending on retailer and condition. Amazon, TI's direct store, and exam supply shops all carry it. Make sure you're buying an authentic unit. Counterfeit calculators sometimes have firmware issues that cause incorrect results on certain calculations. The biggest piece of advice I can give is to practice with actual problems, not just button mashing. Work through bond pricing, net present value calculations, annuity due versus ordinary annuity comparisons, and amortization schedules until the process feels automatic. The calculator itself is not the hard part. Understanding what the numbers mean is. That takes deliberate practice and a willingness to make mistakes while you're studying, not on exam day.