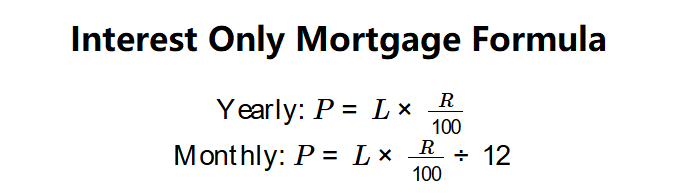
What an Interest Only Home Mortgage Calculator Actually Does
An interest only home mortgage calculator figures out what your monthly payment would be if you're only paying the interest portion of the loan for a set period. That's it. No principal reduction during the interest-only phase. You're basically paying rent on the money you borrowed. The calculation itself is straightforward: take the loan amount, multiply by the annual interest rate, divide by 12. Most calculators online do this instantly, but the ones that actually work properly also show you what happens when the interest-only period ends and the amortization kicks in. That second half is where people get blindsided. I've been working mortgage models for a long time, and the biggest issue I see isn't the math. It's that most people don't realize how dramatically their payment can jump after the interest-only window closes. You might be paying $1,200 a month on a $300,000 loan at 6.5% and feel fine. Then five years later, that same loan comes due for principal and interest and suddenly you're looking at $1,900 or more depending on the remaining term and rate. The calculator that tells you just the interest-only number is giving you an incomplete picture.
How to Use an Interest Only Home Mortgage Calculator Properly
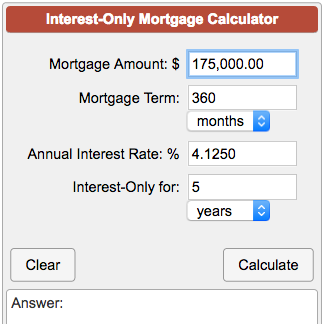
Start by entering the full loan amount, not just the portion you think you'll carry interest-only on. Some loans are partially interest-only, which complicates things. Plug in the actual annual rate your lender quoted — not the teaser rate from the brochure, the real rate with points and fees baked in if applicable. Set the interest-only period correctly, because some are 5 years, some are 10, and a few go as long as 15. Then run two scenarios: one showing the interest-only payment, and one showing the post-interest-only payment with full amortization over the remaining loan term. The trick most free calculators miss is the balloon payment risk. If you have a 30-year mortgage but only 7 years of interest-only payments, the remaining balance gets amortized over 23 years once the interest-only period expires. But some structures reset differently, and that changes everything. I dealt with a client who had a hybrid ARM that was interest-only for 7 years, then adjusted to a fully amortizing schedule over the original 30-year term minus the 7 already passed. Her payment jumped from about $1,450 to $2,180. Not catastrophic, but it caught her off guard because the calculator she used had only shown the initial payment. If you're trying to understand your actual numbers, the most useful calculator will let you adjust the amortization period that kicks in after the interest-only phase. Some lenders use the original term. Some reset it. This matters enormously for cash flow planning.
Why People Choose Interest-Only Mortgages and Where They Go Wrong
Interest-only loans aren't inherently bad. Investors use them strategically because they preserve capital during the build-out or lease-up phase. Homeowners who expect a significant paydown from a bonus or sale also find them useful. The problem is when someone picks an interest-only mortgage thinking it's a long-term strategy. It isn't. It's a short-term tool, and treating it like a permanent payment structure is how people lose homes. One thing people consistently overlook is the tax implication difference. During the interest-only period, your mortgage interest deduction is maximized because nearly every payment goes toward interest. Once principal amortization begins, a larger chunk of each payment goes to principal, which reduces your deductible interest. If you're relying on that deduction to make the numbers work, the post-interest-only payment combined with a smaller deduction can hit your net cash flow harder than the gross payment increase suggests. Another common trap is ignoring prepayment options. Some interest-only loans allow you to pay down principal during the interest-only period. A few even require minimum principal payments after year three or five. If your calculator doesn't account for optional or mandatory principal reductions, your end-of-period balance could be lower than expected, which softens the payment shock. Or worse, if mandatory reductions exist and your calculator ignores them, you're understating what you'll actually owe monthly going forward.
Get the Full Details
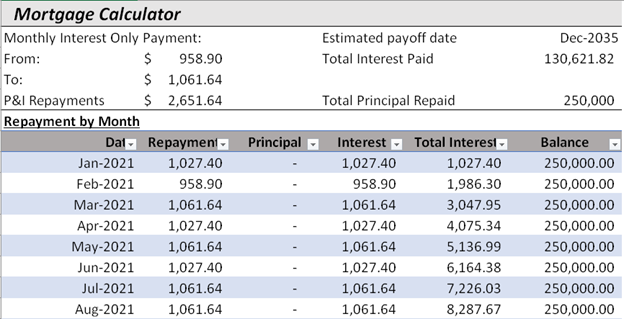
Pitfalls in Popular Online Calculators
I've tested dozens of free calculators, and the most widespread issue is that they assume the full loan amount is interest-only when it's actually a combination of interest-only and principal-plus-interest tranches. You'd be surprised how many people enter $300,000 into a calculator and get a result, not realizing their loan is structured as $200,000 interest-only and $100,000 amortizing from day one. The correct approach is to run separate calculations for each tranche and add them together. A second issue involves rate locks and adjustments. If you have an adjustable-rate mortgage with an interest-only period, the calculator needs to know whether the rate shown is the initial teaser rate or the fully indexed rate. Using the teaser rate gives you a payment that's significantly lower than what you'll actually pay once adjustments begin, even during the interest-only window. I've seen people budget on a 4.5% teaser rate when their note actually adjusts to 6.75% after year one. That's not a calculator problem, but most calculators don't warn you about it. The most annoying limitation I've encountered is that very few interest-only calculators factor in escrow. Your actual monthly obligation includes property taxes and insurance, which can add $300 to $800 to your payment depending on location. A calculator showing a $1,500 interest-only payment might actually cost you $2,200 out of pocket. If you're evaluating whether you can afford the loan, include escrow in your comparison or you're working with incomplete data.
Building Your Own Interest Only Home Mortgage Calculator
If the existing tools aren't giving you what you need, building a simple spreadsheet takes about 20 minutes and gives you far more control. You'll need cells for the loan amount, annual interest rate, interest-only period in months, total loan term, and whether the post-interest-only amortization uses the original remaining term or resets. The formula for the interest-only payment is simply the loan amount times the monthly rate. For the post-interest-only payment, use the standard PMT function with the remaining balance and adjusted term. Add a third scenario showing what happens if you refinance at the current market rate after the interest-only period ends — that's often the realistic path people actually take, and it changes the numbers significantly compared to staying with the original loan. One edge case worth noting: if your interest-only loan has an early payoff penalty, running the refinance scenario without including that penalty will overstate your savings. I worked with someone who calculated a $400 monthly improvement from refinancing and didn't discover until closing that the prepayment penalty was $8,200. That erased roughly 20 months of the projected savings. Always check the loan documents for any yield maintenance or prepayment clauses before modeling exit strategies. There's also the question of negative amortization. Some interest-only products, particularly certain ARM structures, allow the minimum payment to fall short of the accruing interest, which gets added to the principal balance. A basic calculator won't show this unless it's specifically designed for negative amortization loans. If your payment doesn't cover all the interest that month, your balance grows even though you're making payments on time. This is rare in residential mortgages now but still exists in some portfolio products and non-QM loans. Make sure whatever calculator you're using accounts for this possibility, or you could be looking at a higher balance than expected when the interest-only period ends.