Looking at a Balance Sheet Is Not the Same as Understanding It
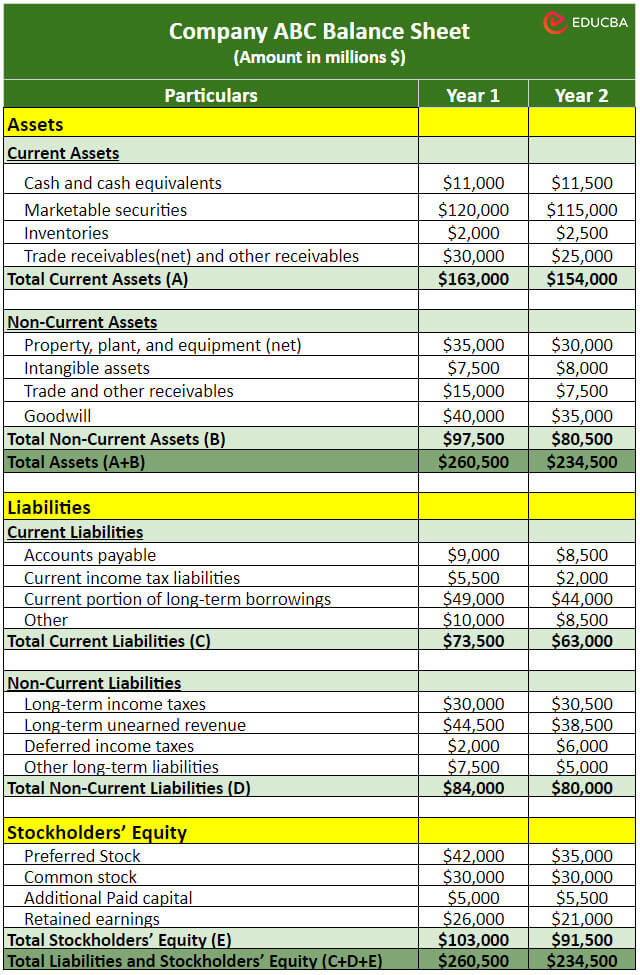
Most people open a balance sheet and start reading line items like a grocery list. That never works. The numbers on the page are a snapshot, but the story lives in the changes between snapshots and the relationships across lines. Here is a practical way to actually get something out of this. Let me show you how I would walk through a real example. Take a fictional manufacturing company with $42 million in total assets. You need to know if that's healthy, overstated, or sitting there collecting dust. The first thing I do is calculate working capital. Current assets minus current liabilities gives you an operating liquidity number. If it's negative and the business isn't a cash converter like a grocery chain, you've already flagged something worth investigating further. Next I pull total debt divided by total equity. A ratio above 2.0 in most industries means the company is carrying heavy leverage and a single revenue dip could trigger covenant issues. Below 0.5 usually means they're underutilizing cheap capital. The sweet spot sits somewhere in the middle, but it depends entirely on sector norms. Utilities run at 1.8 or higher without issue. Tech startups with minimal debt face different expectations.
Now look at asset turnover. Revenue divided by average total assets tells you how efficiently the company deploys its resource base. A dropping turnover over three years while revenue grows suggests the expansion is capital hungry and potentially inefficient. That distinction matters because growth looks good on an income statement until the balance sheet reveals where the money actually went. I also check receivables aging against revenue growth. When receivables grow 30 percent faster than sales, management either relaxed credit terms to push volume or collections are slipping. Either way it's a red flag for cash flow quality. Profitable companies with poor cash conversion cycle mechanics routinely fail. Revenue without collection is just a promise.
The Actual Process I Use
Start with three years of raw balance sheet data in front of you. Year-over-year change calculations take maybe ten minutes if your spreadsheet is set up correctly. I build a simple template that auto-formats percentage changes and common-size percentages in one go. Common-size means every line item expressed as a percentage of total assets. That lets you compare a $500 million firm against a $5 billion firm without distortion from sheer scale. Once the template runs, you scan for anomalies. A line item moving more than 15 percent year-over-year without a clear narrative reason deserves a note. Intangible assets jumping suddenly usually signals an acquisition that will need future amortization or potential impairment charges. Goodwill specifically warrants attention because companies occasionally use it to hide overpayment from prior deals. Cash and equivalents should never be dismissed as unimportant. A company sitting on $80 million in cash while carrying $120 million in high-interest debt is mismanaging its capital structure. That gap alone could save millions in interest expense if managed properly. The reverse scenario, where a growing company has minimal cash reserves relative to short-term obligations, tells a different and equally important story about refinancing risk.
Get the Full Details

Tangible book value per share is another metric people overlook. Total assets minus intangibles and goodwill, divided by shares outstanding, gives you a floor value that ignores accounting adjustments. During distressed situations or takeover scenarios, this number often predicts where a stock stabilizes more accurately than forward earnings estimates ever will.
A Real Problem I Hit
Several years back I was reviewing a mid-market industrial company and everything looked fine on the surface. Strong revenue growth, manageable debt ratios, positive working capital. Then I noticed their accounts payable had grown by 40 percent while inventory barely moved. The company was essentially financing its operations through supplier payment delays rather than genuine operational improvement. It looked like a positive cash flow story until you traced the supplier relationships and found that several key vendors had started requiring faster payment terms, which meant the apparent cash generation was about to evaporate quickly. The workaround was straightforward but required digging into footnotes. I pulled the vendor concentration data and payment term disclosures. The company had been extending payables from net-45 to net-60 over eighteen months through informal negotiation rather than formal contract changes. Once those informal arrangements expired, cash flow deteriorated materially. This is the kind of detail that never shows up in standard financial ratio screening tools. You have to read the notes section carefully and cross-reference operating metrics with balance sheet movements.
What Most People Get Wrong
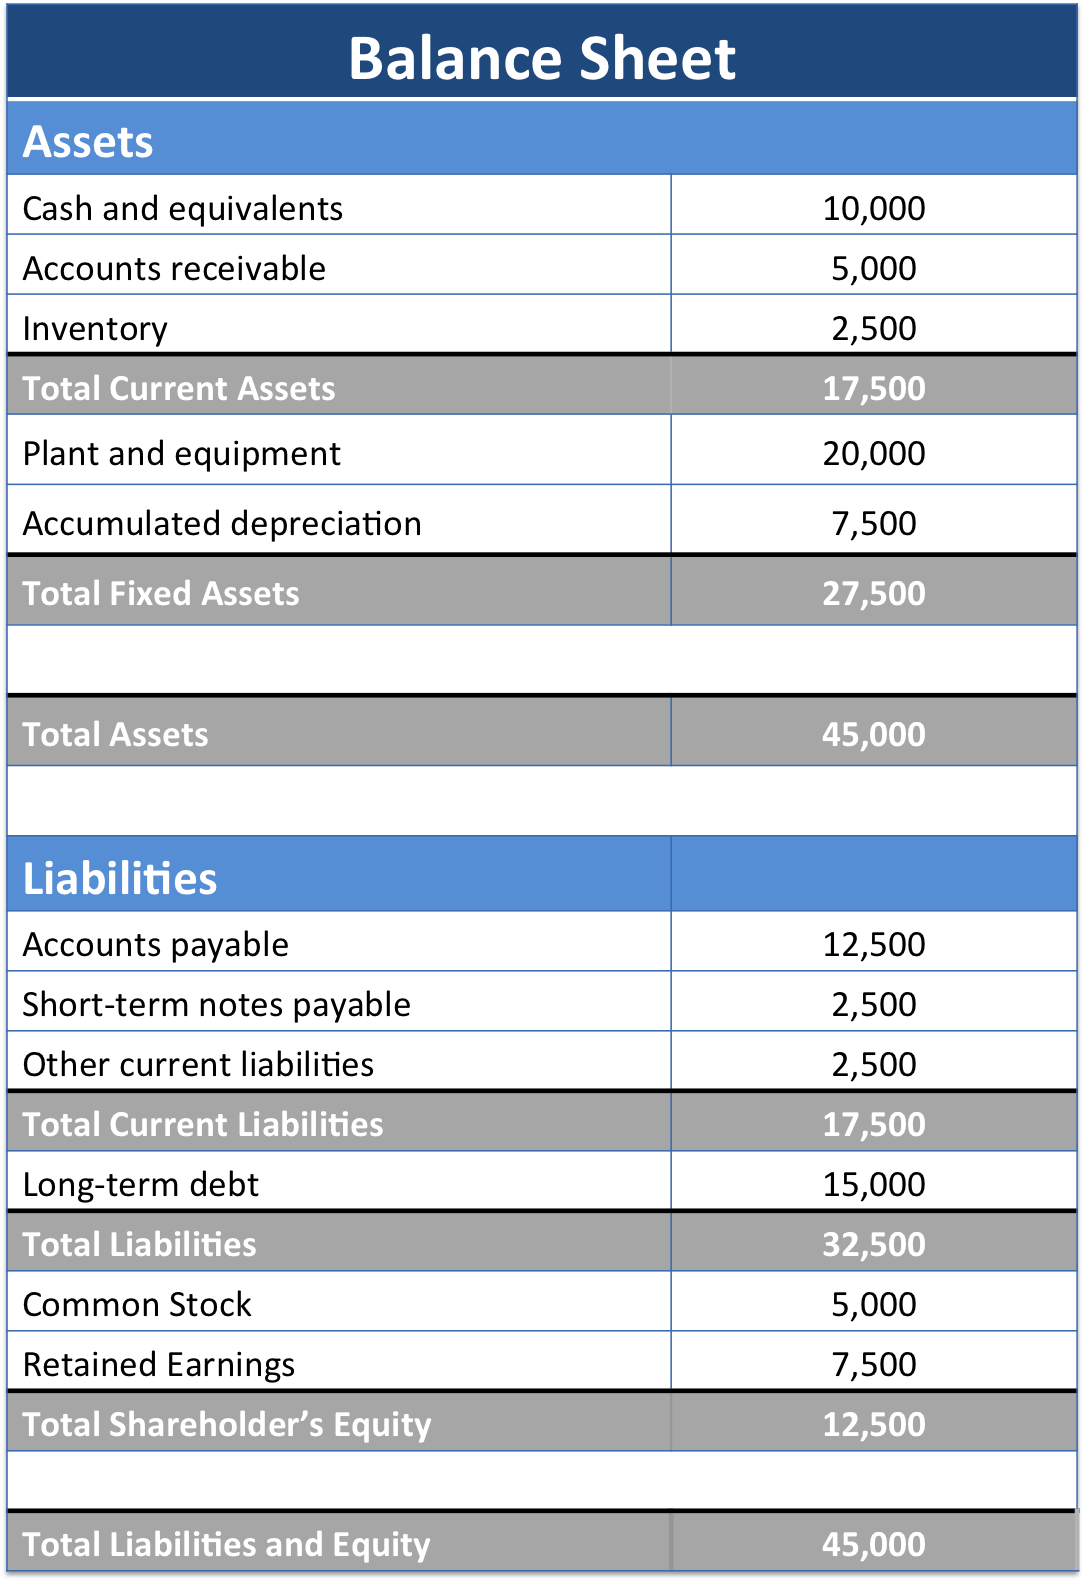
The biggest mistake I see is focusing exclusively on absolute dollar amounts instead of ratios and trends. A company with $2 billion in debt looks scary until you see it operates on $15 billion in assets with a debt service coverage ratio of 4.2 times. Meanwhile a smaller firm with $200 million in debt and a coverage ratio of 1.1 is the one actually at risk. Absolute numbers are meaningless without the denominator context. Another common error is treating balance sheet items as static. Inventory values shift with valuation methods. LIFO companies in the United States will report different inventory figures than FIFO users even when holding identical physical stock. Comparing these firms side by side without adjusting for the method difference produces false conclusions about relative profitability and liquidity positions. People also ignore off-balance-sheet obligations. Operating leases used to be the classic example before the accounting standards changed, but certain contractual commitments and contingent liabilities still don't appear directly on the balance sheet. Pension obligations, environmental remediation reserves, and litigation provisions can create material risks that ratio analysis completely misses unless you dig into the footnote disclosures.
When This Approach Falls Short
Balance sheet analysis alone cannot determine whether a company is a good investment. It tells you about financial position and risk characteristics. It does not predict future earnings, competitive positioning, or management quality. A company with a pristine balance sheet can still destroy shareholder value through poor strategic decisions or industry disruption. For service-based companies with minimal physical assets, the traditional balance sheet framework becomes even less useful. Human capital, intellectual property, and customer relationships drive value but rarely appear as measurable assets on the sheet. In those cases, you need to supplement balance sheet analysis with cash flow statement review and qualitative factors that no spreadsheet can capture. Banking and insurance companies require entirely different analytical approaches because their balance sheets function differently. Deposits are liabilities but represent available lending capital. Policy reserves operate under regulatory frameworks that distort normal balance sheet interpretation. Using standard industrial analysis techniques on financial institutions produces misleading conclusions about leverage and liquidity positions.
Quick Reference for Key Ratios
Current ratio above 1.5 generally indicates comfortable short-term liquidity for non-financial companies. Below 1.0 suggests potential cash flow pressure unless the business model generates cash rapidly despite the ratio. Quick ratio removes inventory from the calculation and provides a stricter liquidity measure, especially useful for retailers where inventory may be slow-moving or obsolete. Debt-to-equity ratio below 1.0 means equity holders fund more than half the asset base. Above 2.0 typically signals aggressive leverage unless the industry carries inherently high fixed costs. Interest coverage ratio below 2.0 raises concerns about debt servicing ability during revenue downturns. Above 5.0 generally provides adequate cushion for most stable businesses. Return on assets measures how effectively management deploys the entire asset base regardless of funding structure. Values above 8 percent for manufacturing and above 5 percent for retail are reasonable benchmarks, though sector variations exist. Declining ROA trends warrant investigation even when current levels appear adequate.
Where to Find the Data
PUBLIC companies file balance sheets through SEC Edgar or equivalent regulatory bodies in other jurisdictions. Annual reports contain the full balance sheet along with notes that provide crucial context. Quarterly filings give you more recent snapshots but include fewer disclosure details. Subscription services like Bloomberg or Refinitiv aggregate this data and can export directly to spreadsheet format, saving considerable manual entry time if you are analyzing multiple companies regularly. PRIVATE companies do not make their financials publicly available. If you are evaluating a potential acquisition or credit extension, access depends on the relationship and due diligence agreements in place. This limitation makes balance sheet analysis impossible without cooperation from the company itself, which changes the entire dynamic of the evaluation process.