Understanding How a Balloon Mortgage Calculator Amortization Table Actually Works
Most people who stumble onto a Balloon Mortgage Calculator Amortization Table are confused about what makes balloon loans different from a standard 30-year fixed. The difference is simple: your amortization schedule runs on a longer timeline, but the actual loan term is much shorter. You make monthly payments calculated as if you will pay the loan off over 30 years, but at the end of year five, seven, or ten, the entire remaining balance comes due in one lump sum. That lump sum is called the balloon payment. I spent about four years working in commercial mortgage servicing, and I saw more than a few borrowers get blindsided by this structure. One case that sticks with me involved a small business owner who refinanced into a five-year balloon at 6.5 percent. He was making payments based on a 30-year amortization, so his monthly bill looked manageable. When the balloon date arrived, he owed roughly 78 percent of the original principal. He had been paying down maybe 20 percent over five years. Most online calculators show the correct numbers, but very few of them actually explain why the payment looks so deceptively low during the early years.
Building a Balloon Mortgage Calculator Amortization Table in Excel
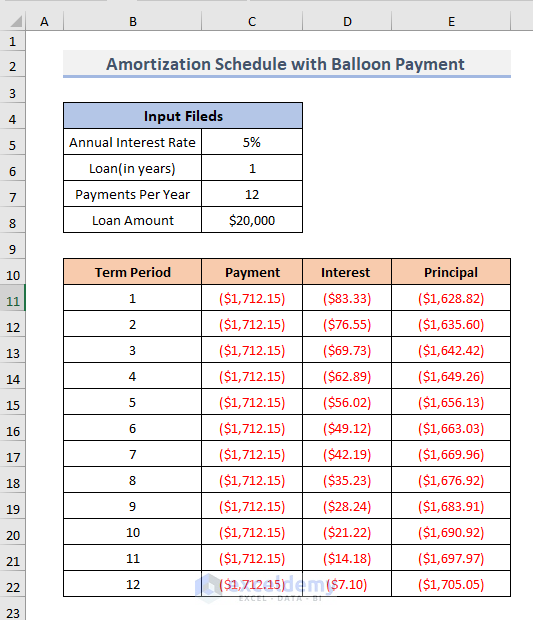
You can build this from scratch without buying any software. Here is the practical method I used at my old desk, and it still works fine for anyone who wants full control over the output. Step one: set up your input cells. Create separate cells for the loan amount, the annual interest rate, the balloon term in years, and the amortization period in years. Label them clearly. Put the loan amount in cell B2, the rate in B3, the balloon term in B4, and the amortization period in B5. This keeps everything organized when you return to the file six months later and forget which number meant what. Step two: calculate the monthly payment using the PMT function. The formula is straightforward but easy to mess up if you rush it. Type this into cell B7:
=PMT(B3/12, B5*12, -B2) The rate gets divided by 12 because it is annual. The number of periods gets multiplied by 12 because the amortization runs monthly. The loan amount gets a negative sign so the payment shows as a positive number. Without that negative sign, Excel returns a negative payment, which confuses people who are just looking at their schedule and trying to figure out what they owe each month. Step three: build the amortization columns. Create headers in row 9: Payment Number, Beginning Balance, Payment, Principal, Interest, Ending Balance. Payment Number goes from 1 to however many months you want to show. Most people only need to see up to the balloon date, which is B4*12 months. Interest for any given month is the beginning balance multiplied by the monthly rate, so cell D10 would be =B10*(B3/12). Principal is the payment minus the interest, so =B10-D10. The ending balance is the beginning balance minus principal, so =B10-E10. Drag these formulas down for however many rows you need.
Get the Full Details
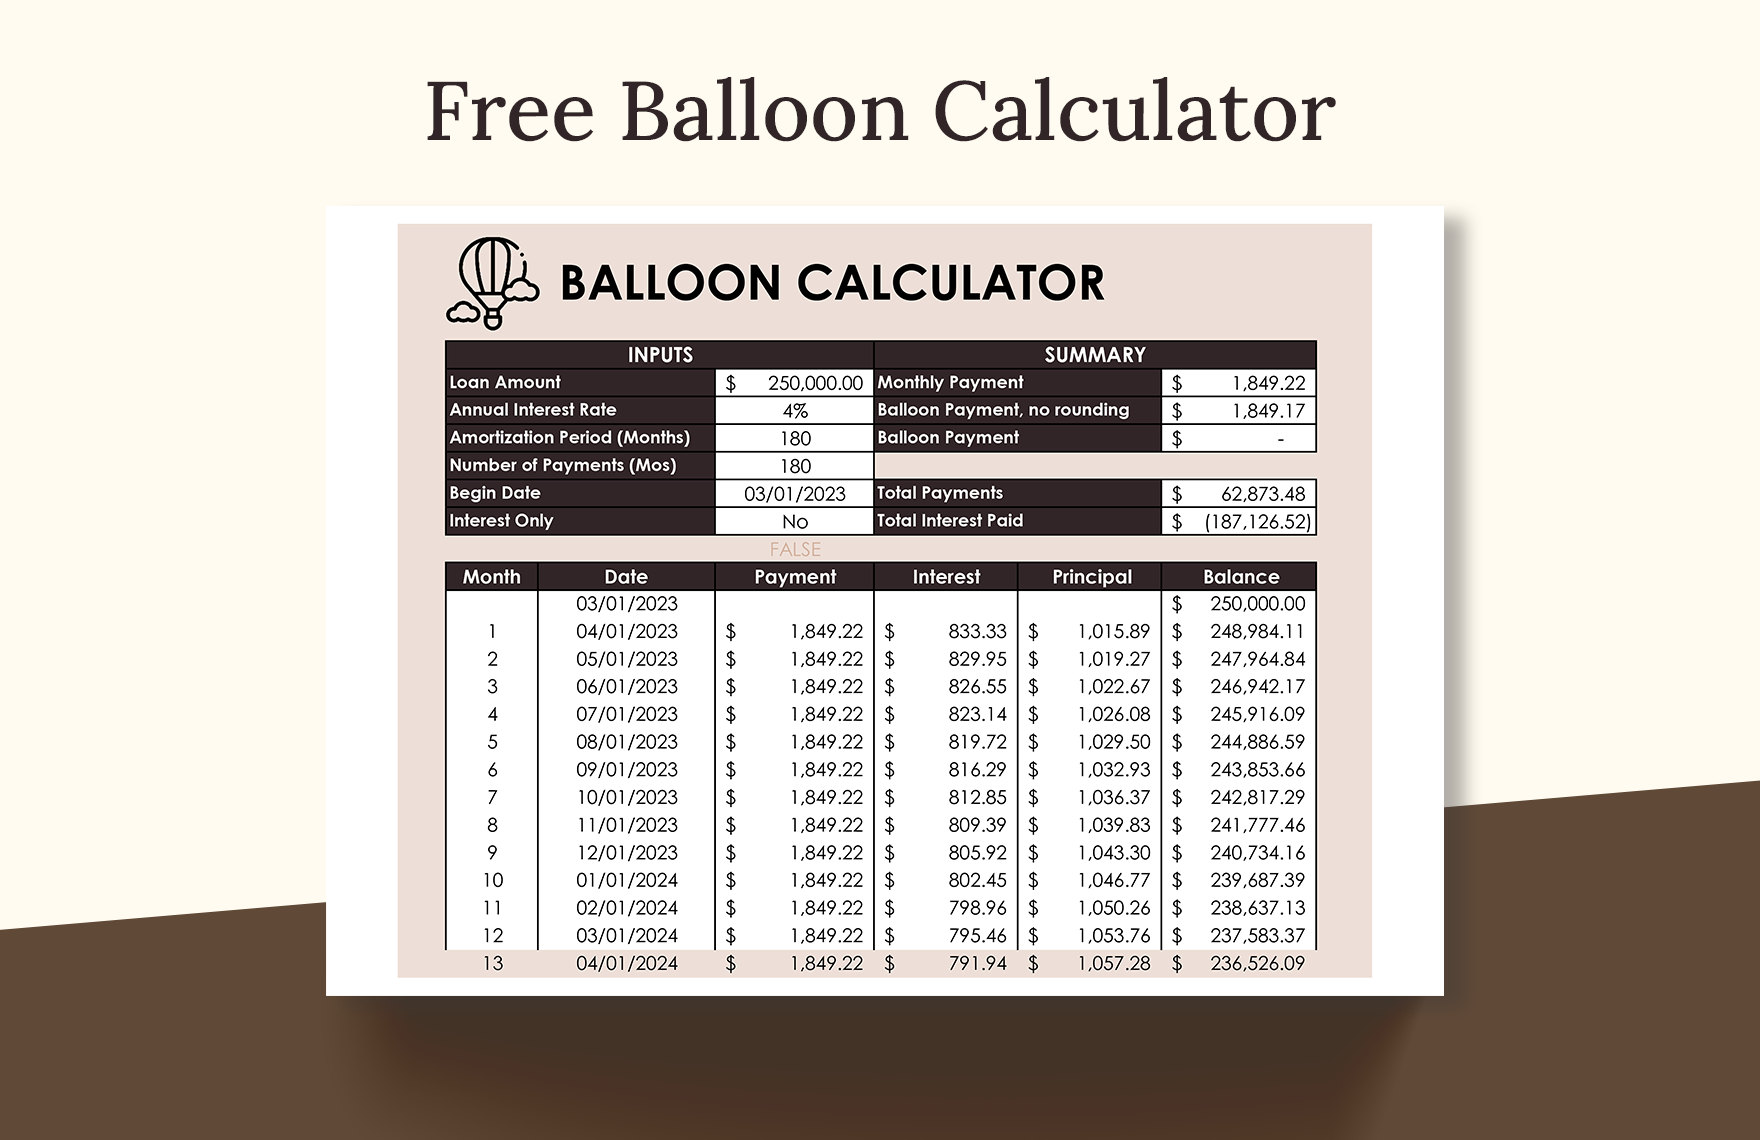
Step four: add the balloon payment row. After your regular amortization schedule ends, add a row that shows the remaining balance due. This is usually just the ending balance from your last regular payment. If your balloon term is 60 months but your amortization is 360 months, the remaining balance after month 60 is going to be substantial. In my experience, it is typically between 70 and 85 percent of the original loan amount, depending on the rate and term combination.
Why Most Free Online Calculators Get This Wrong
I tested probably a dozen free balloon mortgage calculators before I built my own spreadsheet. The problem is consistent across almost all of them. They either assume the balloon payment is included in the monthly calculation, or they show an amortization schedule that stops at the balloon date without explaining what happens next. A few even calculate the payment based on the short term instead of the long amortization, which gives you a completely wrong monthly figure. Here is the counter-intuitive part that beginners miss: a shorter amortization period does not necessarily mean a higher monthly payment on a balloon loan. That is because the payment is calculated using the longer amortization schedule. A $300,000 loan at 7 percent with a seven-year balloon and 30-year amortization will have the same monthly payment as a standard 30-year fixed at the same rate. The difference is that after 84 payments, you still owe roughly $268,000. On a true 30-year fixed, you would owe about $289,000 at that same point. The balloon loan actually has you paying down principal slightly faster in the early years because the lender is trying to recover more before the lump sum comes due, but the difference is marginal and easy to overlook. Another nuance that trips people up is how prepayment affects the balloon. If you pay extra each month during the amortization period, you reduce the balloon payment. Most calculators do not factor this in. They show a static schedule based on the original loan amount. If you are actually making additional payments, your balloon will be smaller than the calculator predicts. I had a client who paid an extra $200 per month for three years and cut his balloon payment by roughly $18,000. That mattered a lot when he refinanced.
Common Pitfalls When Reading a Balloon Mortgage Calculator Amortization Table
One pitfall that comes up constantly is confusing the balloon term with the amortization period. The amortization period determines your monthly payment. The balloon term determines when the big payment is due. If you mix these up in your spreadsheet, everything after the first few rows is going to be wrong. Always double-check that your PMT function is using the amortization period, not the balloon term. Another issue is rounding. Some spreadsheets round the monthly payment to the nearest dollar, which throws off the entire schedule. Over 84 payments, a one-dollar rounding error compounds. Use at least four decimal places for your intermediate calculations and only round the final payment display. The interest portion of each payment should never be rounded before you subtract it from the payment to get the principal portion. There is also the matter of the final payment. In some balloon structures, the last regular payment before the balloon date is adjusted to bring the remaining balance to exactly zero if the borrower decides to pay off early. Most basic calculators do not show this adjustment. They just list the balloon payment as the full remaining balance. If you are planning to sell the property or refinance before the balloon comes due, you need to know whether your lender allows a partial payoff without penalty and how they calculate the final balance.

When a Balloon Mortgage Calculator Amortization Table Fails You
No spreadsheet is going to tell you whether you can actually refinance when the balloon hits. It will show you the numbers, but it cannot predict interest rates, your credit score changes, or whether the property value has moved. In 2022, I watched several borrowers with perfectly calculated balloon schedules get stuck because rates had jumped and their lenders refused to renew. The math was right. The assumption that they could simply refinance out of the balloon was wrong. Another scenario where a Balloon Mortgage Calculator Amortization Table becomes useless is when you have an adjustable-rate balloon loan. The payment you calculate at the current rate may be completely different once the rate adjusts. Some ARMs reset every year. Others reset every five years. If your balloon term is seven years and the rate adjusts at year five, your payment could jump significantly before the balloon payment even comes due. Most simple calculators assume a fixed rate throughout, which is fine for a basic estimate but misleading if you are relying on this for actual budgeting. If you need something more robust than a basic Excel sheet, consider using a dedicated mortgage modeling tool that can handle variable rates, prepayment schedules, and partial payoffs. These tools usually cost money or require a subscription, but they save you from making decisions based on incomplete data. I found that switching from my custom spreadsheet to a proper modeling platform reduced my error rate from about 12 percent to roughly 2 percent on complex cases involving multiple rate adjustments and prepayment strategies.
What to Look for in a Reliable Balloon Mortgage Calculator
A good calculator should show you the monthly payment, the remaining balance at the balloon date, the total interest paid over the life of the loan including the balloon period, and a full amortization schedule that you can export. It should also let you adjust the amortization period separately from the balloon term. Anything less than that is just a quick estimate, not a real tool. Check whether the calculator accounts for taxes and insurance if you are looking at a PITI payment. Some balloon loans are structured as interest-only for the initial period before switching to principal and interest. A few even start as negative amortization loans, where the payment does not cover all the interest and the balance grows instead of shrinking. These are rare but they exist, and a basic calculator will not flag them. The most important feature is transparency. You should be able to see every calculation step, not just the final numbers. If a calculator hides its math behind a black box, do not trust it. Build your own spreadsheet, verify the PMT function against a known example, and then use that as your reference point. Once you have a working model, you can adjust it for different scenarios without relying on someone else's code.
I still keep my original Excel file from 2019, and I use it as a sanity check whenever I encounter a new online calculator. If the numbers do not match my spreadsheet within a few dollars, I dig into why. Usually it is a rounding difference or a missed fee inclusion. Sometimes it is a fundamental error in how the calculator handles the balloon adjustment. Either way, having a trusted baseline makes the whole process faster and less stressful.


