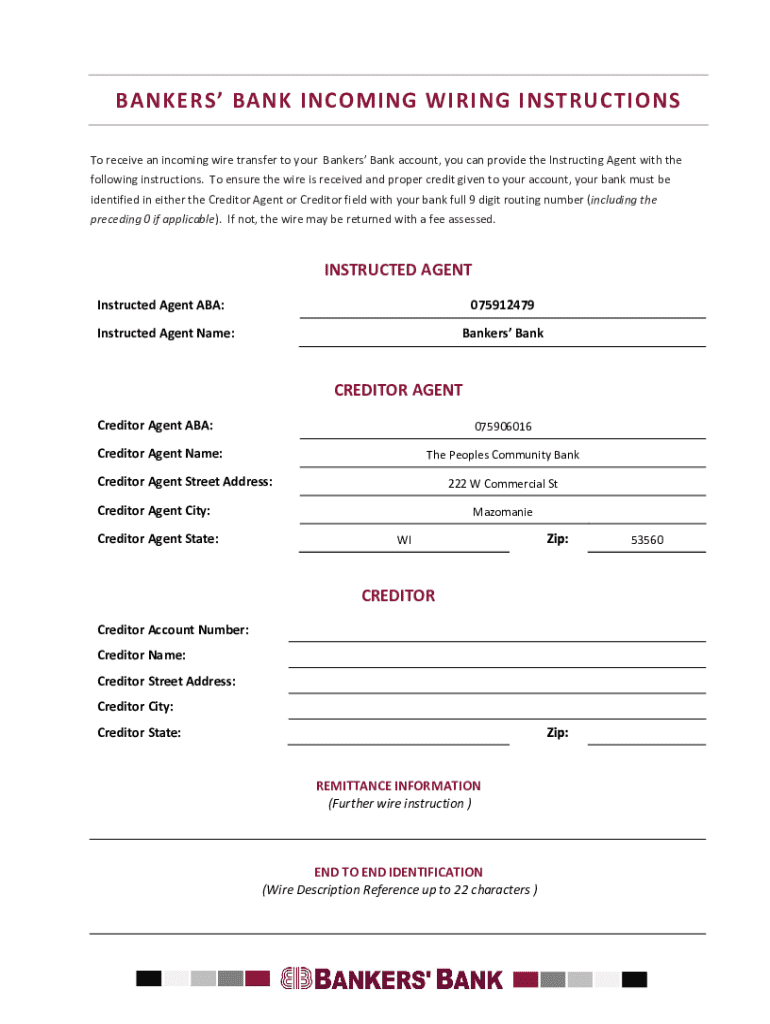
What Bank Incoming Wire Instructions Actually Are
They're a set of details you give to someone who needs to send money into your account from abroad or sometimes domestically. The person or company initiating the transfer needs your bank's routing number, your account number, the SWIFT/BIC code for your bank, and sometimes your address on file. That's it. Nothing more complicated than that, though the execution is where people get tripped up. I've been dealing with wire transfers for over a decade now, and the number one mistake I see is people sending their outgoing wire instructions instead of their incoming ones. They look the same on paper but they serve completely different purposes. The format looks nearly identical whether it's incoming or outgoing, which is annoying but true. If you've ever asked your bank for "wire instructions" and gotten back a document that works for outgoing but fails on the receiving end, this is exactly what happened to you.
How to Generate Your Bank Incoming Wire Instructions
Log into your online banking portal and navigate to the account details or transfer section. Most major banks have a dedicated "Wire Instructions" or "Direct Deposit Information" link on the account page. Some banks like Chase and Wells Fargo let you download a formal PDF directly. Others, like local credit unions or smaller regional banks, might require you to call a number and wait on hold for fifteen minutes. Bank of America used to put these behind two additional clicks that weren't obvious. Happened to me last month when I was helping a friend set up payroll for a remote contractor. Took three phone calls before I figured out the right menu path. The information you'll pull will include your full name as it appears on the account, your account number, your bank's ABA routing number for domestic wires, and the SWIFT code for international transfers. Some banks also require an intermediary bank's details for certain currencies. This is not optional for euro or pound conversions going through US banks. If you skip the intermediary, the money stalls or gets returned with a fee attached. Here's the practical part that nobody emphasizes enough. Always verify the SWIFT code against the exact branch your account is held at, not just your bank's headquarters. I had a situation where my client sent a €50,000 transfer using the parent bank's SWIFT code instead of the regional office code. The money sat in limbo for four business days while the receiving bank chased down which branch actually owned the account. Cost us a $45 trace fee and a seriously awkward conversation with the sender. You can verify SWIFT codes at swift.com for free. Takes thirty seconds and prevents hours of headaches.
Common Pitfalls That Waste Everyone's Time
The intermediary bank problem is the most common issue with international wires. Not every bank has direct correspondent relationships with banks in every country. When a wire crosses certain currency corridors, it needs to pass through an intermediary institution. Your bank will tell you which one to use, but sometimes the initiating bank chooses a different intermediary on their own. This creates a mismatch and the funds get delayed or rejected. Always ask your bank which intermediary they prefer for the specific currency you're receiving, then make sure the sender uses that exact institution. Beyond the usual SWIFT/Giro confusion. People mixing up the different system names. SWIFT handles most international wires. SEPA covers euro transfers within the single euro area. Fedwire runs domestic US dollars. CHAPS handles UK pounds. Each system has different cut-off times, different fee structures, and different error handling. If someone sends you a euro via SEPA and you give them SWIFT instructions anyway, the wire might still go through but it'll be routed the long way and cost more than necessary. Know which corridor your sender is using and match the instruction format accordingly. The address field trap. Many wire forms require your street address as it appears on your account. If you typed it differently when you opened the account five years ago, or if you moved and updated your email but not your mailing address, the intermediary bank might flag the discrepancy and hold the transfer for manual review. I learned this the hard way when a German contractor sent an SEPA transfer to a US account and it came back because the address on the wire didn't match what my bank had on file for the account holder. Updating the address in the portal resolved it, but the delay cost us a late payment penalty on a vendor invoice. Check your address before sharing your instructions, especially if it's been a while since your last update.
Get the Full Details
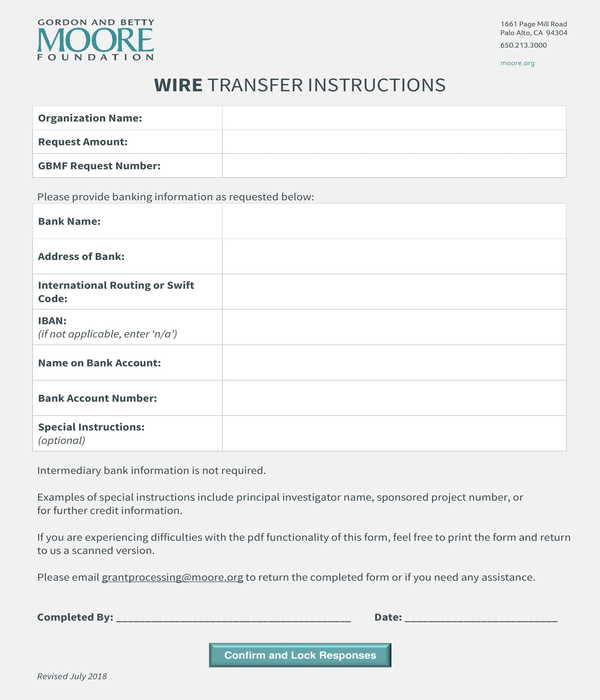
When Bank Incoming Wire Instructions Just Won't Work
There are legitimate scenarios where this approach breaks down. Small transfers under $500 often get eaten alive by fees on both ends. A $30 outgoing fee from the sender's bank and a $15 incoming fee from yours turn a $500 payment into a $455 receipt. For recurring small payments, setup a different method. Platforms like Wise or Payoneer handle micro-transfers far more efficiently, though they carry their own exchange rate markup. Worth comparing the total cost across options before committing to wires for anything under $1,000. Some banks also impose limits on incoming wire amounts per transaction or per day. Corporate accounts typically have higher thresholds than personal accounts. If you're expecting a large transfer, call your bank ahead of time and ask about any reporting requirements or holds. The Bank Secrecy Act kicks in at $10,000 for domestic wires, and international transfers trigger similar scrutiny. Your money isn't frozen, but the bank may request documentation proving the source. Having an invoice or contract reference ready speeds this up from weeks to minutes. One more thing worth noting about turnaround times. Even "same day" wires don't always land the same day. Cut-off times vary by bank and by currency. A wire sent at 4:30 PM EST on a Friday to a European bank effectively becomes a Monday submission. Weekends and holidays in either country count. Always factor in at least one full business day buffer unless you've specifically arranged expedited handling with your bank, and even then there are no guarantees. The industry standard for international wires remains two to five business days, and that's under ideal conditions.