Understanding and Using Bank of America Letter of Instruction
A Bank of America Letter Of Instruction is a formal document used to authorize a specific action on your behalf. It most commonly comes up when you need someone else to initiate a transaction, update account information, or handle paperwork without being the actual account holder. The bank accepts these letters when the person signing has proper legal authority — usually a power of attorney or court appointment. You need to include several specific elements for the bank to process it without sending it back. Full legal name of the account holder, complete account number, the precise action being authorized, full legal name and contact information of the authorized party, and a clear statement of scope. Limit the scope. A vague letter gets rejected faster than one that's too narrow, which sounds backwards but it's true. Bank officers are trained to flag ambiguity because ambiguity creates liability for them. I spent three weeks trying to get a wire transfer processed through an authorized representative last year. The letter I drafted said "handle all banking matters." They returned it the same day with a single note: "Please specify the exact transaction." Turns out the officer had seen hundreds of those generic letters and the bank's compliance team had recently tightened review standards after a fraud case in the Southeast region. I rewrote it with the exact dollar amount, recipient name, and ABA routing number. Processed within 48 hours after that.
How to Actually Get It Accepted
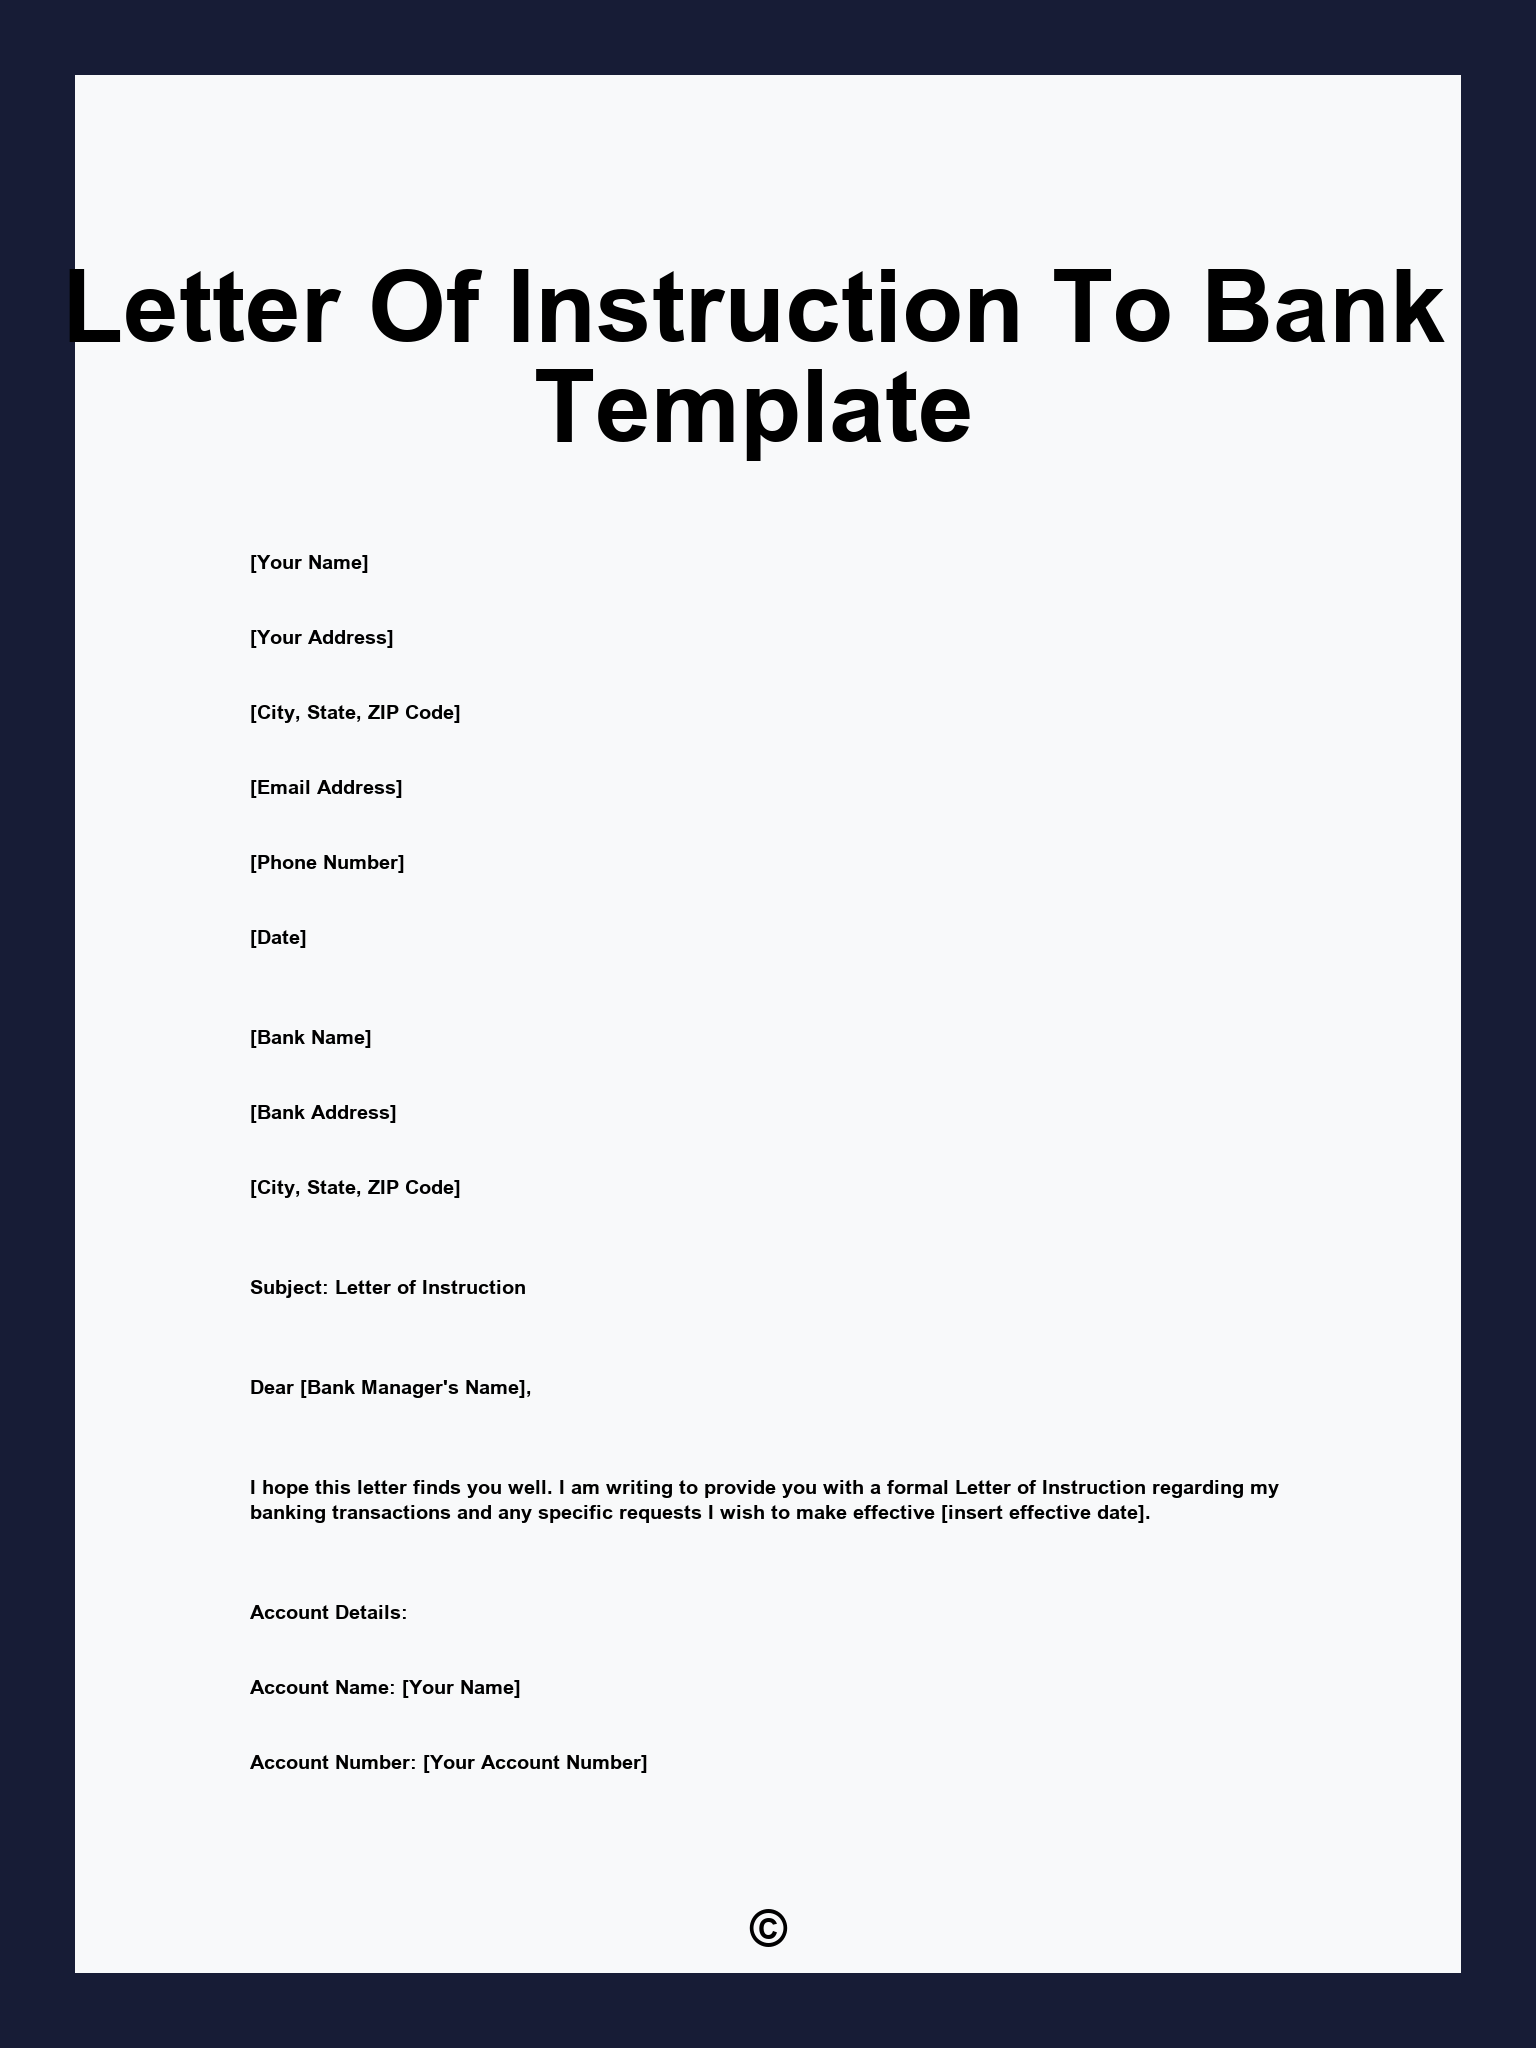
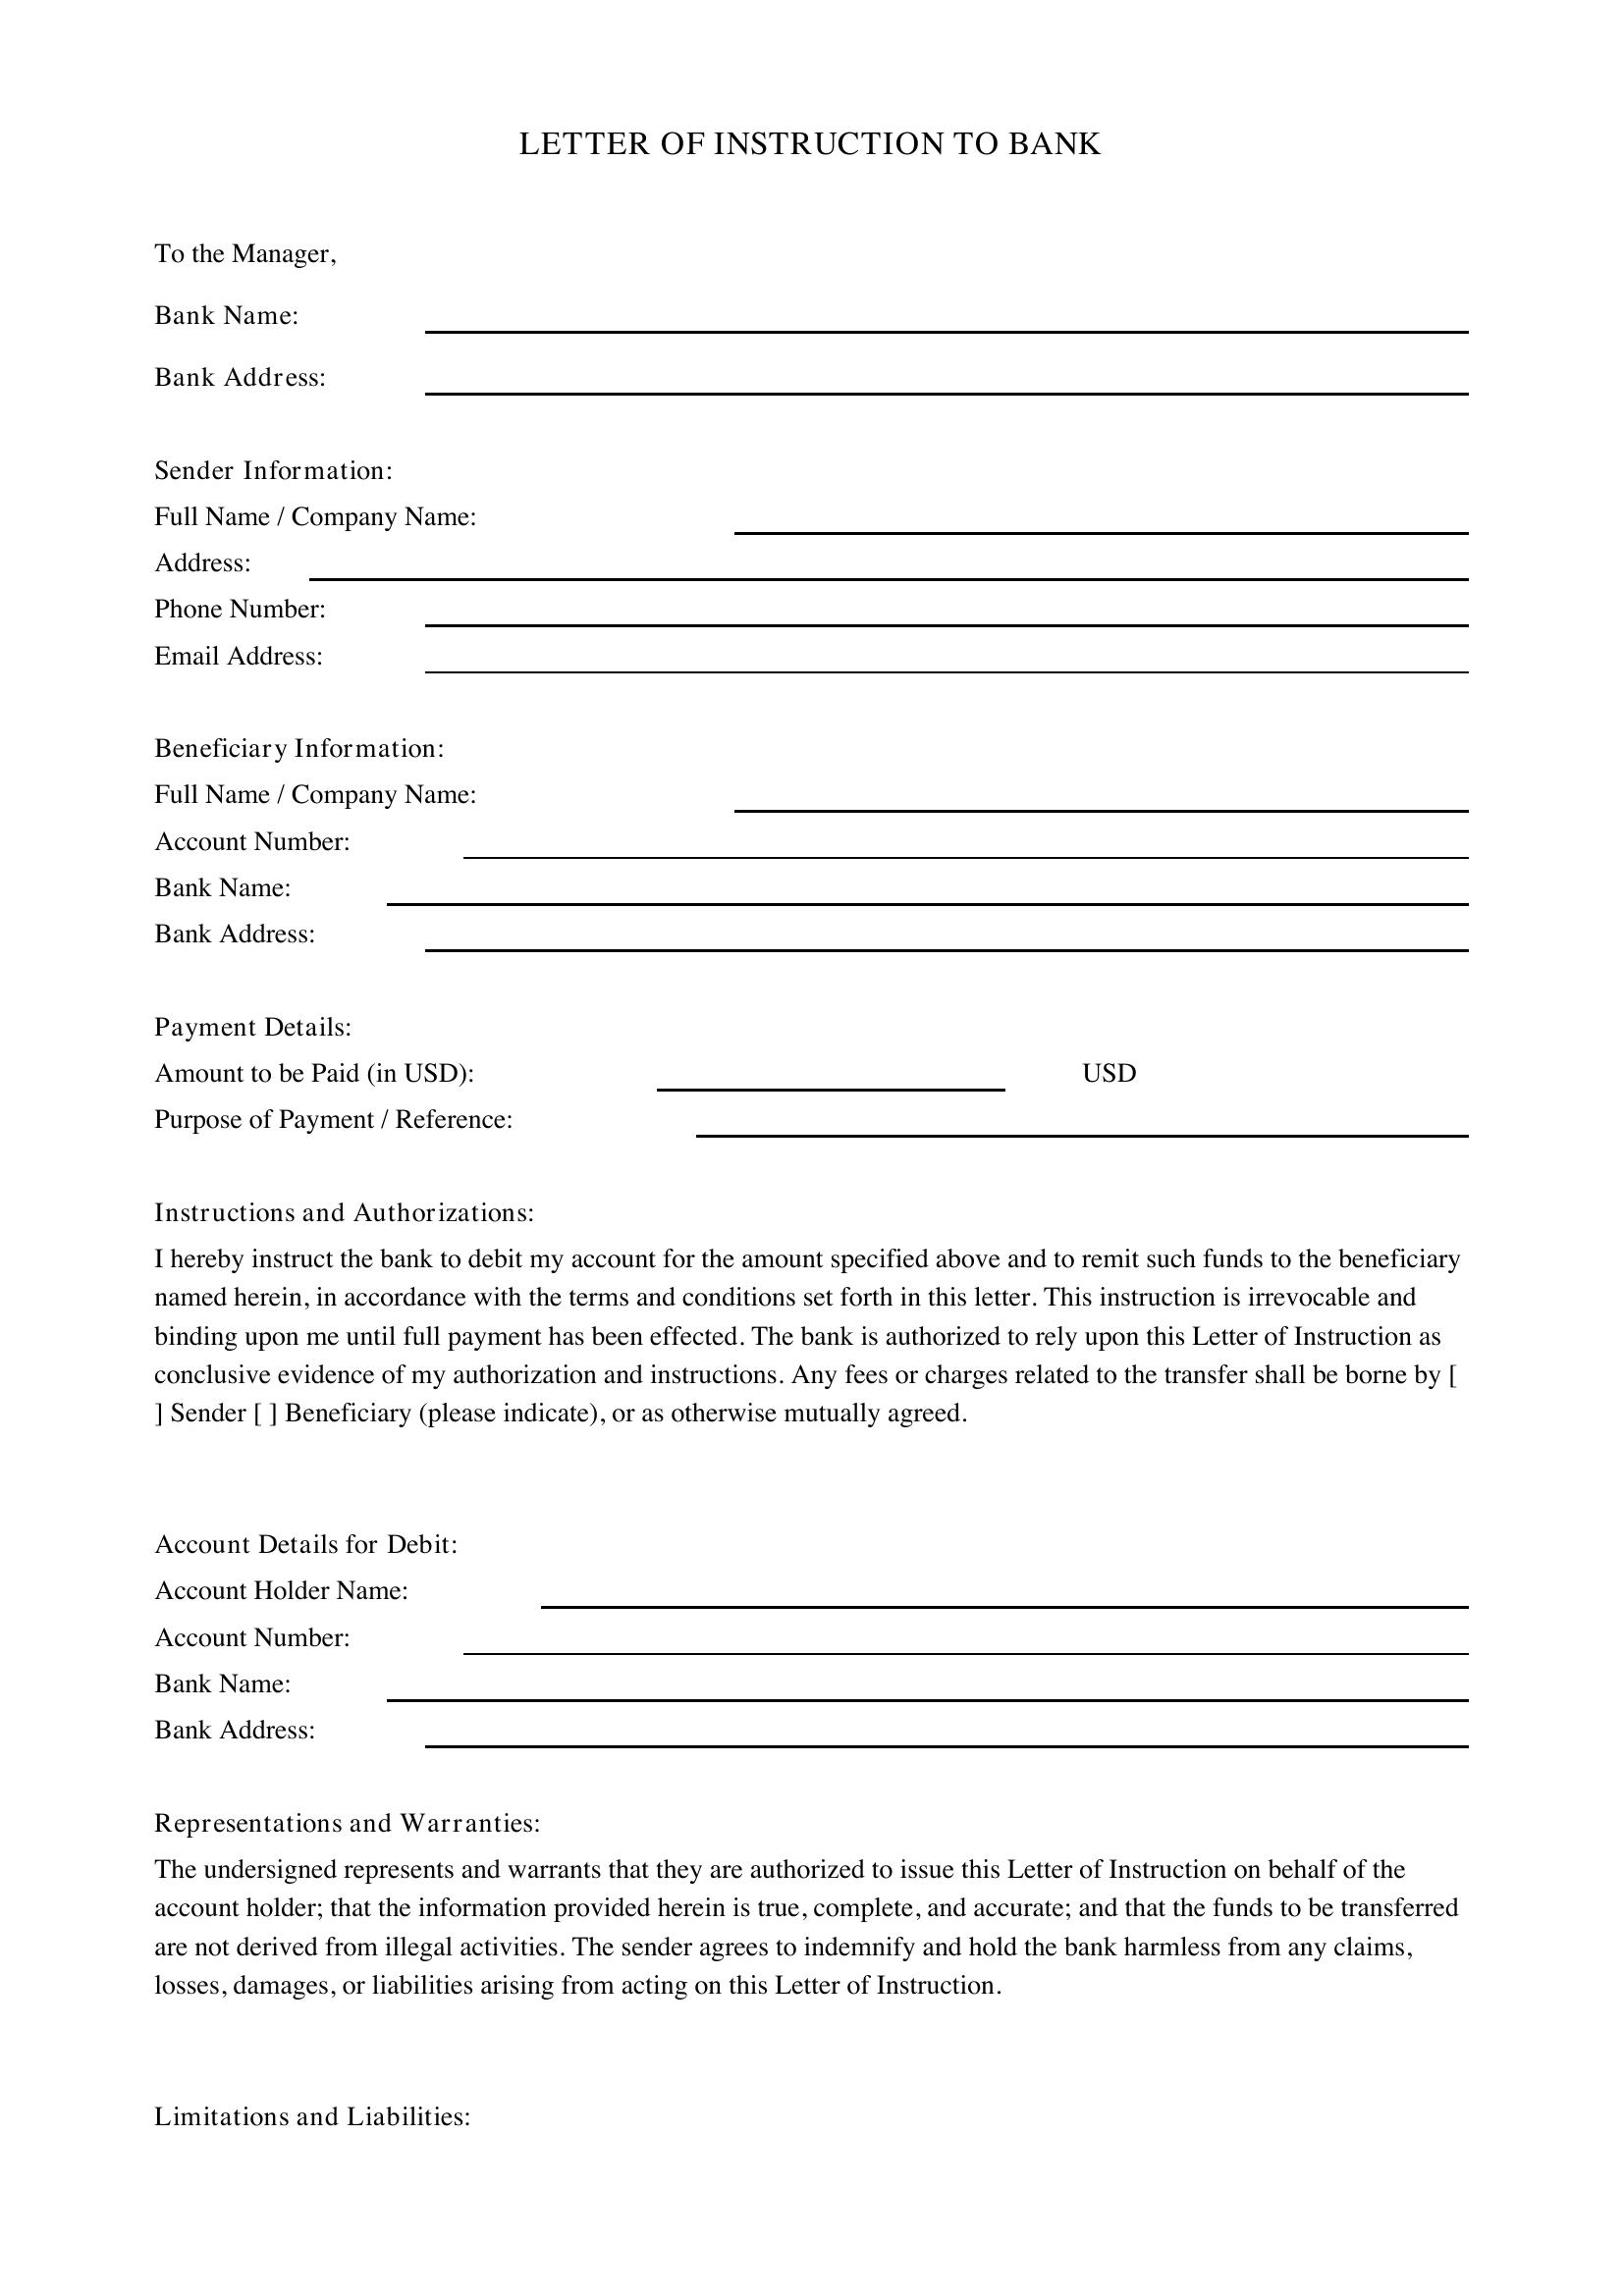
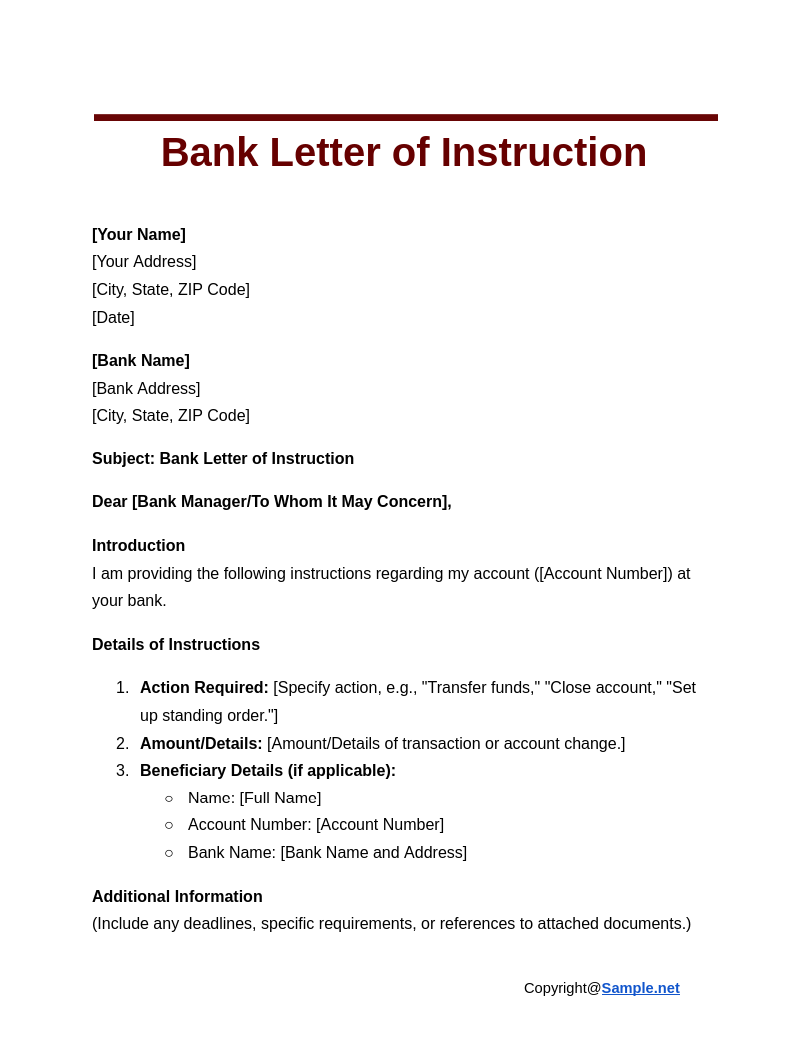
Start with the bank's current template if they have one. Many branches won't tell you upfront, but the wealth management or commercial banking division usually has a preferred form. Asking a relationship manager directly gets you further than calling general customer service. The template approach removes most guesswork because it already uses the bank's internal language. Notarization is almost always required. Some branches accept a simple notary seal, others require the notary to include specific certification language. Check with your branch before you leave home. I had to drive across town a second time once because the notary on my first attempt didn't include the state-mandated acknowledgment clause for financial documents. That added about forty-five minutes and a $35 notary refee. Get everything in writing before you schedule a branch appointment. Send a draft to your relationship manager or branch manager via secure message through online banking. They'll flag issues before you waste a trip. This step alone cuts the revision cycle from an average of two visits down to one in most cases.
When This Approach Fails Completely
Letters of instruction don't work for everything. You cannot use one to bypass a joint account requirement. If the account has multiple owners and the action requires all signatures, the bank will reject the letter outright regardless of how well it's drafted. You also can't use it to override a stop payment or freeze. Those require separate legal documentation. Power of attorney documents carry more weight than a standard letter of instruction. If you're dealing with an elderly parent or someone incapacitated, a properly executed POA is the right path. The letter works best for routine, time-sensitive authorizations where pulling out full POA paperwork would be overkill. The line between those two is blurry sometimes, and that's where people get confused. There's also a processing delay to factor in. Even a perfectly drafted letter takes anywhere from two to five business days to get reviewed and approved at Bank of America, depending on the branch and the complexity of the requested action. Emergency situations don't usually benefit from this route. If you need something done urgently, going through a branch manager with an existing relationship can sometimes expedite review, but don't count on it.
Get the Full Details
Practical Steps to Draft Your Own
Open a word processor and structure the document with these sections in order: account holder information, account details, authorized party information, specific instructions, scope limitation, effective date, and signature blocks. Keep each section to one or two sentences. No legal jargon. Plain English works better here because the bank officer reading it shouldn't need a law degree to understand what's being authorized. Include the date and make sure the effective date is explicit. Letters that say "effective immediately" without a calendar date cause problems during fraud review. Write the actual date. Same thing for the signature block — include printed name, handwritten signature, and date next to each signature. Missing a single date is the most common reason letters get sent back for minor corrections. If you're authorizing someone to access account statements or transaction history specifically, mention that separately from transaction authorization. Bank systems sometimes flag combined scopes as a compliance concern, and splitting them into distinct clauses keeps the review process moving faster.
The bottom line is that this document exists to fill a gap between full legal representation and doing nothing at all. It's useful, it's, and it requires attention to detail. Get the details right the first time and you're looking at a straightforward process. Skip the specifics and you'll be making trips to the branch instead.