What Actually Happens During Teller Training
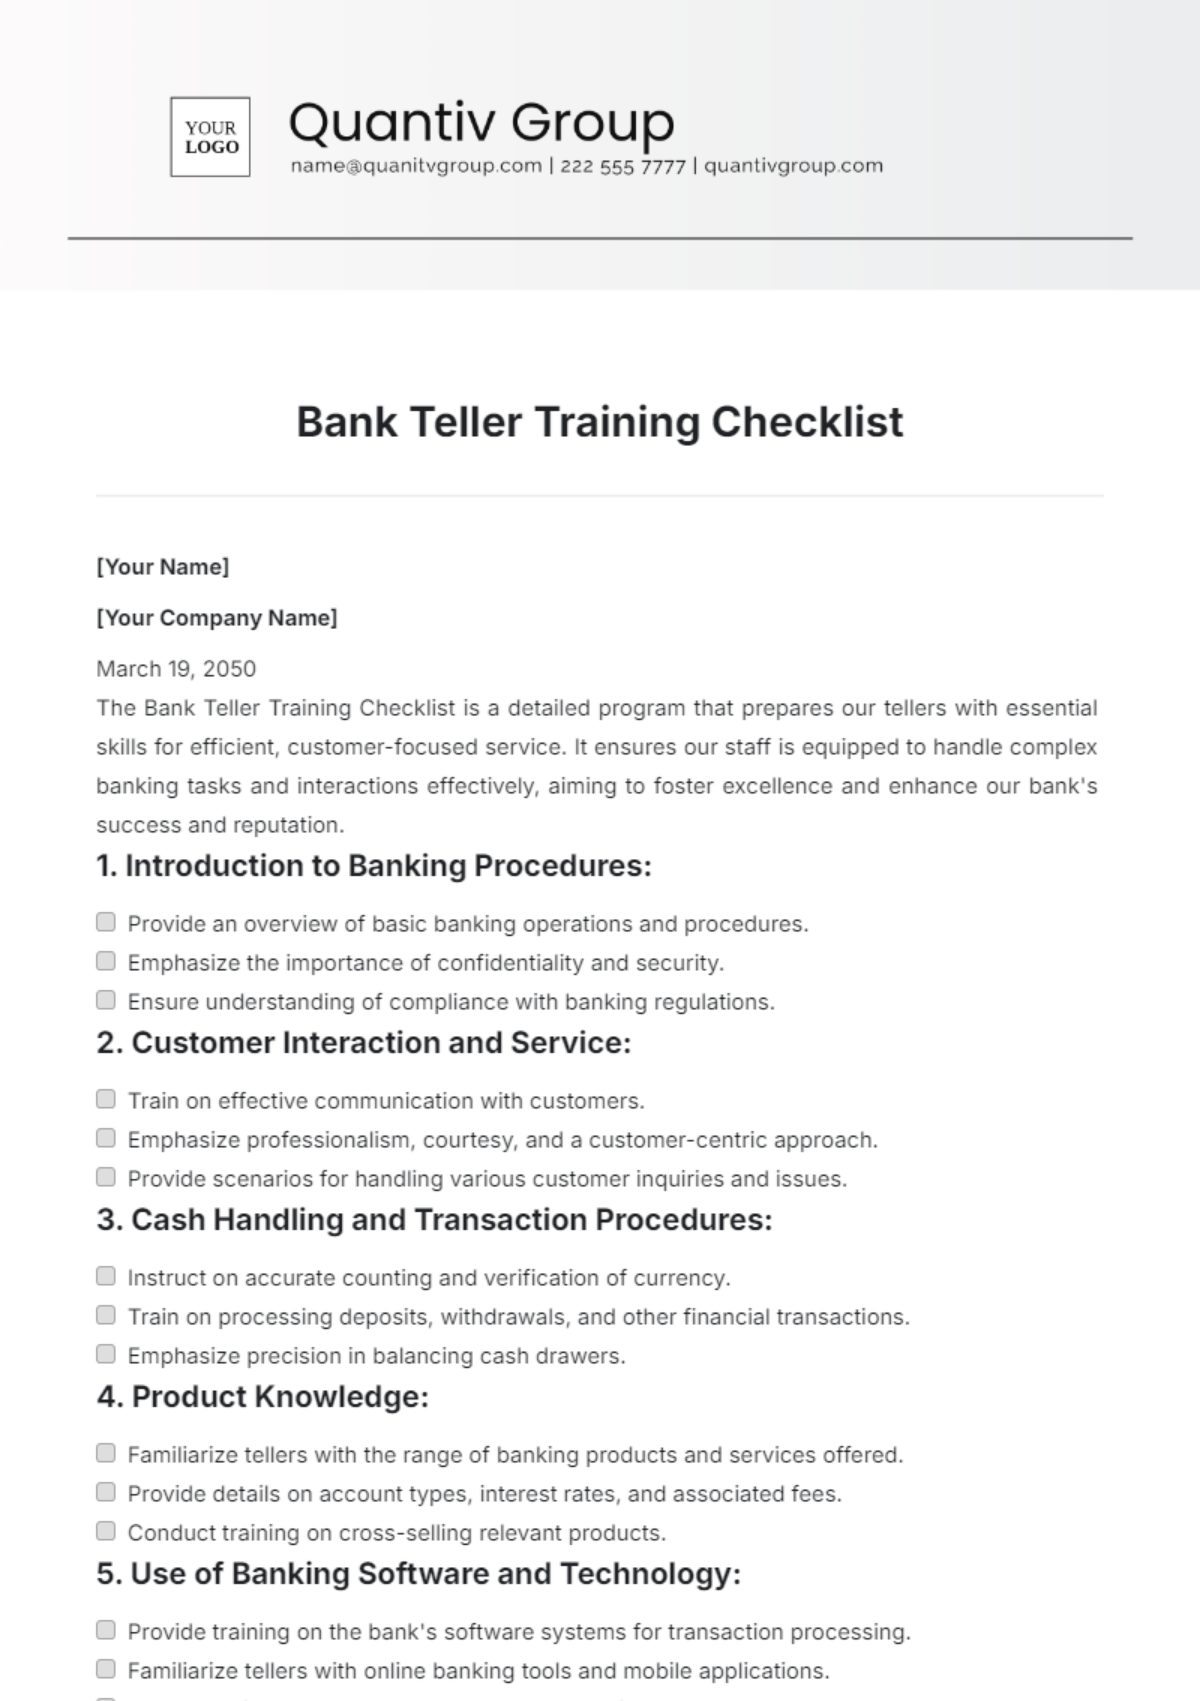
Most banks run their new teller programs through a structured classroom period followed by floor training. The classroom part covers basic system navigation, cash handling procedures, and compliance fundamentals. It typically runs one to two weeks depending on the institution. Then you get assigned to a senior teller for shadow shifts, where you spend maybe forty hours watching someone else handle deposits, withdrawals, check cashing, and the occasional difficult customer. The floor training phase is where people actually learn the job. Not because the classroom is useless — it's not — but because real transactions don't look like the practice ones. A deposit slip that looks straightforward on paper can have mismatched deposit categories, a counterfoil number that doesn't align with the account, or a secondary ID requirement that nobody bothered to mention in the manual. That's the kind of stuff you catch during Bank Teller Training, not from reading a PDF.
Bank Teller Training: A Practical Walkthrough
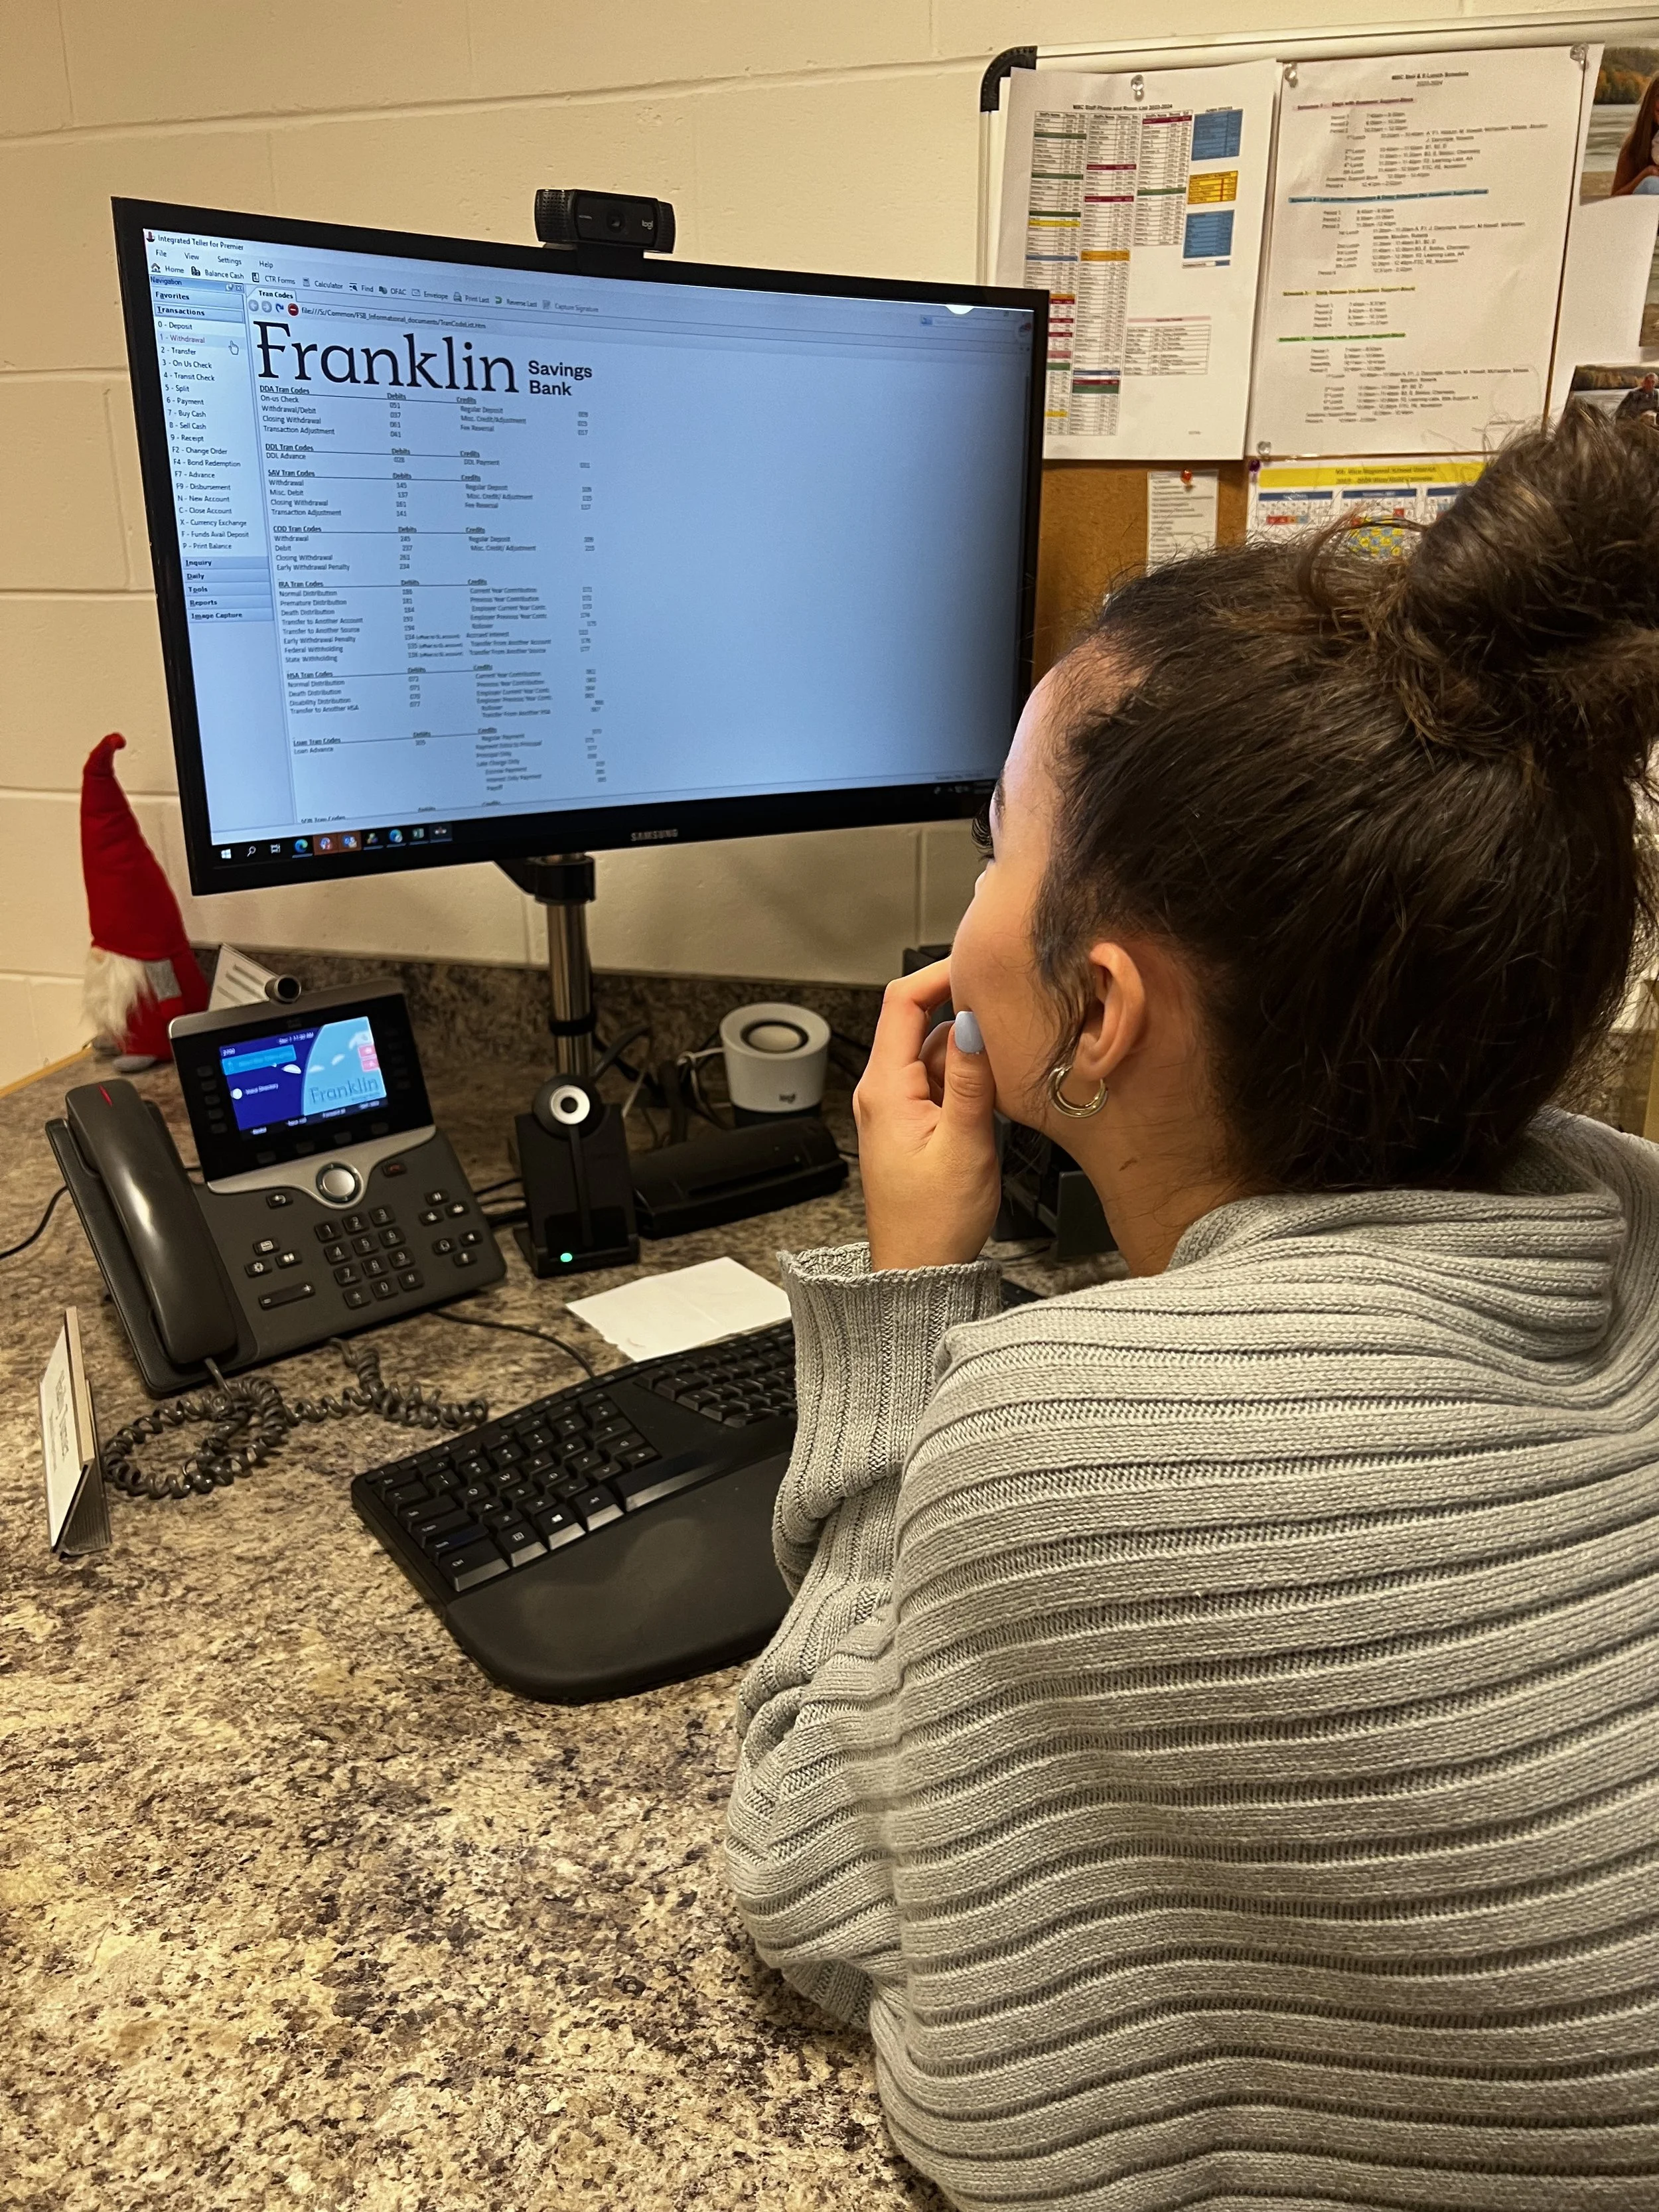
Here's how I'd structure actual training if you were building it from scratch, based on what I've seen work across multiple institutions. Phase One: System Familiarization (Days 1–3) New tellers need to understand the core banking platform before touching a single transaction. This means logging in, navigating menus, understanding the difference between a general ledger inquiry and a transaction history search, and knowing which screens lock and which ones require supervisor override. The biggest mistake I see trainers make here is rushing through this phase. People who skip proper menu navigation end up spending twice as long on basic operations during their first solo shifts. It takes about four hours of guided system walkthrough to do this right.
Phase Two: Cash Handling Fundamentals (Days 4–7) Cash counting starts with the basics — sorting notes by denomination, using the bill counter correctly, and understanding residual value expectations. Each teller has a starting cash position, usually around $3,000 to $5,000 depending on branch volume. Trainees learn to count their own drawer at the beginning and end of every shift. There's a variance tolerance, typically plus or minus twenty dollars, beyond which an incident report gets filed. Nothing builds attention to detail faster than being off by five dollars on a shift you're certain you balanced perfectly. Phase Three: Transaction Practice (Week 2)
Get the Full Details
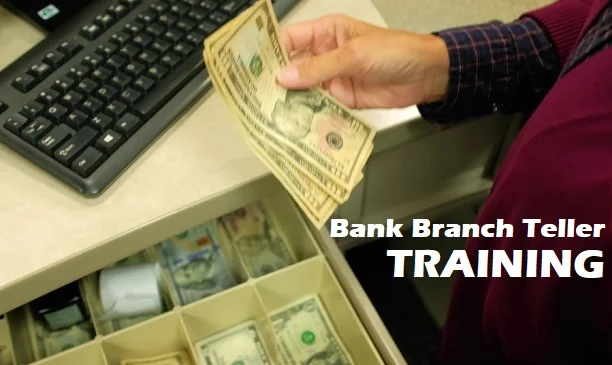
This is where trainees start running simulated transactions. Deposits, withdrawals, check cashing, money orders, cashier's checks, loan payments. They run each one three to five times in practice mode until the keystroke sequence becomes muscle memory. Most platforms have a training mode that doesn't post to real accounts. It's worth using it exhaustively. I've seen tellers who only ran two practice deposits walk onto the floor and mix up credit and debit entries on actual customer accounts. That costs the branch real money and real time to correct. Phase Four: Live Floor Training (Weeks 3–6) Trainees now sit at a real teller window with a trainer standing behind them. They handle actual customers, but the trainer intervenes before anything goes wrong. This phase is less about teaching transactions and more about developing judgment. When does a customer's ID look fraudulent? When should you escalate a large cash withdrawal? How do you handle someone who's clearly intoxicated or disruptive without causing a scene? These aren't covered in training manuals with enough specificity to matter.
I remember a specific case where a trainee was processing a check cashing for $2,400. The check looked fine. The customer had ID. But the trainee hadn't been taught to flag a mismatch between the customer's stated occupation on the application and the address history — which showed a different city than what they claimed. The trainer noticed it and flagged it. The check turned out to be from a business that had been reported for fraud two weeks earlier in a regional alert. That kind of pattern recognition comes from hands-on exposure, not classroom instruction. Phase Five: Solo Shifts with Monitor (Weeks 7–8) Trainees run their own shifts now, but a floater or supervisor checks their drawers after every transaction block. At first, they might need verification after every five transactions. By week eight, that drops to end-of-shift drawer counts only, provided there have been no exceptions or overrides. If a teller has consistent balance accuracy and zero compliance flags during this phase, they're typically certified for independent work.
Counter-Intuitive Things Nobody Teaches You
One thing that trips up even experienced trainers is the assumption that speed follows accuracy. It doesn't. Trainees who focus heavily on going fast early in their training actually develop bad habits that slow them down permanently. The ones who move deliberately and build accuracy first tend to pick up speed naturally by month three. Speed without accuracy means reprocessing transactions, which takes longer than just doing them slowly the first time. Another overlooked piece is cross-training on non-cash products. Many new tellers can handle deposits and withdrawals flawlessly but freeze up when a customer asks about opening a certificate of deposit or setting up a direct deposit. Product knowledge gaps show up most often during peak hours when there's no time to look things up. Trainers should spend at least half a day specifically on product menus and common customer requests that aren't cash transactions. Compliance training is another area where most programs cut corners. Anti-money laundering basics, suspicious activity reporting thresholds, and customer identification program requirements are usually covered in a single module. But tellers are the front line for detecting layering attempts, structuring, and other red-flag patterns. A teller who can recognize a structuring pattern — someone making multiple deposits just below the reporting threshold on the same day — is worth significantly more than one who just processes transactions mechanically. This isn't something that gets reinforced naturally on the floor. It needs dedicated scenario-based training.
Where Standard Programs Fall Short
The biggest gap in most teller training programs is handling difficult customer interactions. Every manual has a section on professional demeanor, but nobody practices de-escalation. A trainee who's never handled an angry customer who's been told their check is still pending will not perform well when one actually sits down at their window. Role-playing these scenarios during training makes a measurable difference. I've seen branches implement a ten-minute role-play exercise before floor training begins and watch complaint rates drop significantly within the first quarter. Another limitation is technology-specific training. Some banks use legacy systems that require entirely different workflows than modern platforms. Trainees coming from other institutions or from simulated training environments sometimes struggle with systems that have outdated interfaces or unusual navigation patterns. If your bank is in the middle of a system migration, training timelines can stretch by two to three weeks because trainees are learning two systems simultaneously. Budget for that. Finally, there's the issue of trainer availability. The quality of floor training depends almost entirely on the trainer's patience and teaching ability, not just their transaction speed. A top-performing teller isn't automatically a good trainer. Some of the most skilled tellers I've worked with were terrible at explaining why they were doing something a certain way. They'd say "just do it this way" without any context. Branches that invest in actual trainer development — teaching senior tellers how to break down processes for beginners — see dramatically better certification pass rates and lower post-training error rates.
If you're building a training program from scratch or updating an existing one, the most practical thing you can do is map every transaction type to a specific training milestone with clear pass/fail criteria. Don't rely on vague assessments like "shows adequate proficiency." Define what adequate means for each transaction: correct keystrokes, within time tolerance, proper documentation, and zero compliance flags. That level of specificity is what separates a training program that produces competent tellers from one that just fills seats.