Understanding Bi-Weekly Amortization: What Actually Happens When You Pay Every Two Weeks
I spent three years running mortgage servicing software before I ever saw a borrower complain about bi-weekly amortization, and honestly, the complaints were almost always about the same thing: the payment amount on their statement didn't match what they thought they were supposed to send. It's a simple misunderstanding that creeps in because the math looks different than what people are used to seeing. A standard monthly mortgage amortization schedule has 360 payments over 30 years. A bi-weekly schedule has 26 half-payments per year, which adds up to 13 full monthly payments when you do the math. That one extra payment every year is where the whole benefit comes from, and it's also where most people get confused about what they're actually paying.
How a Bi Weekly Amortization Schedule Actually Works
The structure is straightforward once you stop treating it like a mystery. You take your regular monthly principal and interest payment, divide it by two, and pay that amount every two weeks. Because there are 52 weeks in a year, you make 26 payments instead of 12. Twenty-six halves equal thirteen wholes, so you're effectively making one extra monthly payment per year without having to remember to do anything unusual. On an amortization basis, each payment still covers accrued interest first and then reduces principal. The difference is that with bi-weekly payments, interest accrues less frequently between payments because you're cutting the gap from 30 days down to 14. That matters more on larger balances and higher rates. Over the life of a loan, this typically shaves two to four years off a 30-year term and saves anywhere from 8% to 14% in total interest, depending on the rate and loan amount. Here's what nobody tells you upfront: your loan servicer may not call it bi-weekly amortization. They'll call it a accelerated payment plan or a voluntary extra payment program. The accounting treatment is identical, but the label matters because it determines whether your payments get applied correctly or whether you spend six months calling customer service because something fell through the cracks.
I learned this the hard way in 2019 when a borrower sent me a spreadsheet showing her bi-weekly payments were being treated as monthly installments by her servicer's system. She'd been paying extra for eleven months without the principal reduction showing up on her statements. The fix was filing a formal request to convert the loan to an official bi-weekly payment frequency with the servicer, not just continuing to send half-payments and hoping for the best. That process took about three weeks and required her original loan documents and a written authorization.
Get the Full Details
The Math Behind the Extra Payment
Let me give you a concrete example so you can see where the savings actually come from. Say you have a $300,000 loan at 6.5% interest over 30 years. Your standard monthly payment is approximately $1,896. That breaks down to about $1,625 in interest and $271 in principal in the first month. The early years of any amortizing loan are heavily interest-weighted, which is why small changes in payment frequency have outsized effects. Switch to bi-weekly: your payment becomes $948 every two weeks. Over 12 months you're sending $11,376 instead of $22,752. Wait, that's the same total, right? No. Because 26 times 948 equals $24,648, which is exactly one extra monthly payment. That extra $1,896 goes entirely toward principal in the early years, and because it reduces the balance faster, every subsequent interest calculation starts from a lower number. The cumulative effect compounds in a way that feels almost unfair if you've never watched it play out. On that same $300,000 loan at 6.5%, the bi-weekly schedule pays off the loan in roughly 25 years and 8 months instead of 30. Total interest drops from about $382,000 down to approximately $305,000. That's a savings of roughly $77,000 over the life of the loan, and it happens without you having to refinance or change lenders.
What's interesting about this from a modeling perspective is that the savings aren't linear. They cluster heavily in the first seven to ten years, which is exactly when most people sell their homes or refinance. If you're planning to move within five years, the bi-weekly advantage barely registers. You might save two or three thousand dollars in interest, but you've also locked yourself into a payment schedule that requires more frequent transactions and more attention to timing.
Where Bi-Weekly Amortization Breaks Down
I need to be blunt about the scenarios where this doesn't work well, because most articles on the topic skip this part entirely. If you have an adjustable-rate mortgage with a cap structure that resets every year, the bi-weekly payment model becomes unpredictable. Your payment could jump 20% at reset, and the half-payment amount you've been basing your budget on suddenly doesn't cover the new principal and interest figure. The servicer won't adjust your bi-weekly schedule automatically, and you'll be making underpayments without realizing it. Another edge case that trips people up: Federal student loans and some institutional loans don't support bi-weekly payment frequencies at all. I ran into this with a borrower who had both a mortgage and a private student loan, and she assumed the bi-weekly strategy would apply across both. The student loan payment schedule was lock-step monthly, and her extra half-payments just sat in a suspense account for months. She lost the timing advantage on that debt entirely. There's also the question of opportunity cost that deserves more attention than it gets. If you have a mortgage at 6.5% and you could alternatively invest that same extra $1,896 per year in a diversified portfolio averaging 7% returns, you're essentially breaking even on a pre-tax basis. After tax, the investment side usually wins. The bi-weekly strategy is really a forced savings mechanism disguised as a payment schedule, and it only makes sense if you can't reliably invest surplus cash or if your mortgage rate is high enough to outweigh investment alternatives.

Sometimes the simplest alternative beats the bi-weekly model altogether. If your goal is just to make one extra payment per year, you can do that on a standard monthly schedule by setting up a calendar reminder in January to send an additional principal-only payment. The result is mathematically identical, the payment frequency stays predictable, and you avoid any risk of the servicer mishandling half-payments. I recommend this approach to most of my clients because it gives them the same amortization benefit without the administrative overhead.
Building Your Own Schedule Without Software
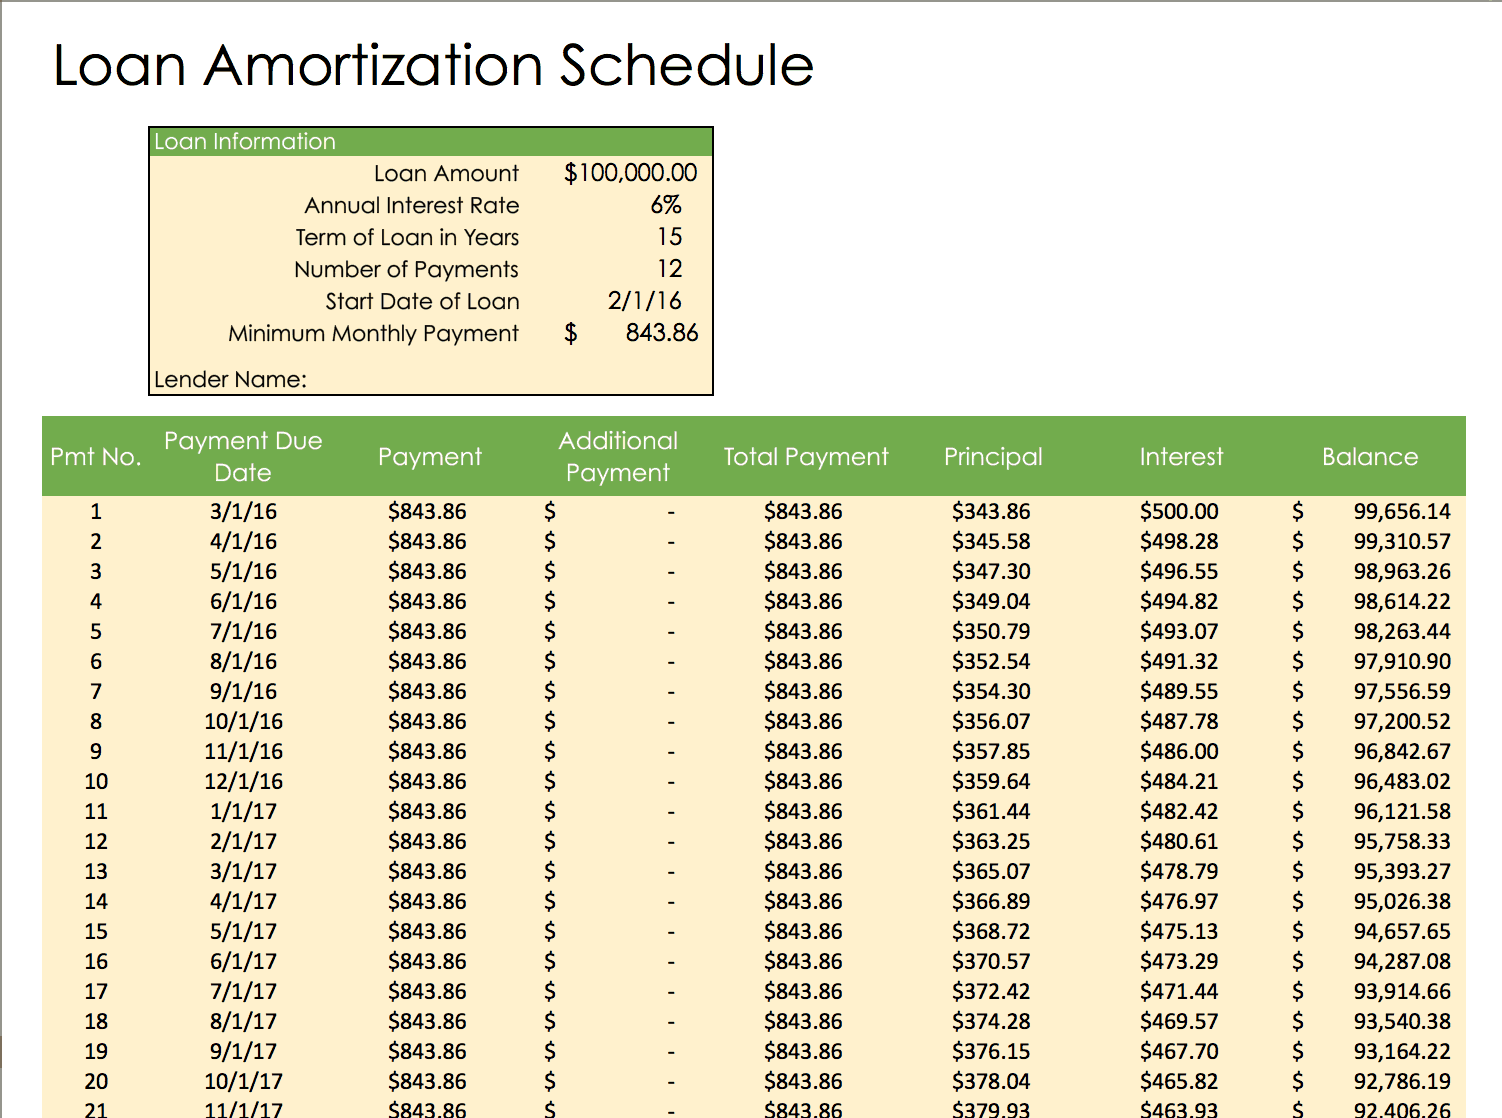
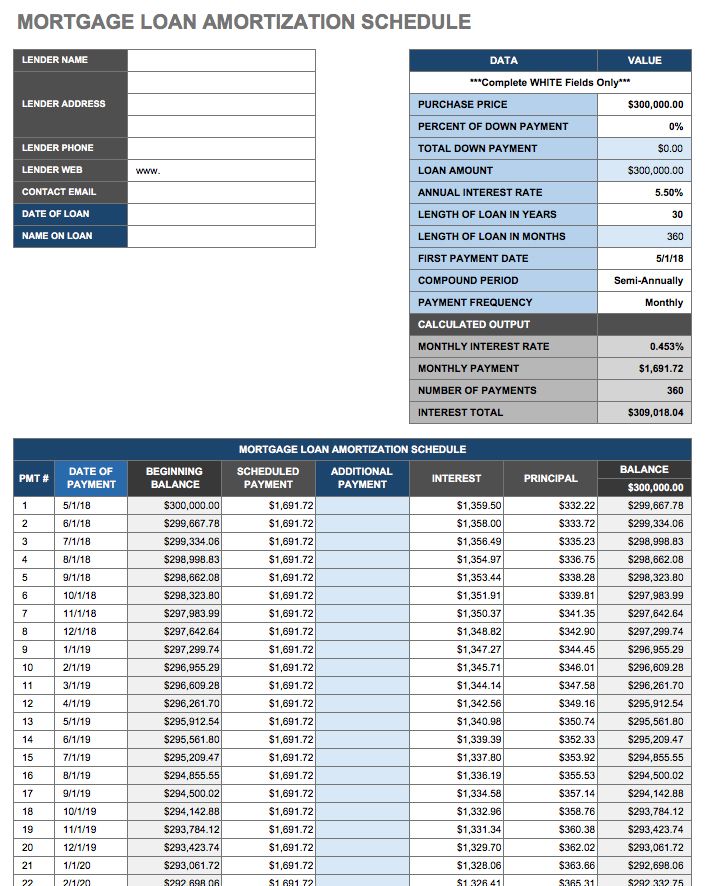
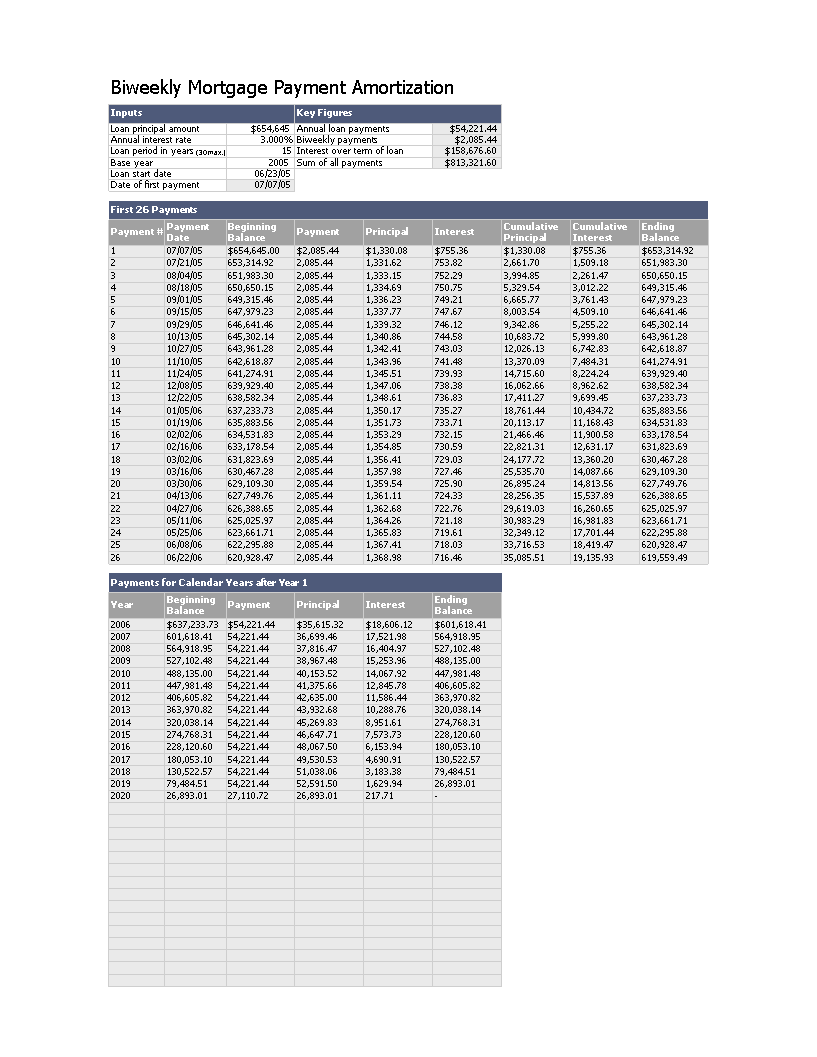
You don't need a specialized tool to track a bi-weekly amortization schedule. A basic spreadsheet will do, and setting one up takes about 15 minutes. Start with columns for payment number, payment date, payment amount, interest portion, principal portion, and remaining balance. Fill in your loan terms at the top, then use the PMT function to calculate your monthly payment, divide that by two for your bi-weekly amount, and build out the rows using the standard amortization formula: interest for each period equals the remaining balance multiplied by the periodic rate, and principal equals the payment minus that interest amount. The periodic rate for bi-weekly is your annual rate divided by 26, not 12 divided by 2. This is a common error that throws off the entire schedule by a small but measurable amount over time. I've seen spreadsheets online that use the wrong divisor, and the discrepancy is small enough that most people don't notice, but it's there, and it matters if you're comparing schedules side by side. If you want a downloadable template rather than building from scratch, most mortgage calculators on financial sites offer Excel or CSV exports. Search for "bi-weekly amortization schedule template" and you'll find dozens of options. The free ones are usually adequate, but check the formulas before you trust them with your actual loan numbers. I've encountered at least three templates in the past year where the principal calculation was referencing the wrong cell, which made the final balance wrong by several thousand dollars.
What to Expect From Your Servicer
Not all servicers handle bi-weekly payments the same way. Some will automatically convert your loan to a bi-weekly frequency and adjust your escrow calculations accordingly. Others will accept your half-payments but process them as if they were monthly installments, which means you're not actually getting the accelerated payoff you expected. A few will charge a setup fee between $100 and $300 for converting to a bi-weekly plan, and some won't offer the option at all. Before you switch, call your servicer and ask three specific questions: whether they support bi-weekly payment frequency natively, whether there are any fees for the conversion, and how they handle principal-only payments versus standard installment payments. Write down the answers and the representative's name. If they can't answer clearly, that's a sign you should either set up the extra payment manually on your own or look into a different servicing approach. The bottom line is that bi-weekly amortization is a legitimate strategy with real mathematical benefits, but it's not a silver bullet and it doesn't belong in every financial situation. Understanding the mechanics, knowing where it breaks down, and having a fallback plan if your servicer doesn't cooperate will save you more time and money than any template ever could. I've seen borrowers lose thousands by assuming the system would work correctly without verifying how their specific loan was being processed, and that's a mistake you don't need to make.