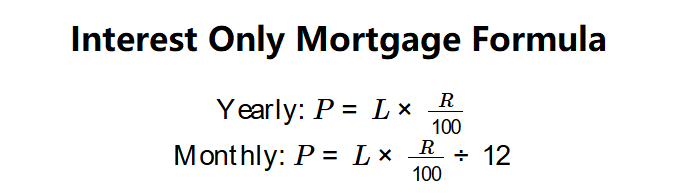
How to Calculate an Interest Only Mortgage Payment
The basic calculation is simpler than most people expect. Take your loan amount, divide it by 12 to get the monthly principal, then multiply by your annual interest rate divided by 100. Wait, that's wrong. The actual formula is even more straightforward: multiply the loan balance by the annual interest rate, then divide by 12. That's it. You're only paying interest, so there's no principal reduction to factor in during the interest-only period. For example, if you have a $400,000 interest-only mortgage at 6.5% annual interest, your monthly payment would be $400,000 times 0.065, divided by 12, which equals approximately $2,166.67. That number stays exactly the same every month for the duration of the interest-only phase, whether that's 5, 7, 10, or in rare cases even 15 years. The stability is the main selling point, and it's also what makes this product dangerous if you don't understand what happens after that period ends.
Using an Interest Only Mortgage Calc Tool
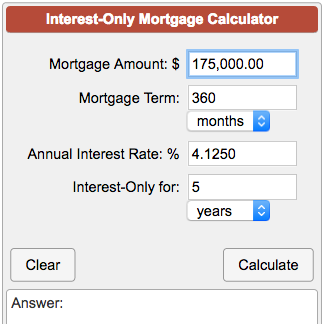
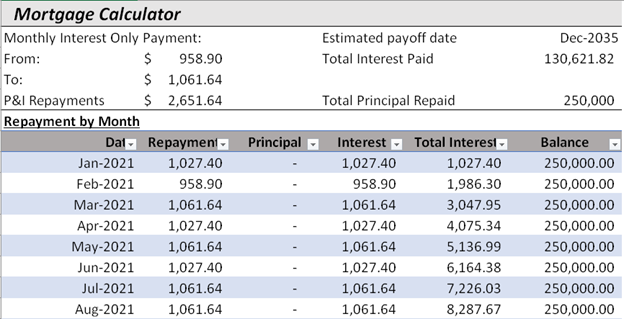
Most calculators online follow the same basic approach, but the good ones let you adjust the interest-only period length and show you what the payment looks like once amortization kicks in. That second number is the one people forget to check. A calculator that only shows the IO payment without the post-amortization rebound isn't really helping you make a decision. It's showing you the easy part and hiding the hard part. When I was evaluating an IO refinance for a client back in 2019, I ran into a edge case that every standard calculator missed. The loan had a hybrid structure where the first 7 years were interest-only at 4.25%, and then it automatically converted to a 30-year fully amortizing schedule. The calculator I was using showed a monthly payment of $1,484 during the IO period, which looked reasonable. But after year 7, the remaining balance was still $350,000 because no principal had been paid down, and the amortization kicked in at the then-current rate of 5.1%. The new payment jumped to $1,903. That's a $419 increase out of nowhere, and the calculator I'd been using completely failed to project that transition. It only showed the IO payment and called it a day. The workaround was to manually model the post-IO phase in a spreadsheet. I set up two sections: one for years 1 through 7 showing the flat interest-only payment, and a second section starting in year 8 that recalculated the payment based on the remaining balance, the new rate, and the remaining amortization term. That second section revealed the payment shock immediately. Any calculator worth using should be able to do this projection natively, and if it can't, you're better off building a simple two-phase model yourself. It takes about ten minutes and saves you from being blindsided.
Here are a few things that most guides don't mention but matter significantly in practice. First, the interest-only period doesn't mean you're paying less total interest over the life of the loan. You're just deferring principal repayment, which means more interest accumulates overall. Second, some IO loans have points or fees baked into the rate that aren't obvious from the payment alone. Always check the APR, not just the note rate, because the effective cost can differ by a full percentage point or more depending on origination charges. Another nuance is how property appreciation during the IO period interacts with your loan-to-value ratio. If your home value drops while you're only paying interest, you could find yourself underwater even though your payment looks manageable. I've seen this play out in markets where values corrected 15 to 20 percent during the IO window, and borrowers who thought they had equity built up suddenly couldn't refinance or sell without bringing cash to closing. The payment calculator won't tell you this because it has no way to factor in property value changes. If you're considering an interest-only mortgage, the calculation itself is the easy part. The harder part is modeling what happens after the IO period ends and honestly assessing whether your income will support the higher payment. Most people I work with focus entirely on the low initial payment and skip ahead to signing. That's where the mistakes happen. Get the Interest Only Mortgage Calc working correctly for both phases, compare the total cost against a standard amortizing loan over the same timeline, and only then decide if the cash flow benefit is worth the long-term interest drag.
Get the Full Details