Calculating Motorcycle or Bike Loan Payments
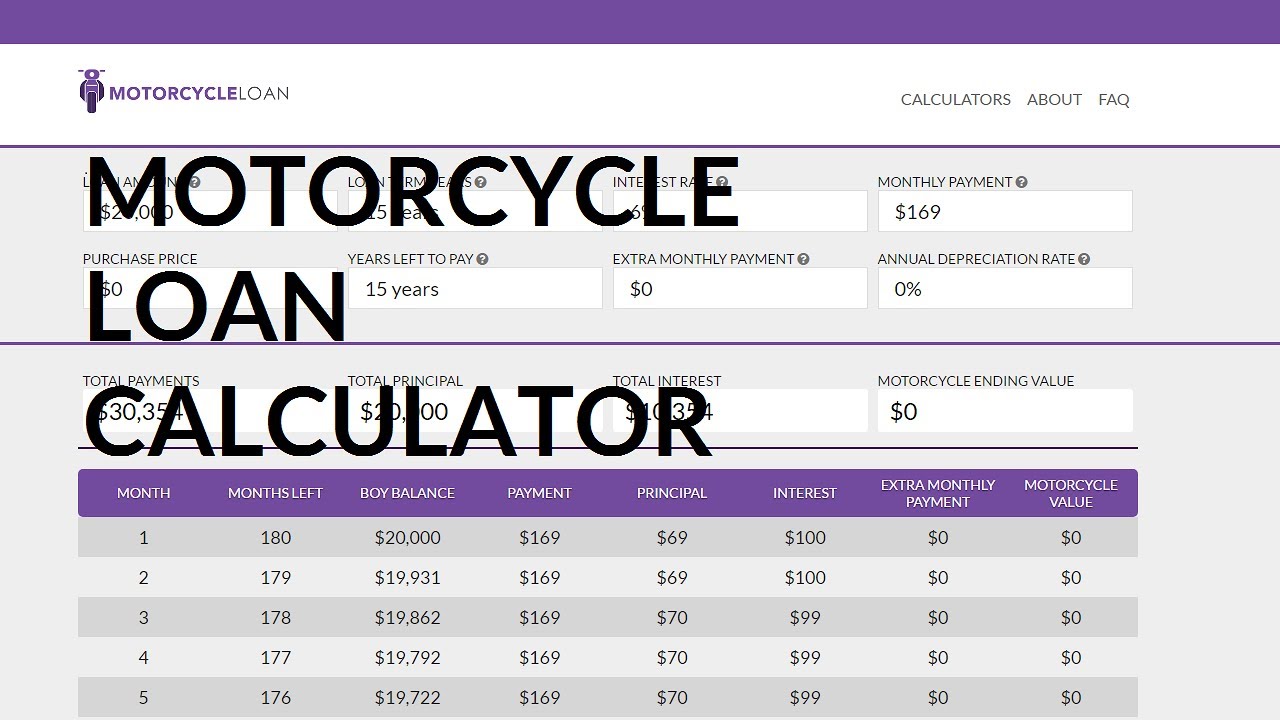
Most people don't think about it until they're staring at a sales agreement with monthly payments that seem higher than expected. A Bike Finance Calculator takes the guesswork out of two-wheeler loans, whether you're financing a street bike, commuter scooter, or adventure touring machine. The basic inputs are straightforward: your desired loan amount, the annual interest rate the dealer or bank is offering, and the repayment period in months. Some calculators also factor in down payment, processing fees, and whether it's a balance transfer from an existing loan. I ran into an edge case last year when a dealer quoted 8.5% APR but the actual monthly payment I calculated using their spreadsheet came out $47 higher than expected. The problem was hidden prepayment penalties and mandatory GAP insurance bundled into their calculation. After calling three lenders, I found one that used pure amortization without the add-ons, which dropped my payment by exactly that amount.
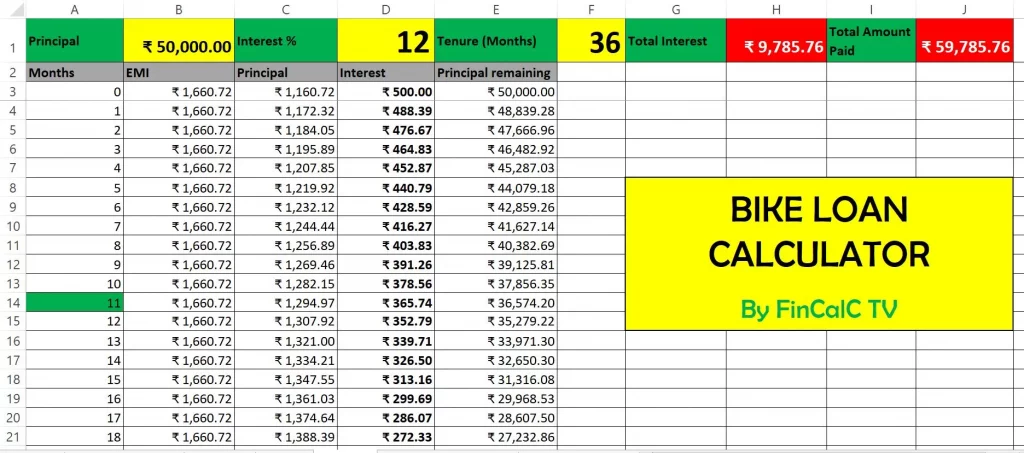
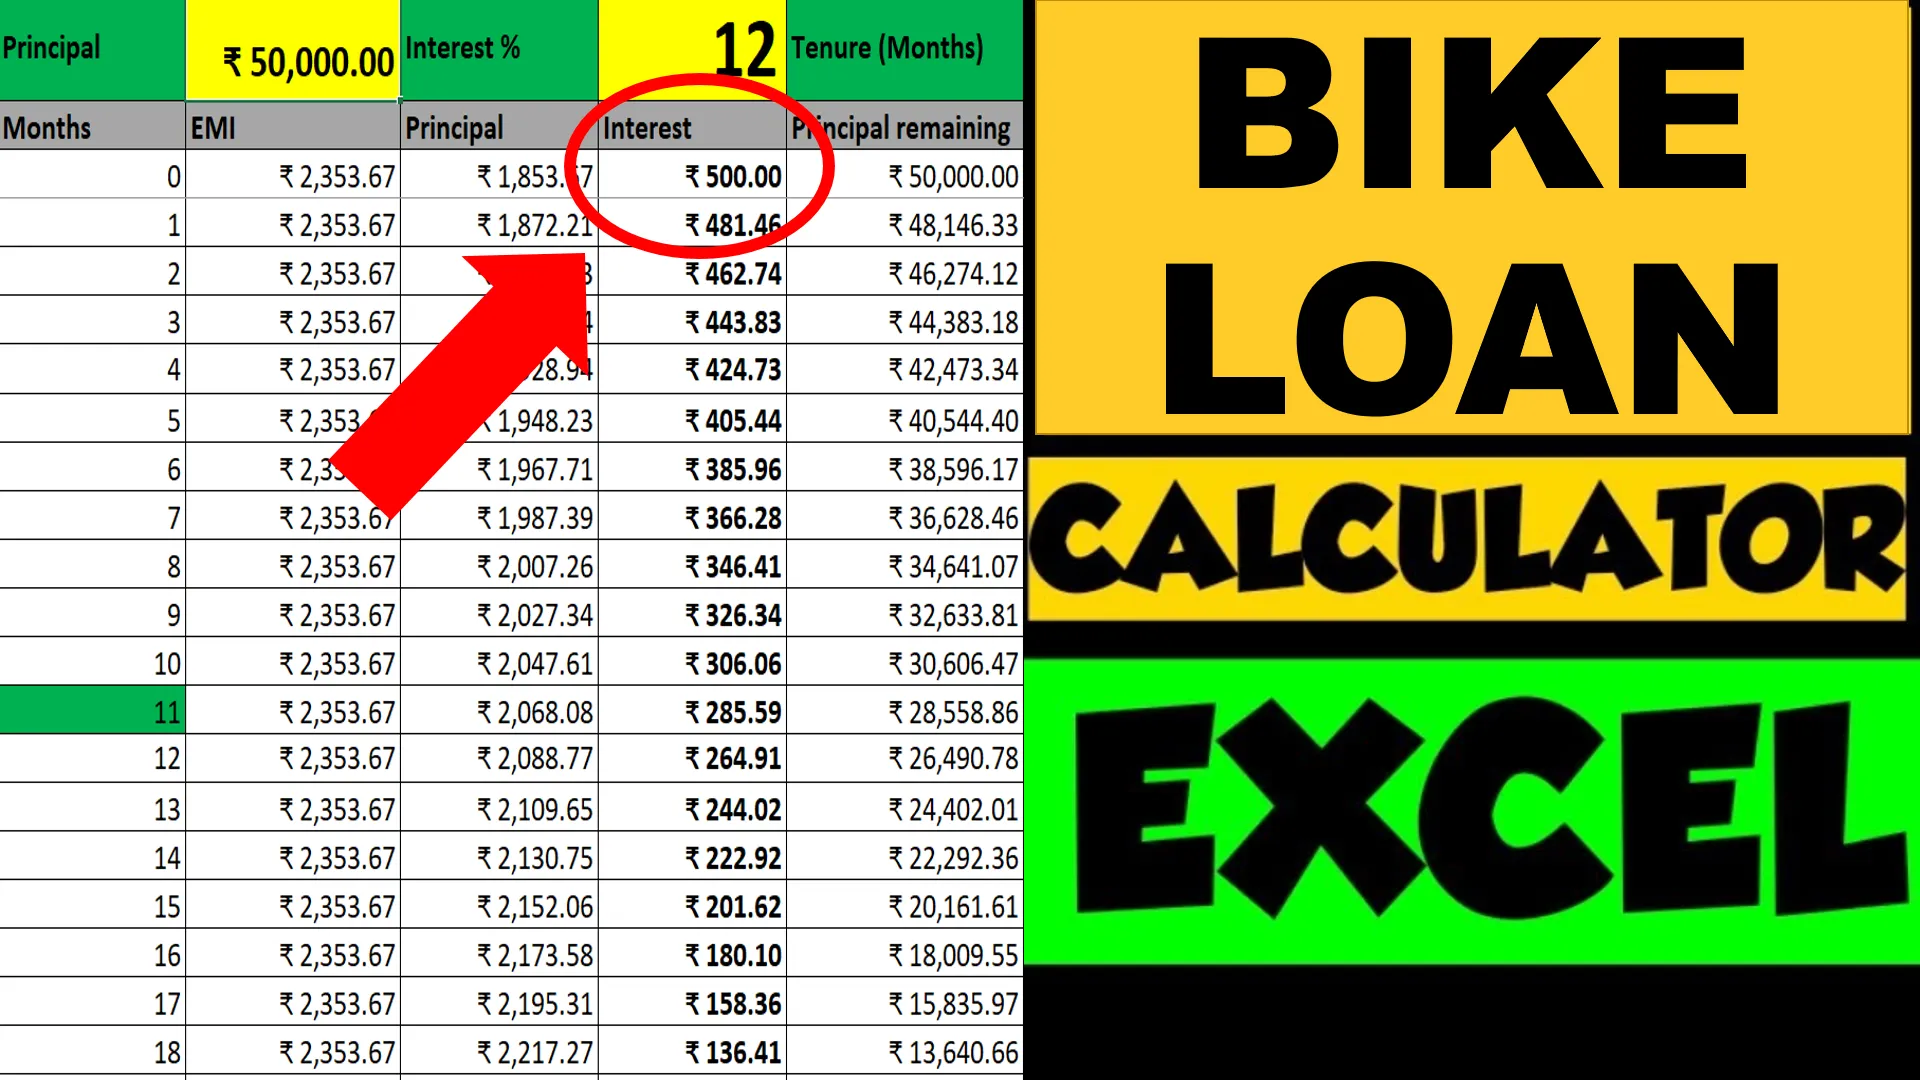
The standard formula most calculators use is the reducing balance method, which looks like this: M = P × [r(1+r)^n] / [(1+r)^n - 1] Where M is your monthly payment, P is the principal loan amount, r is your monthly interest rate (annual rate divided by 12), and n is the total number of payments. This is different from simple interest loans where the interest is calculated upfront and added to the principal, which makes the total cost significantly higher even though the quoted rate looks lower.
What Most People Miss About Bike Financing
Here's something that trips up first-time buyers regularly: the displayed interest rate isn't always the effective rate you pay. Dealers often quote a flat rate, but the reducing balance calculation means you're paying interest on the full amount throughout, not on the declining balance. A 10% flat rate actually works out to closer to 18% effective rate on a reducing balance loan. Another counter-intuitive point: shorter loan terms sometimes come with higher monthly rates. Lenders price risk differently for two-wheeler loans than auto loans. A 36-month motorcycle loan might carry a slightly better rate than a 60-month one, but the monthly payment jumps significantly. I've seen customers stretch to 72 months just to keep payments under a certain threshold, not realizing they'll pay nearly double the interest over the life of the loan. The balloon payment structure is another trap. Some lenders offer a large deferred payment at the end, sometimes 30-40% of the original loan amount. The monthly payments look attractive, but you still need to come up with that balloon at maturity. If you can't refinance or sell the bike to cover it, you're in a tight spot. Only use balloon structures if you have a clear exit strategy.
Get the Full Details
When a Bike Finance Calculator Falls Short
Online calculators give you a baseline, but they can't account for your credit profile. A score above 750 might get you the advertised rate, while someone at 650 could be quoted 3-4% higher. Two people financing the exact same bike at the same dealer can end up with completely different monthly payments because of this. Insurance costs are another variable most calculators ignore. Comprehensive coverage on a new sport bike can run $800 to $1,500 annually, depending on your location and riding history. That's not part of the loan payment, but it's a real cost that affects your budget. If you're looking at used bike financing, the rules change again. Many lenders won't finance bikes older than five years, and the rates jump for anything beyond three years old. The available loan amounts are also typically capped at 70-80% of the bike's assessed value, not the purchase price.
A practical workaround I recommend: calculate three scenarios using your Bike Finance Calculator. First, the best-case rate you qualify for with excellent credit. Second, the average market rate for your credit tier. Third, the worst case if you need subprime lending. The range between these three tells you how much room you have to negotiate or whether you need to improve your credit before applying. Download a calculator and run through the numbers before you walk into a dealership. Walk away if the monthly payment doesn't match what their own calculator shows. It usually means they're padding the numbers somewhere.