How Biweekly Mortgages Actually Work
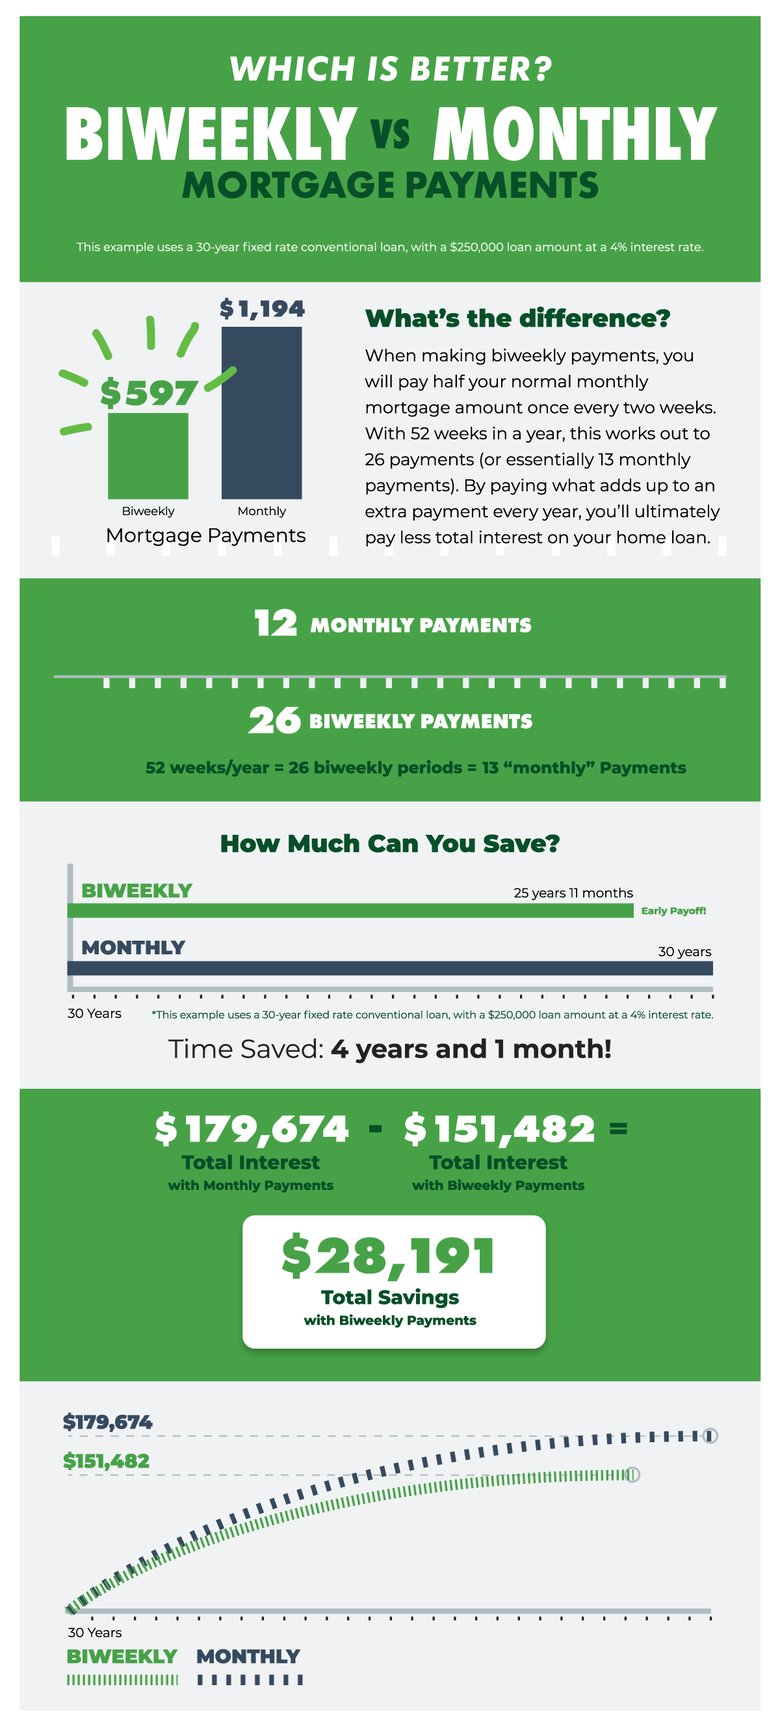
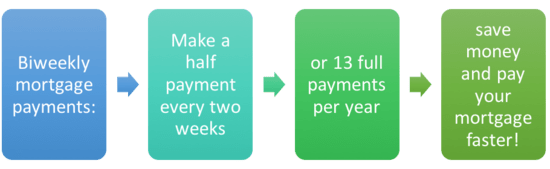
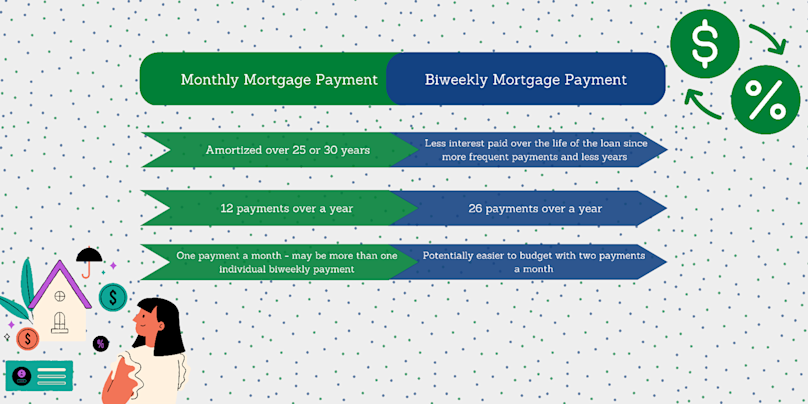
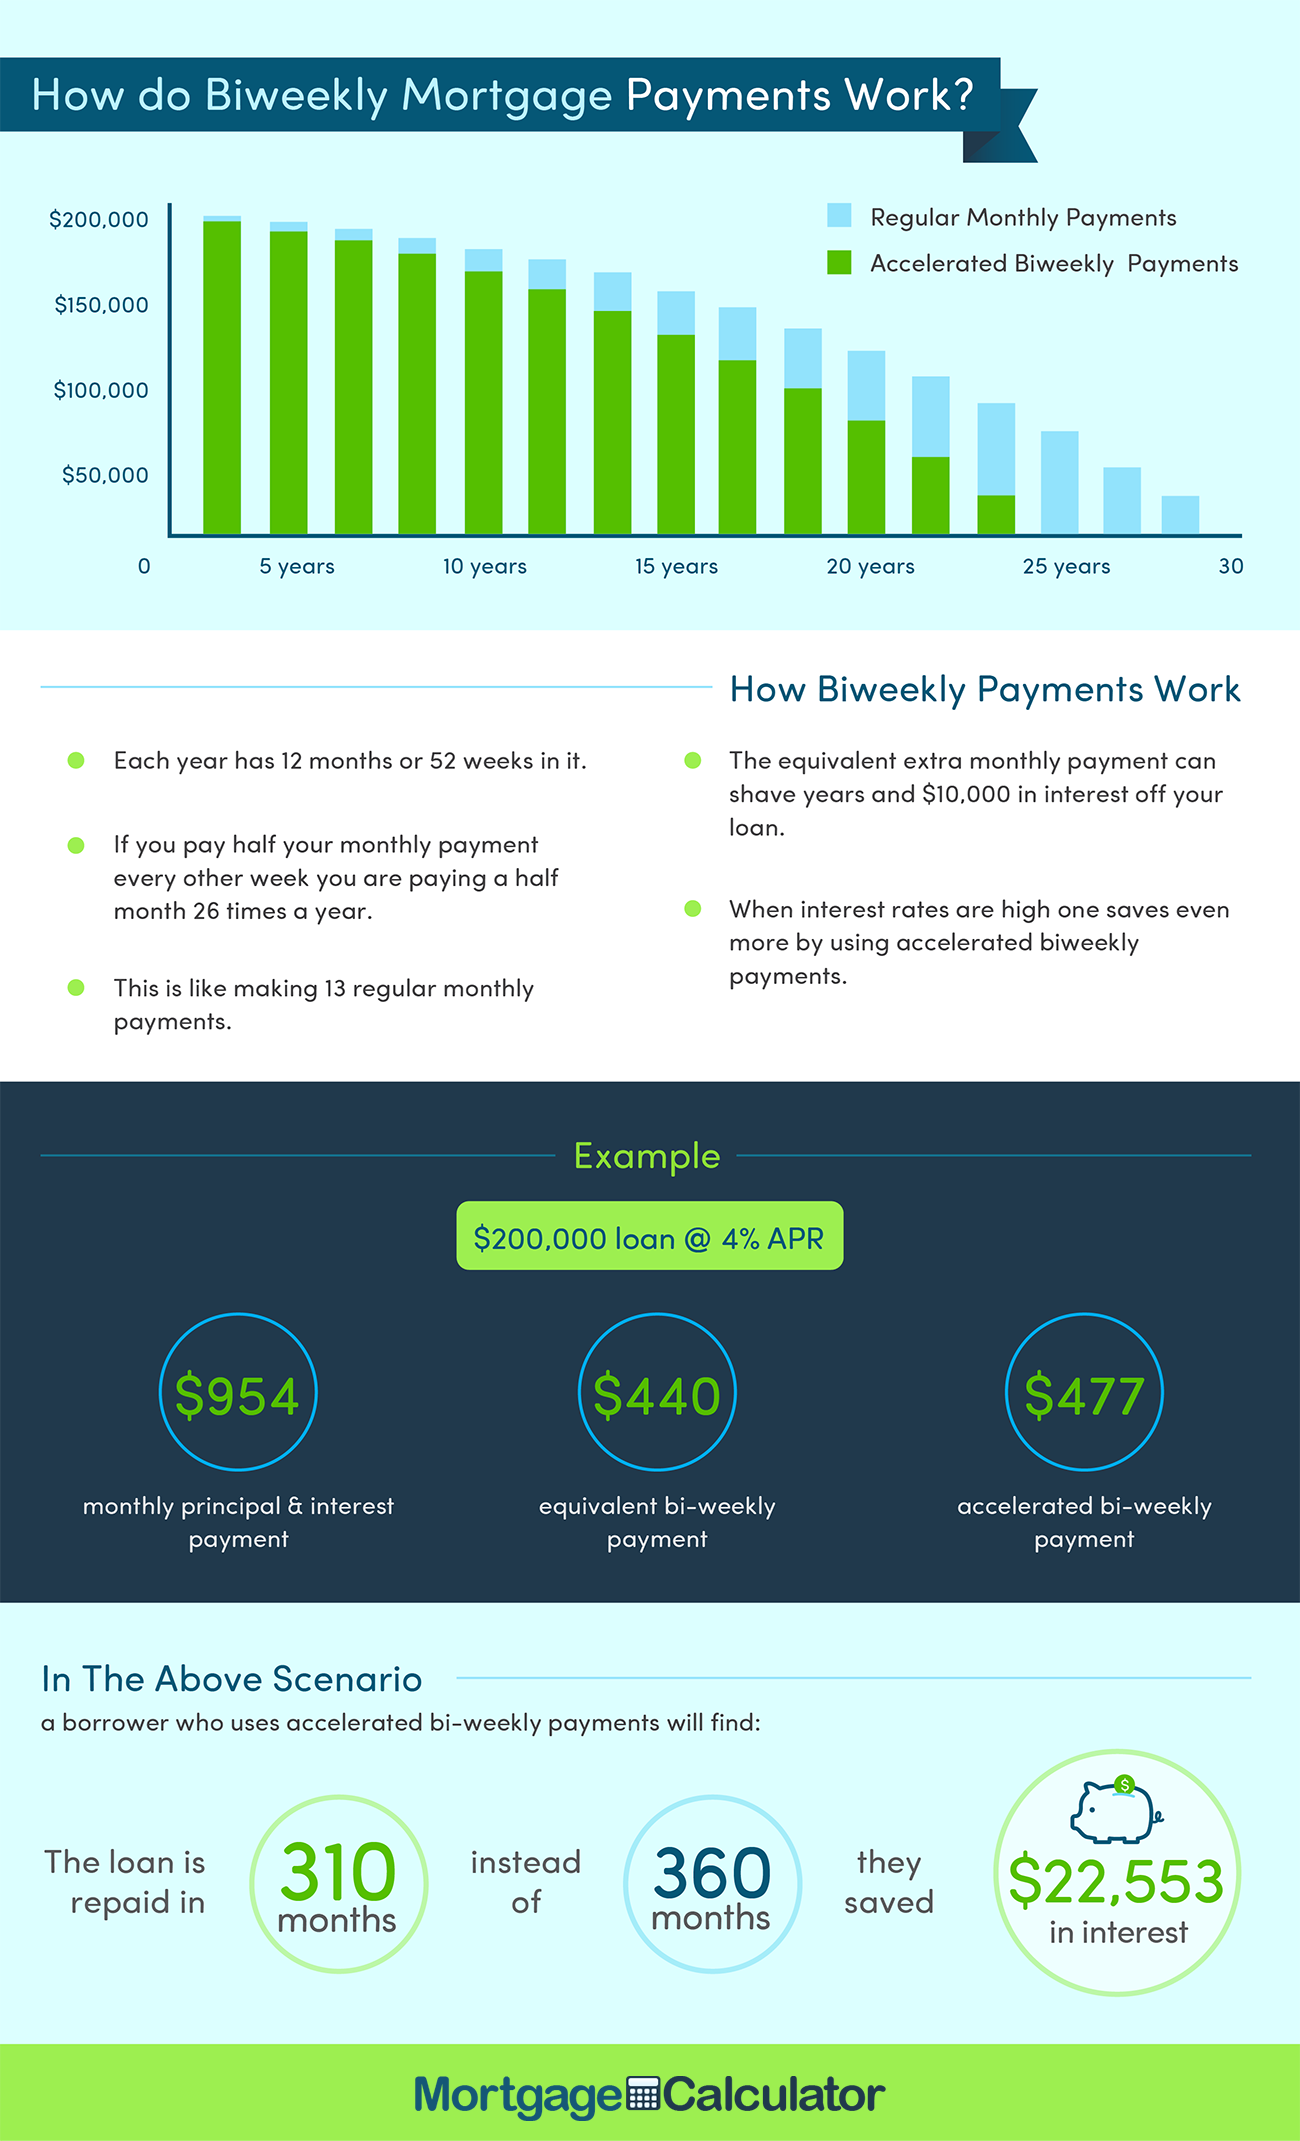
You take whatever your normal monthly payment is, divide it by 26, and pay half of it every two weeks. The math is stupidly simple. Most people mess it up trying to overcomplicate the schedule, but that's not how it's designed. You pay half every fourteen days instead of the full amount once a month. Here's what most calculators won't tell you immediately. Because there are 52 weeks in a year, paying biweekly means you make 26 half-payments, which equals 13 full monthly payments. You're effectively making one extra payment per year without thinking about it. That extra payment goes straight toward principal, which reduces the balance faster, which means less interest accrues over the life of the loan. A standard 30-year mortgage at 6.5% could be paid off roughly four to five years early depending on your terms, and you'd save somewhere between twenty and thirty percent in total interest. The numbers hold up.
The Biweekly Mortgage Reality
I've set up more of these than I can remember for clients, and the thing nobody warns you about is the timing trap. Your servicer might offer an official biweekly program, but the way they apply those payments varies wildly between companies. Some will automatically convert your 26 half-payments into 12 full monthly equivalents and call it a day. Others will actually apply them mid-month and actually recalculate your amortization. If you sign up through your lender's program, read the fine print on how they post the payments. I learned this the hard way with a client in 2019 whose loan was on a legacy servicing platform that treated biweekly payments as a preauthorized draft schedule but still applied them on the original due date each month. She paid 13 equivalent installments over the year and got absolutely zero acceleration benefit because the system never recognized the partial payments as principal reductions. I had to manually recalculate her payoff schedule and submit a written request to her servicer's loss mitigation department to force the proper application. Took six weeks and three phone calls to get it corrected. The workaround was straightforward once I identified the issue. She switched to making her own half-payments on the same calendar date every two weeks and explicitly designated each one as a partial payment toward principal in the memo line. She used a payment portal that accepted variable amounts rather than locking into a fixed installment plan. After the third adjustment, the servicer started applying them correctly and her amortization schedule finally shifted. It cost about $40 in administrative fees for the paperwork changes, but it was worth it. There's a counter-intuitive detail most people miss. A Biweekly Mortgage doesn't always save you money if your loan has a prepayment penalty clause. Some loans, particularly certain jumbo or refinanced mortgages, have built-in restrictions that charge you a percentage of the prepaid amount if you pay off the loan within the first three to five years. The extra biweekly payment could trigger that penalty and wipe out your savings entirely. Check your closing disclosure for any prepayment penalty language before committing. It's usually in section J or buried in the additional disclosures page.
Another detail people overlook: your escrow account doesn't change with a Biweekly Mortgage. Property taxes and insurance are still paid annually or semi-annually from your escrow, and some servicers require you to maintain a certain minimum balance. If your servicer consolidates all your payments into a single escrow-heavy monthly amount, the biweekly schedule might look different on your statement than you expect. The principal portion shrinks temporarily in months when escrow disbursements are large. Important caveat: this strategy assumes you can reliably afford the payment every two weeks. If your income is monthly, you'll need to budget carefully to avoid missing a cycle. Missing one biweekly payment throws off the entire compounding effect for that quarter. The acceleration benefit is marginal if you regularly skip payments or consolidate them retroactively. Some lenders charge a setup fee ranging from $75 to $200 for their automated biweekly programs. Others don't. The fee isn't worth it if you can just set up your own payment schedule through your online portal. You'd be paying for convenience that a calendar reminder and a spreadsheet would handle just as well.
Get the Full Details
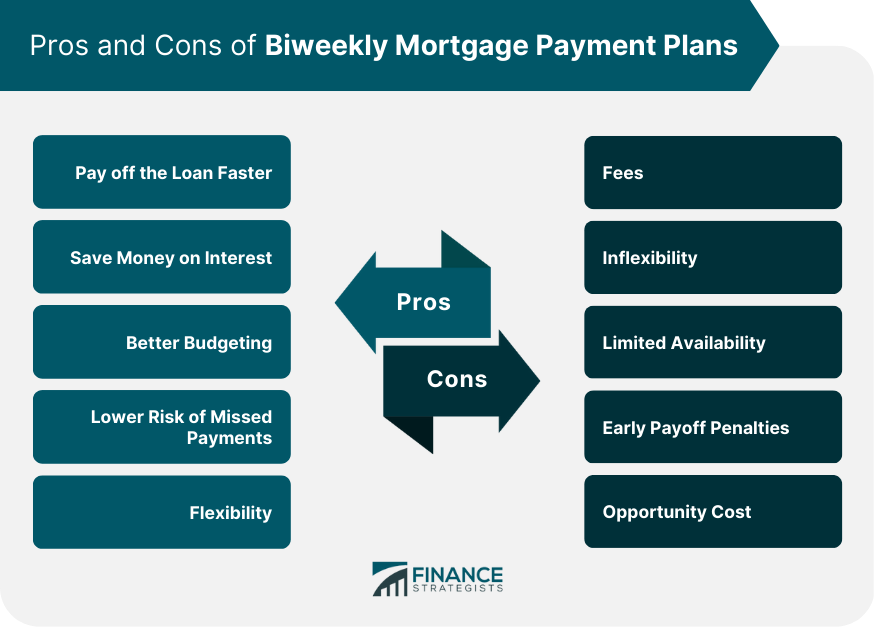
If your servicer is uncooperative about applying partial payments correctly, consider switching loans entirely. A refinance into a standard mortgage with a consciously accelerated payment schedule achieves the same result without the administrative headache. You can pay an extra $100 or $200 per month manually and get identical principal reduction benefits with fewer moving parts. The core advantage of this approach is behavioral, not mathematical. People who commit to a biweekly schedule tend to stick with it because the cadence matches how most people receive paychecks. It removes the decision fatigue of deciding whether to make an extra payment each month. You pay without thinking about it, and the math works in your favor. That said, the difference between a structured Biweekly Mortgage and simply making extra principal payments each month is often negligible once you factor in servicer fees and the administrative overhead of managing a custom payment schedule.