Figuring Out Your Monthly Payment Before You Sign Anything
Most people don't realize how much a boat loan actually costs until they've already committed. The numbers on the sticker don't tell the whole story, and dealerships aren't going to volunteer the details unless you ask for them. That's where doing the math on your own first saves you from walking into a financing meeting blind. A Boat Loan Calculator is just a tool that plugs your loan details into the standard amortization formula and spits out what your monthly payment will be. Simple enough. But the real value isn't in getting the number—it's in understanding which variables move the needle and which ones are noise so you know what to push back on when you're actually talking to a lender.
Boat Loan Calculator: What Actually Goes In
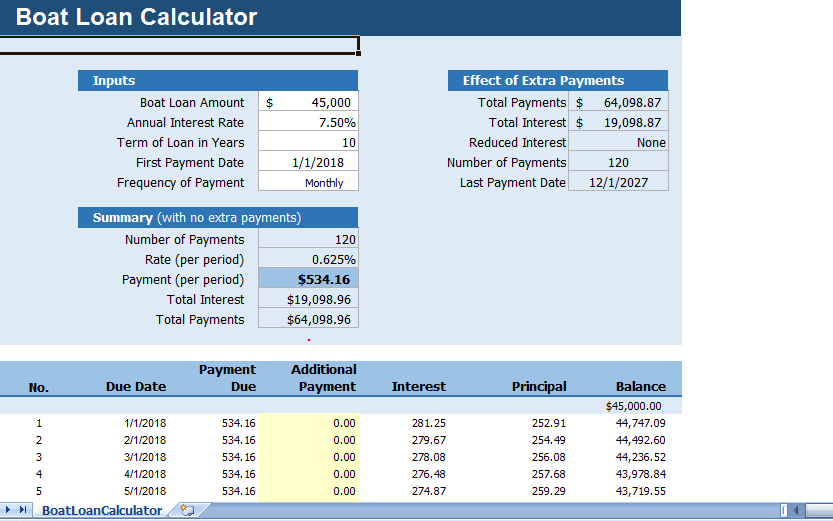
The inputs are fairly standard. You need the purchase price, your down payment amount or percentage, the interest rate the lender quoted, the loan term in years, and ideally the start date so you can see exactly when payments kick in. Some calculators also factor in taxes, registration fees, and shipping costs, but those are often optional because they vary so wildly depending on where you buy and which state you're titling in. I keep it simple. The core calculation only needs five data points: price, down payment, rate, term, and sometimes pre-paid fees if you want a total cash-out number. Everything else gets added manually at the end if you need to budget around it. Here's the formula behind it, in case you ever want to verify what a calculator is doing or build your own: the monthly payment equals the loan amount multiplied by the monthly interest rate, divided by one minus one over one plus the monthly rate raised to the power of the total number of payments. The loan amount is just the price minus your down payment. The monthly rate is your annual percentage rate divided by twelve. The total number of payments is your loan term in years multiplied by twelve. That's it. No magic.
How to Actually Use One
Find a calculator that lets you enter custom values rather than just picking from a dropdown menu of boat prices. Some online tools lock you into preset categories that don't match what you're actually looking at. You want one where you can type in your exact numbers. I run through it like this. First I plug in the listed price. Then I subtract the down payment—I usually budget ten to fifteen percent depending on whether I'm buying new or used. Next comes the interest rate, and this is where most people get burned. The rate printed on the ad isn't always the rate you qualify for. I always run the calculator at least twice: once at the advertised rate and once at the rate the lender actually offered me after a soft pull. The difference between those two scenarios can change your monthly payment by a hundred dollars or more on a larger loan. After that, I select the term. Twelve years is common for new boats, but six to eight years is where a lot of people land if they're trying to keep payments manageable. I always check what happens at each interval because the total interest paid jumps non-linearly as the term extends. Going from seven to ten years might seem like it only adds three years of payments, but the interest cost over that loan's life can balloon in a way that's easy to gloss over if you're only looking at the monthly number.
Get the Full Details
One Specific Problem I Ran Into
A few years ago I was looking at a used vessel with an existing loan that had a balloon payment baked into the terms. The seller's figure looked reasonable on the surface, but when I put it into a standard Boat Loan Calculator, the numbers didn't align with what the lender was quoting. Turns out the interest was compounded semi-annually instead of monthly, which is common in Canadian-style financing and some smaller credit unions. A standard calculator assuming monthly compounding gave me a payment that was roughly four dollars off per month. It sounds small, but over the life of a six-year loan on a forty-thousand-dollar balance, that added up to about two hundred and fifty dollars in underpaid principal, which then cascaded into a slightly higher payoff at the end. The workaround was straightforward. I found a calculator that allowed me to specify the compounding frequency and adjusted the annual rate to its equivalent monthly compounded rate before running the numbers. If your calculator doesn't have that option, you can approximate it by dividing the annual rate by twelve and rounding to four decimal places, though it won't be exact. Better yet, just ask the lender for the amortization schedule upfront. It takes them thirty seconds to generate, and it saves you from guessing.
Things Calculators Won't Tell You
Most free Boat Loan Calculator tools on the web give you a clean monthly payment number and a total interest figure, and that's where their usefulness ends. They don't account for the fact that boat insurance premiums change based on loan-to-value ratios, which lenders determine from your down payment. A smaller down payment means a higher loan-to-value ratio, which some insurers interpret as higher risk and price accordingly. I've seen insurance quotes shift by three hundred dollars a year between a ten percent and a twenty percent down payment on the same vessel. Another thing that rarely shows up in the output: prepayment penalties. Some marine lenders structure loans with clauses that charge you a fee if you pay off the loan early or refinance within a certain window, usually the first two to three years. A calculator won't factor that in because it's specific to the contract. You need to read the fine print. I learned this the hard way when I refinanced a loan after eighteen months and got hit with a three-percent prepayment penalty on the remaining balance. It wasn't disclosed prominently during the original application. There's also the matter of floating-rate versus fixed-rate loans. Most boat loans are fixed, but some lenders, particularly credit unions, offer variable rates that can adjust annually. A calculator will show you a static number based on the current rate, but if the rate moves up even a half percent after two years, your payment changes and the calculator doesn't reflect that shift unless you're running multiple scenarios yourself.
When a Calculator Is the Wrong Tool
If you're dealing with a very large loan—say above one hundred and fifty thousand dollars—the standard amortization model breaks down a bit because lenders often structure these as interest-only periods for the first few years before switching to principal and interest. Running those numbers through a regular calculator gives you incorrect results. In that case, you need the lender to provide a custom amortization schedule, or you can use a commercial loan calculator designed for marine financing with adjustable payment structures. Similarly, if you're buying through a manufacturer's promotional financing program with a deferred interest period, the math gets messy. The calculator will show you zero payments for the promotional window and then a jump, but it won't tell you whether deferred interest accrues or gets forgiven if you pay in full during the promotional period. That's a contract-specific detail you have to confirm with the lender directly. I've seen people assume deferred interest was waived when it wasn't, and they owed a lump sum of back interest at the end of the promotion.

Quick Example
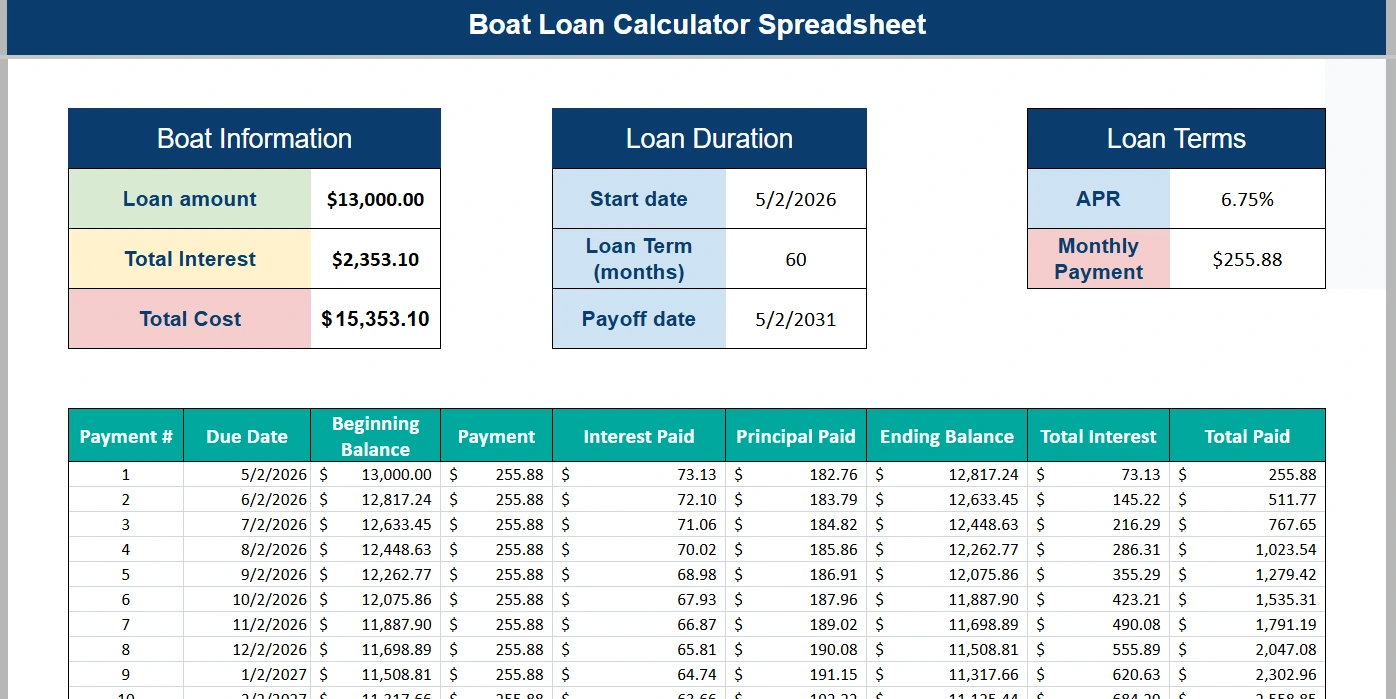
Say you're looking at a thirty-five thousand dollar fishing boat. You put down eight thousand, leaving a loan amount of twenty-seven thousand. The lender quotes you six-point-five percent annual interest over eight years. Plugging those numbers in gives you a monthly payment of roughly three hundred sixty-two dollars. Total interest over the life of the loan comes to about six thousand one hundred dollars, making the total cost of the loan twenty-three thousand one hundred dollars in payments plus the eight thousand down, or thirty-one thousand one hundred dollars out of pocket before taxes and fees. If you drop the term to six years instead, your payment climbs to about four hundred fifty-two dollars, but total interest drops to roughly four thousand two hundred dollars. You pay about nine hundred dollars more per month but save nearly two thousand in interest. That tradeoff is worth thinking about before you pick a term based solely on what feels comfortable month to month. The same boat at a seven-year term lands somewhere in the middle, which is why I always run three scenarios before I stop at one. It takes about ninety seconds on most calculators and prevents you from locking into a term that looks fine today but costs significantly more over time.