Why Most Break Even Templates Fail Before You Actually Use Them
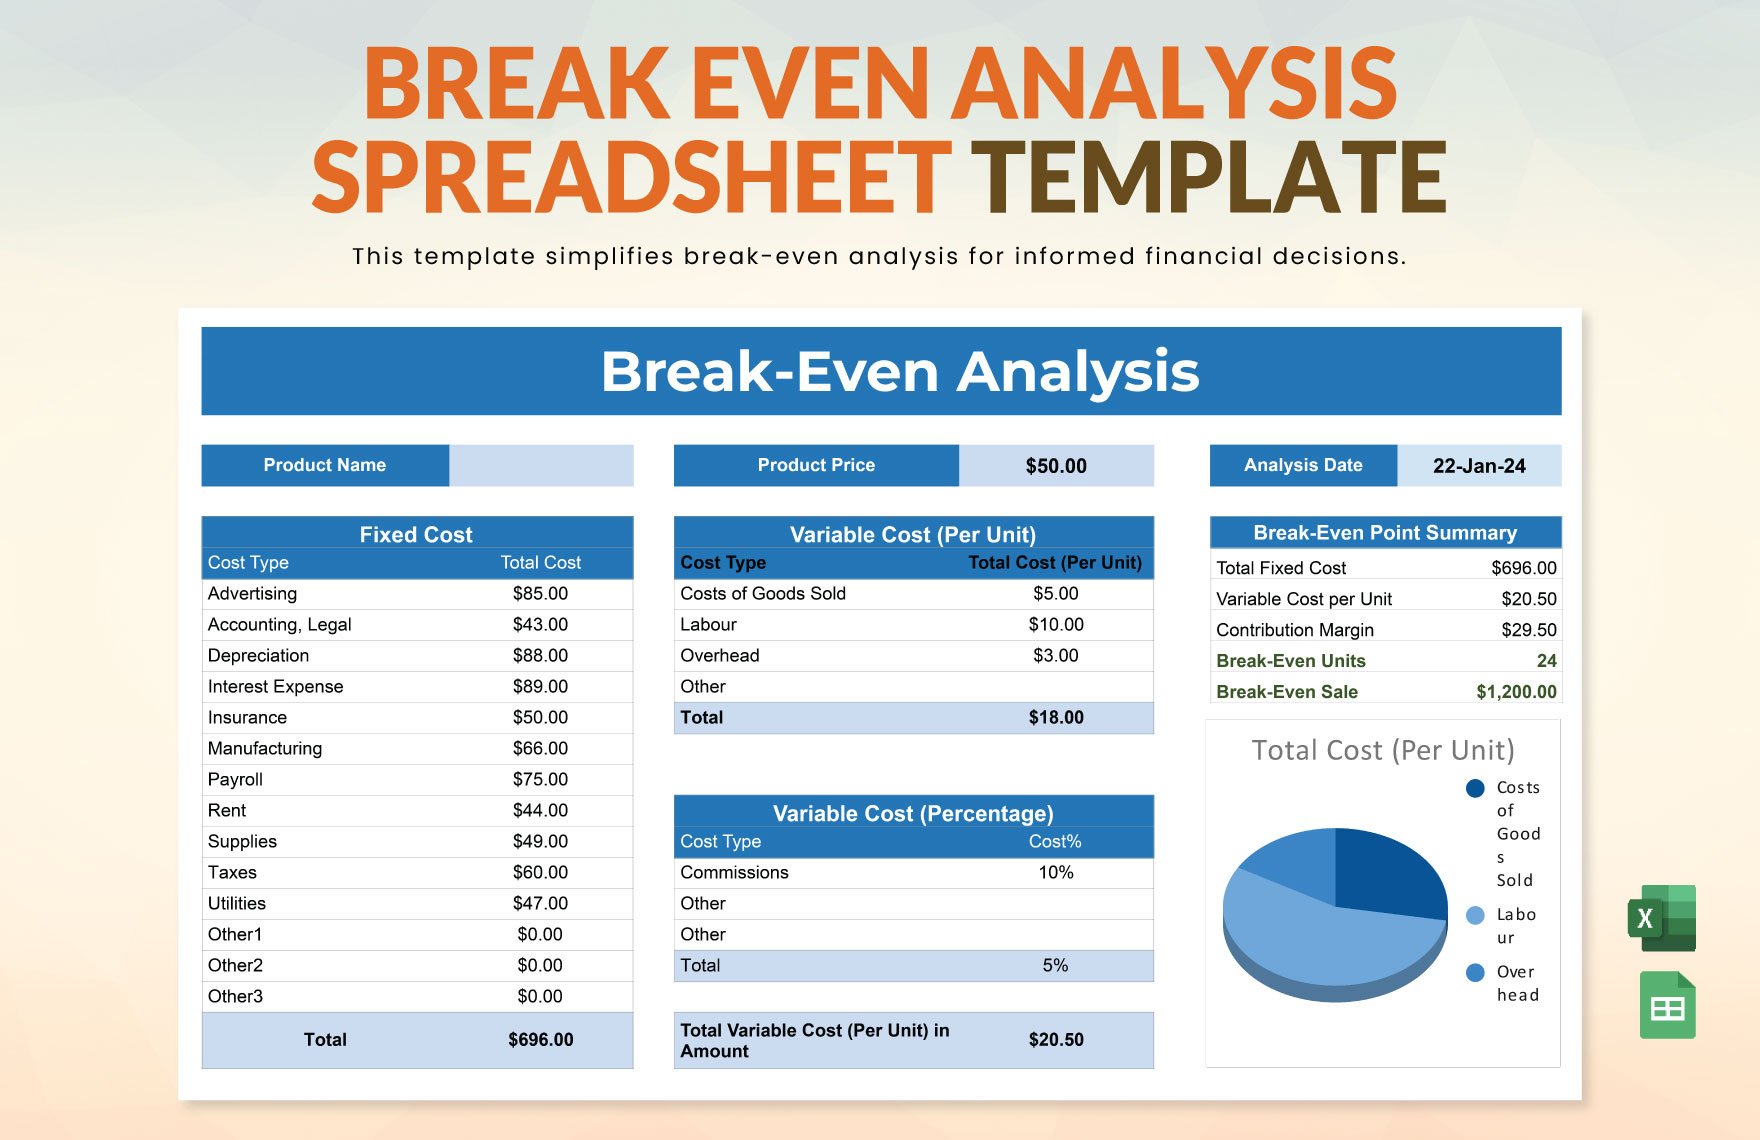
I built my first break even calculator in 2018 for a small manufacturing client. It was supposed to be a quick setup job. Three weeks later, after I'd rewritten the sheet twice, the client called and said their actual break even point was nowhere near what the model predicted. The problem wasn't the formula. It was that the template treated every cost as either fully fixed or fully variable. That doesn't exist in the real world. Everything has a knee point. Break Even Analysis Template Google Sheets works fine if you understand what it's actually measuring. It's a single-input model. You feed it fixed costs, variable cost per unit, and selling price per unit. It outputs a quantity. That's it. Simple in theory. Painful in execution because nobody ever asks the right questions about how those inputs behave at different volumes.
Break Even Analysis Template Google Sheets — What You Actually Need to Build
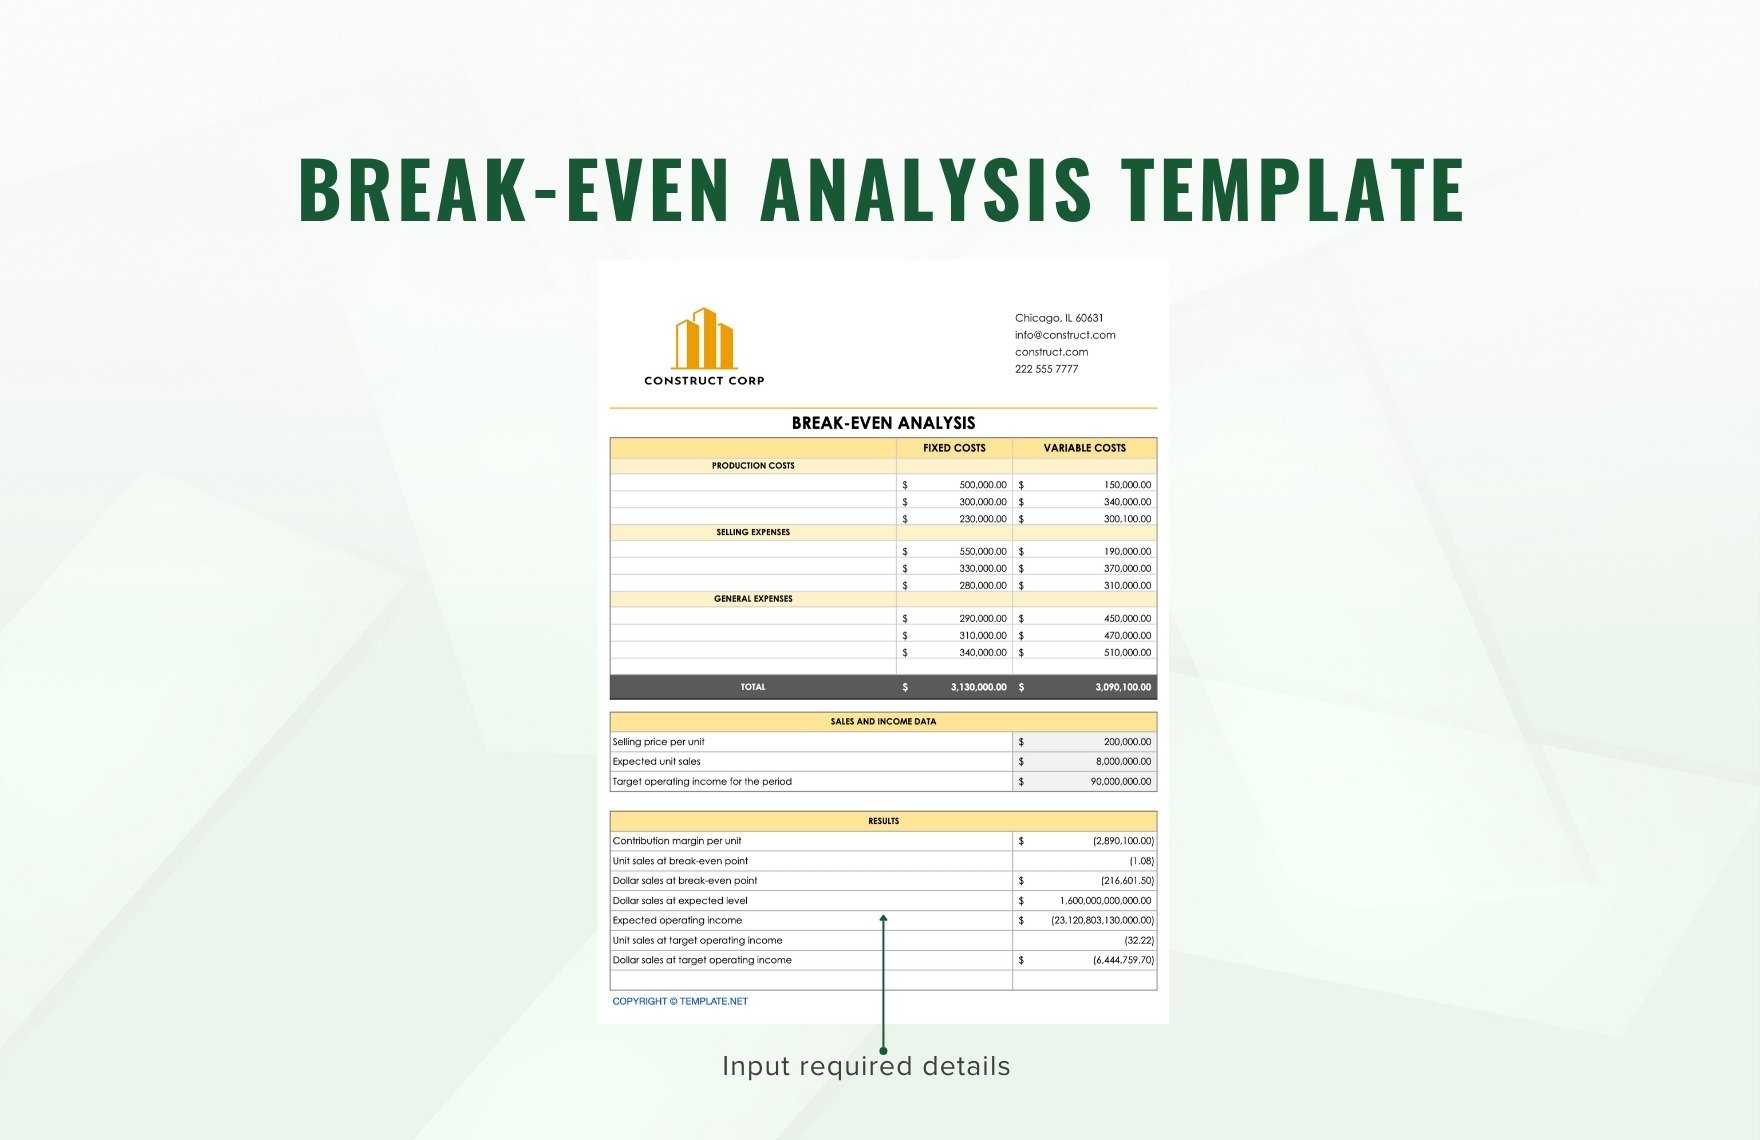
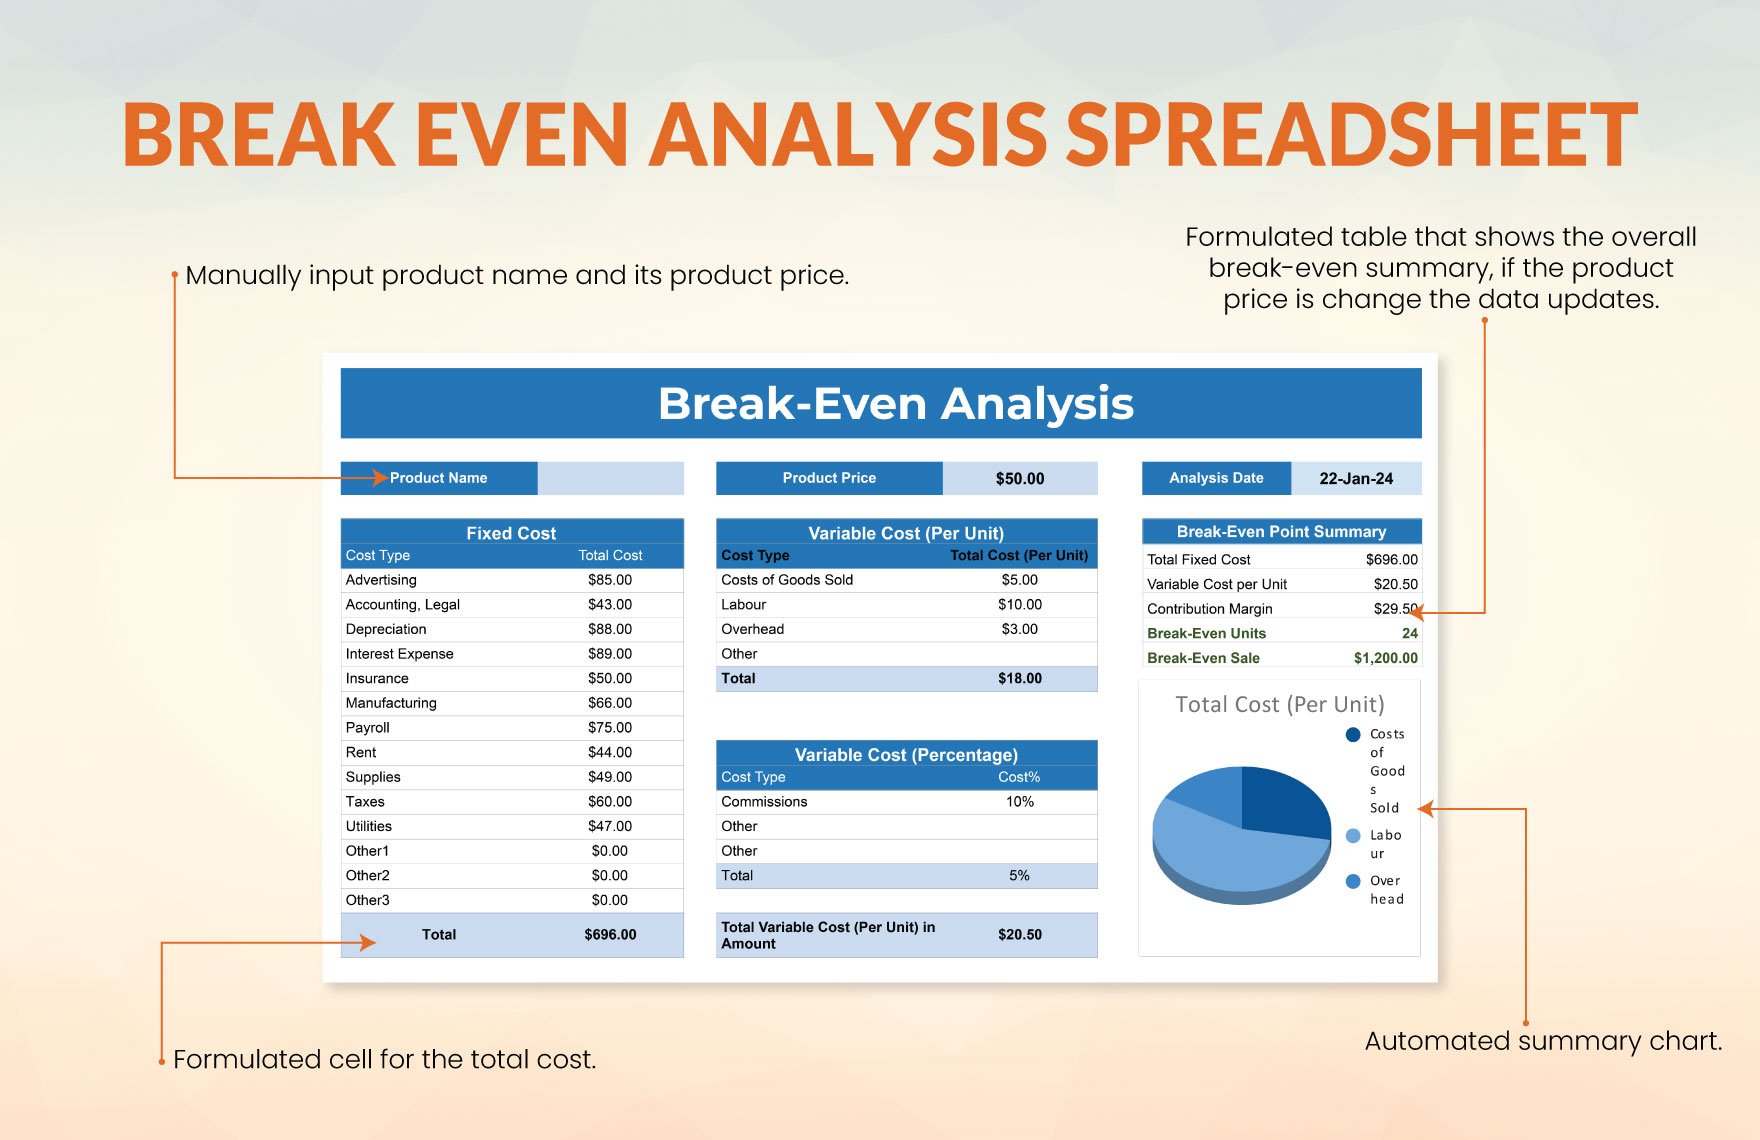
Start with a clean input section at the top. Fixed costs in one column. Variable cost per unit in another. Price per unit in a third. Three cells. That's all that matters for the core calculation. Below that, a single formula: Breakeven Quantity = Fixed Costs ÷ (Price Per Unit Variable Cost Per Unit) In Google Sheets that's just =B2/(B3-B4) where B2 is fixed costs, B3 is price, and B4 is variable cost. Nothing fancy. But here's what most people skip: sensitivity analysis. You should add a data table that shows the break even quantity across a range of prices. This takes about five minutes to set up and saves you from presenting a single number that falls apart the moment any assumption shifts.
The Problem Nobody Warns You About
Last year I was helping a restaurant owner model her break even. She had $12,000 in monthly fixed costs, ingredient costs around 35% of sales, and an average check of $28. The template said she needed roughly 1,450 covers per month to break even. That's about 48 covers per day. Sounds manageable, right? But the template didn't account for the fact that her ingredient costs weren't a flat 35% at every volume level. At lower volumes, she was ordering in smaller quantities and paying higher unit prices for perishables. The effective variable cost was closer to 42% when she was below 60% capacity. That shifted her real break even to over 1,900 covers. She'd been operating under a false sense of security for three months because the template treated variable cost as a static percentage instead of a function of volume. The workaround was straightforward. I built a lookup table that adjusted the variable cost percentage based on projected monthly revenue tiers. Not elegant. Not textbook. It just worked better than the standard formula.
Get the Full Details
What the Template Misses
A standard break even analysis assumes a linear relationship between costs and revenue. That assumption breaks down almost immediately in practice. Here are the specific failure modes I've encountered: Tiered fixed costs. Your rent might stay flat, but your insurance jumps when you cross a certain revenue threshold. Your equipment lease kicks in at a certain production volume. These aren't variable costs. They're step functions. A basic template won't capture them. You need either a piecewise calculation or multiple break even points mapped across different capacity ranges. Mixed cost components. Labor is the classic example. A small team stays fixed through normal hours. Overtime hits past a certain threshold. Part-time staff get added when volume demands it. Each of these represents a different cost slope. The break even point moves depending on where you are on the staffing curve.
Price-volume tradeoffs. The template gives you a single price assumption. But in practice, lowering your price by even a small amount can shift demand enough to change the entire picture. Running a what-if on price elasticity usually reveals that the break even quantity is less useful than understanding the contribution margin at different price points.
Building a More Honest Model in Google Sheets
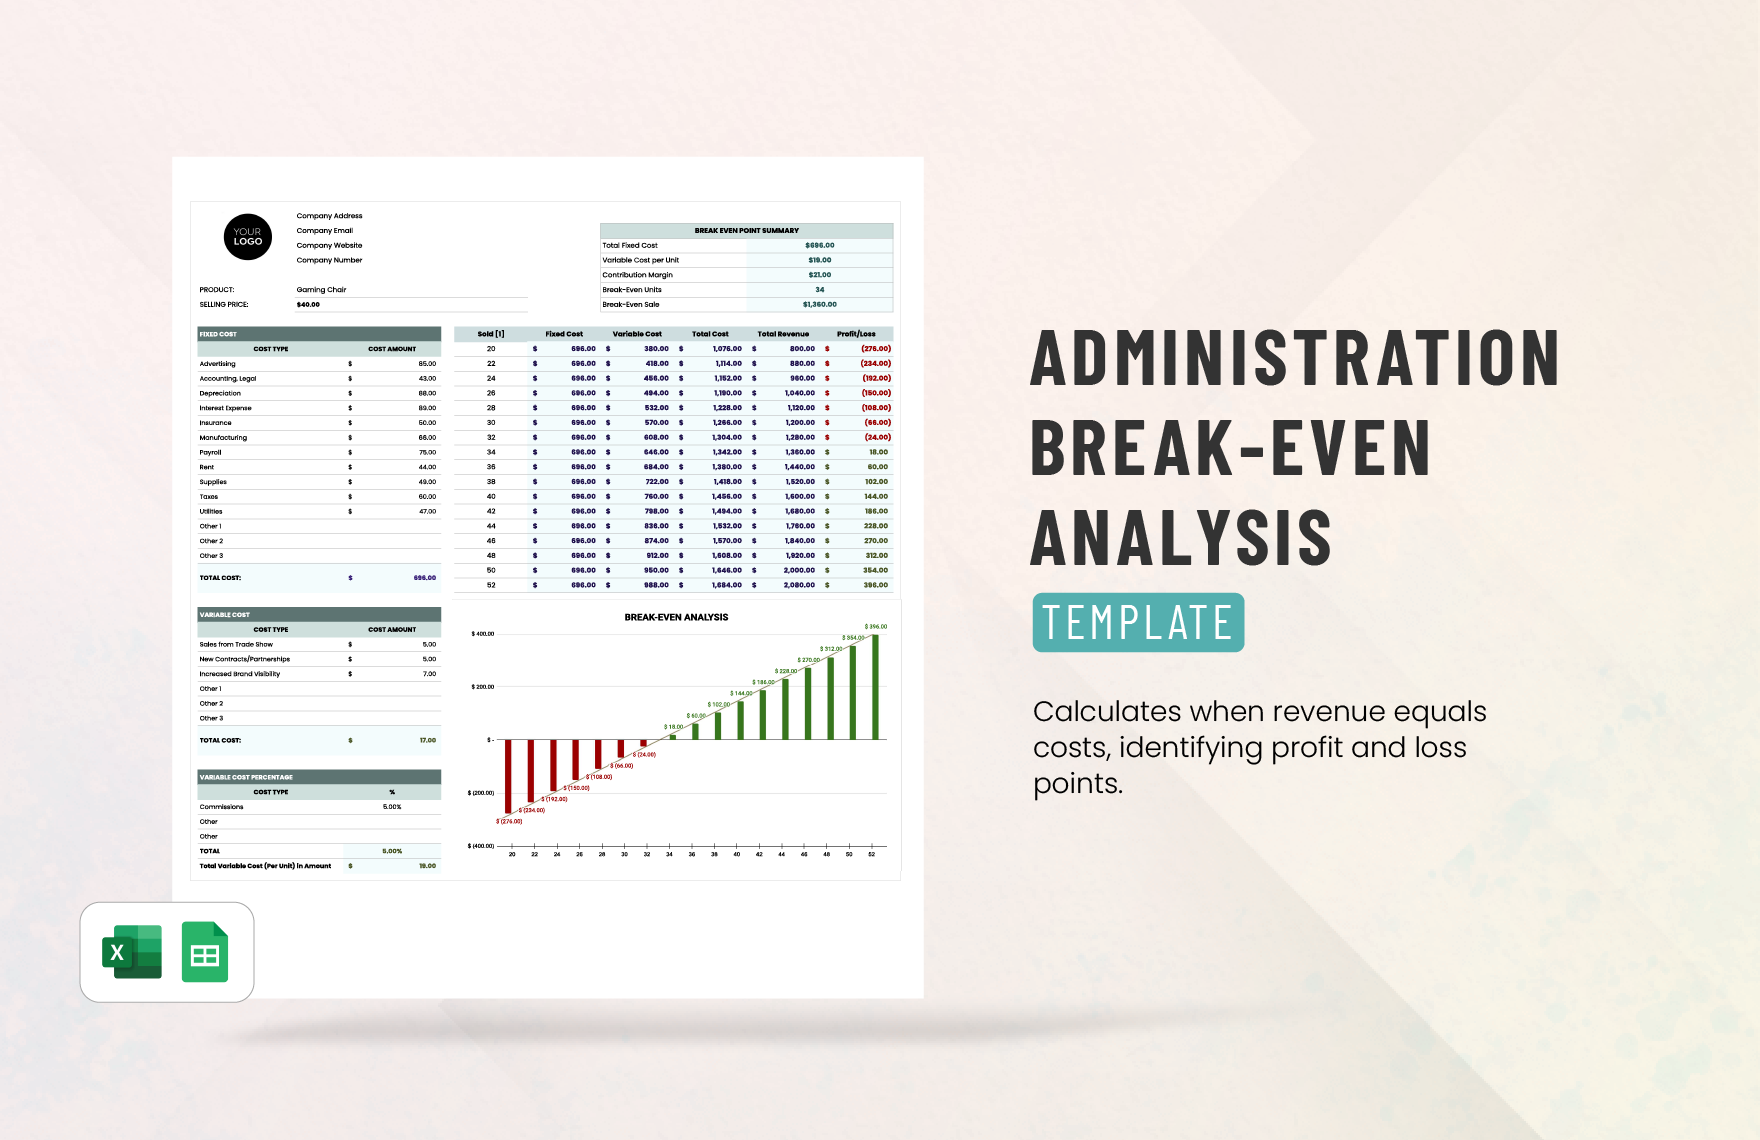
Instead of one formula, structure your sheet around contribution margin per unit. That's simply Price minus Variable Cost per Unit. Then divide Fixed Costs by that contribution margin. Same result, but now you can layer in additional rows for different scenarios without rewriting formulas. Add a section that calculates total revenue and total cost across a range of output levels. Use the sequence function or a simple fill-down to generate quantities from zero to whatever maximum makes sense for your business. Total Revenue = Quantity × Price. Total Cost = Fixed Costs + (Quantity × Variable Cost Per Unit). Then plot both lines on a chart. The intersection is your break even point. Having it visualized makes it much harder to misinterpret the numbers. For the tiered cost issue, use IF statements or a VLOOKUP against a cost-bracket table. Something like this structure: if quantity is below 500 units, variable cost per unit is X. If between 500 and 1000, it's Y. If above 1000, it's Z. Each bracket gets its own break even calculation. The real break even is whichever bracket contains the actual output level.

When the Template Is Actually Useful
Don't throw it out entirely. It's useful as a first-pass estimate. If you're evaluating whether a new product line is worth exploring, a quick break even model tells you whether you're in the right neighborhood. It catches catastrophic assumptions before you invest real time in a detailed financial model. I'd say 80% of the businesses that approach me with break even questions would have avoided the problem entirely if they'd run a quick template check first. The template also works reasonably well for service businesses with minimal variable costs. A consulting firm or a software subscription business where the main variable cost is hosting or payment processing fees. In those cases, the variable cost truly is nearly constant per unit, and the linear assumption holds up fine.
Limitations You Need to Accept
A break even analysis tells you nothing about profit. It tells you the point where profit equals zero. Beyond that point, every additional unit sold contributes its full contribution margin to profit, but the model doesn't tell you whether the market can absorb that volume. It also ignores time value of money, which matters if you're evaluating a capital-intensive project where fixed costs are front-loaded. A traditional break even point calculated in units means nothing if it takes eighteen months to reach and the equipment depreciates significantly in that window. If you're making a serious investment decision, move to a discounted cash flow model. The break even template is a screening tool, not a decision tool. Using it as the latter is how you end up with that restaurant owner thinking she had a viable business when she actually needed twice the volume she was projecting. For most small business owners working in Google Sheets, a well-structured Break Even Analysis Template Google Sheets with sensitivity tables and stepped cost brackets will give you enough signal to make reasonable decisions. Just don't mistake the output for precision. It's a map, not the territory.