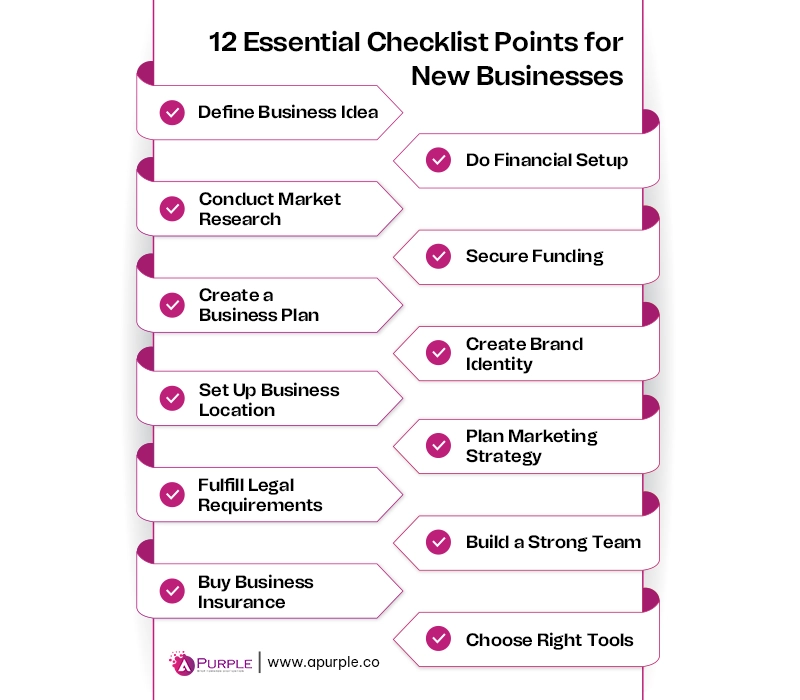
Getting Your First Business Off the Ground Without Losing Your Mind
I spent three weeks in 2019 trying to launch a consulting side-business and discovered I had no idea what I didn't know. My first "checklist" was a Notes app entry that listed things like "get a website" and "figuring out taxes." That was about as useful as telling someone to drive from New York to Chicago by just going west. I ended up booking the wrong business entity type, missing a local permit, and launching with a bank account that couldn't accept ACH payments because I hadn't verified my EIN yet. The whole mess cost me about eight weeks of lost time and roughly $400 in corrected filings. The reason I'm sharing this is that most Business Launch Checklist templates you'll find online are written by people who have never actually done it. They tell you to "create a vision" and "set SMART goals" but skip the part where you discover you need a separate employer identification number before you can open a business checking account, or that your local zoning laws might prevent you from running inventory out of your garage. The gap between those two steps is where most first-time founders get stuck.
Why a Business Launch Checklist Actually Matters (Most People Skip This Part)
Here's a counter-intuitive thing about launching: the order in which you do things matters more than the speed at which you do them. I watched two friends launch nearly identical businesses in the same month. One filed their LLC first, got their EIN, then set up banking. The other did branding and a website before forming any legal entity. The second friend ended up signing vendor contracts under their personal name for six weeks because they couldn't prove the business existed. That's not a speed problem. It's an ordering problem. A proper checklist forces you to confront dependencies. You can't get a business license without a registered entity in most jurisdictions. You can't open a business credit line without a business license and EIN. You can't invoice clients professionally without a business bank account. These aren't suggestions. They are hard dependencies that legal and financial institutions will check before helping you.
The Pre-Launch Phase: Legal and Financial Foundations
Start with the entity structure. This isn't about choosing between LLC, S-Corp, or C-Corp based on some vague notion of what's best. It's about matching your actual situation to a real structure. If you're a solo founder with no plans to bring in investors or issue stock options, an LLC is almost always the right call. It's simpler, cheaper to maintain, and the pass-through taxation means you avoid the double taxation that eats into C-Corp profits. If you're planning to raise venture capital, the calculus changes entirely. But most people asking for a Business Launch Checklist aren't building the next Airbnb. Register your business name through your state's Secretary of State portal. This usually takes one to three business days and costs between $50 and $150 depending on where you live. Do not skip the trademark search at uspto.gov. I learned about this the hard way when a client nearly launched a brand called "Meridian Works" only to discover a registered trademark in a adjacent industry that gave them cease-and-desist rights. The search takes twenty minutes. The lawsuit would have cost twenty thousand. Get your Employer Identification Number from the IRS. This is free, instant if you apply online, and absolutely required before anything else financial. You cannot open a business bank account without it. You cannot file business taxes without it. You cannot hire employees without it. The application takes about ten minutes at irs.gov and the number is issued immediately upon completion. Some people try to use their Social Security Number instead. Don't. Mixing personal and business tax identification creates a compliance nightmare that no accountant wants to fix for you.
Get the Full Details
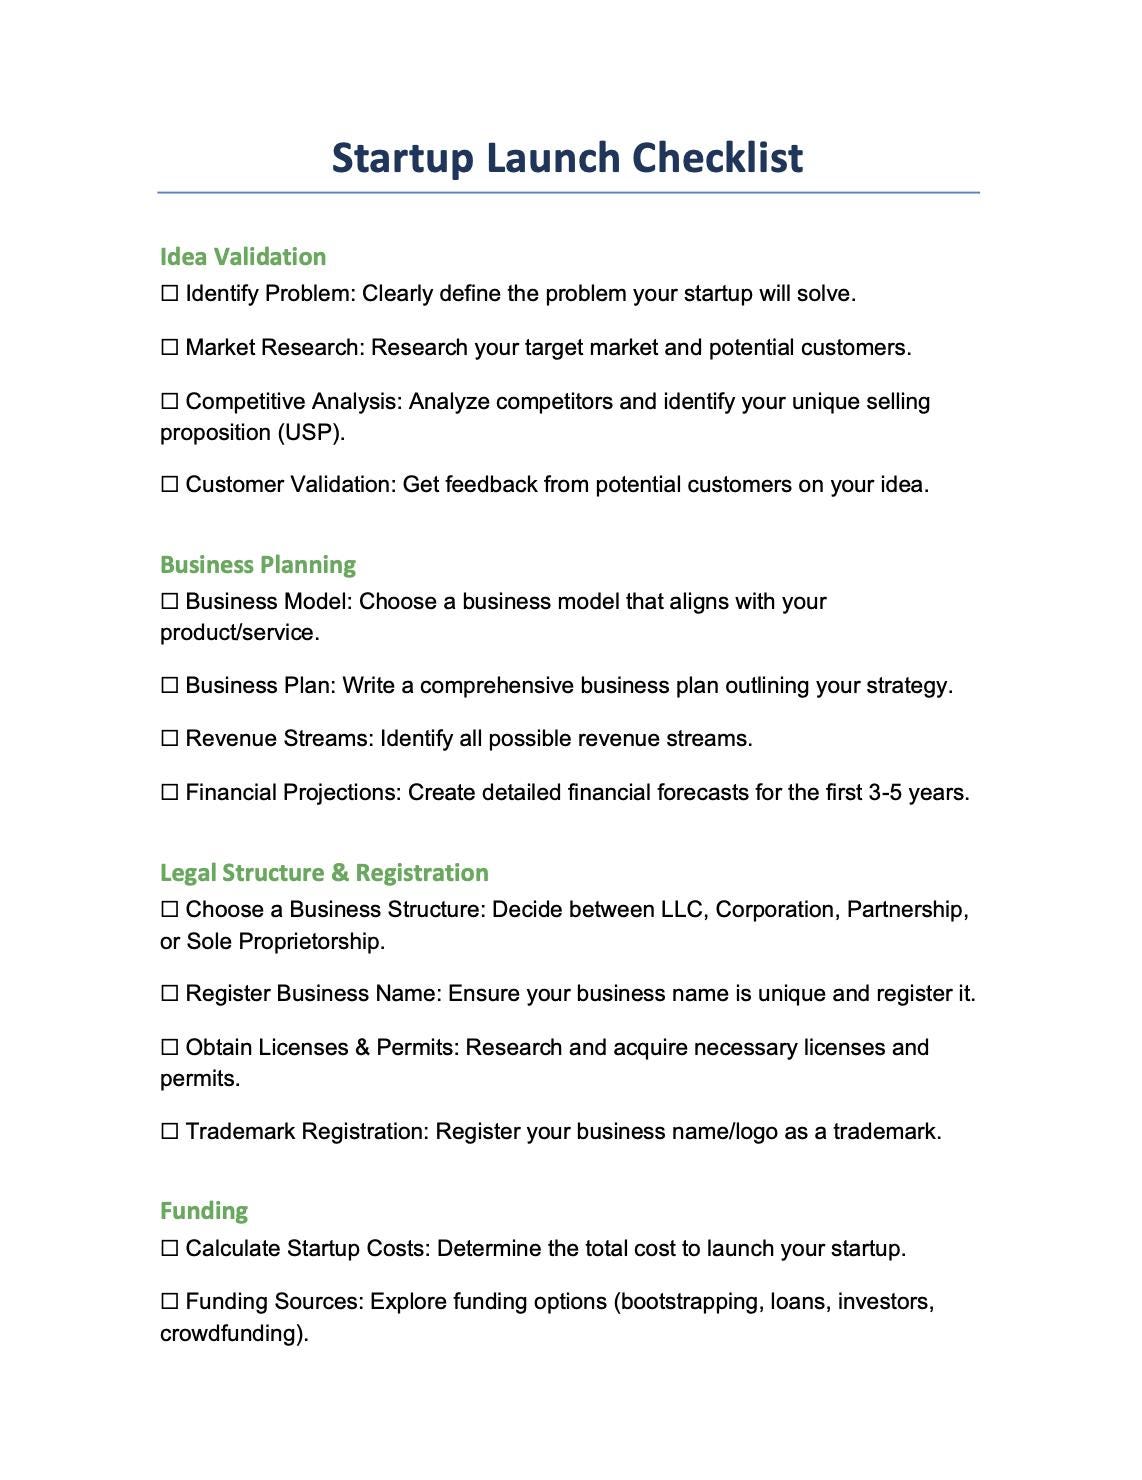
Open a business bank account. Take your EIN, your formation documents, and your personal ID to a bank that offers business checking with no minimum balance. I recommend a local credit union or a regional bank over a national chain for this step. The relationship matters more than the branch count when you eventually need to explain why your revenue patterns look unusual. National banks automate these conversations away. Credit unions put you in front of a human who understands your context.
Compliance and Permits: The Boring Stuff That Will Save You
This is where my personal edge-case comes in. I was launching a small e-commerce business selling handmade goods and assumed I only needed a general business license. Wrong. My city required a specific home occupation permit because I was storing inventory in my garage and shipping from my residence. The permit process took six weeks, required a zoning inspection, and cost $200. I missed it during my initial launch and had to halt operations for two months while I corrected the paperwork. The workaround? Before you incorporate, call your city clerk's office and ask specifically about home-based business requirements. The question should be: "I plan to operate a business from my residence at [address]. What permits and zoning approvals do I need?" Write down their answer. Call them back in three months to confirm nothing changed. Beyond that specific issue, most businesses need at least these items: a general business license from your city or county, a sales tax permit if you're selling physical goods, and potentially a professional license depending on your industry. Food businesses need health department approval. Childcare needs state licensing. Consulting is relatively straightforward by comparison. Check your state's small business administration page and your city's licensing portal. These resources exist and they're usually accurate. Don't forget insurance. General liability insurance costs roughly $500 to $1,500 annually for a small service business. Product liability runs higher if you're selling physical goods. I carried zero insurance for the first four months of my consulting business and operated on the assumption that nothing bad would happen. That's not optimism. That's gambling with your personal assets. If a client sues you and you don't have an LLC protecting your personal wealth, they come after your house. The insurance premium is not discretionary spending. It's the price of sleeping at night.
Financial Infrastructure: Setting Up Properly From Day One
Bookkeeping is the most overlooked component of any Business Launch Checklist. I've seen founders who can close a $50,000 deal in an hour but can't reconcile their bank statement at the end of the month. The result is always the same: a chaotic tax season, missed deductible expenses, and often an IRS notice that could have been avoided with fifteen minutes of weekly bookkeeping. Set up your bookkeeping system before you receive your first dollar. QuickBooks Online, Xero, or even a well-structured spreadsheet will work for early-stage businesses. The key is consistency. Pick one system, link your business bank account to it, and categorize every transaction within forty-eight hours of it occurring. This habit reduces your end-of-year accounting preparation from approximately thirty hours to maybe four hours. The difference between those two numbers is the difference between a smooth tax filing and a frantic December experience involving your accountant's emergency rates. Get a business credit card. This separates business expenses from personal ones, which simplifies bookkeeping and provides a layer of liability protection. I use a capital one business platinum card for travel and software subscriptions. The rewards are incidental. The separation is the point. When your accountant asks for expense documentation during tax season, having everything in one place matters more than any cashback percentage.

Understand your tax obligations. Self-employment tax is 15.3 percent on your net earnings, broken into Social Security and Medicare. Most people don't realize they need to make quarterly estimated tax payments. The penalties for missing them compound quickly. Set up an automatic transfer from your business checking to a separate savings account each month that covers roughly 25 to 30 percent of your expected net income. When April arrives, you already have the money sitting there waiting for you. This simple mechanism has prevented more tax problems than any sophisticated strategy I've encountered.
Operations and Customer-Facing Infrastructure
Your website doesn't need to be perfect. It needs to communicate what you do, how people can pay you, and how they can contact you. I launched my first business with a single-page Squarespace site that took me four hours to build. It had a hero section describing my services, a contact form, and a pricing table. That was enough. Perfectionism in web design is a procrastination strategy disguised as quality control. The website will evolve. It always does. Build the minimum viable version and iterate based on actual user behavior, not imagined objections. Payment processing is another area where ordering matters. Set up your payment infrastructure before you start accepting money. Stripe, Square, or PayPal each have different tradeoffs. Stripe integrates better with custom workflows. Square is simpler for in-person transactions. PayPal has the widest customer recognition but higher dispute rates. For a typical service business, I'd recommend Stripe for online payments and Square for any face-to-face interactions. The setup time is roughly two to four hours depending on your technical comfort level. Contracts. Every engagement needs a written agreement. I used to operate on handshake deals and invoices. That ended when a client refused to pay a $3,000 project and cited vague scope expectations. A basic service agreement covering scope, payment terms, revision limits, and IP ownership prevents these situations entirely. Draft your own using resources from Rocket Lawyer or LegalZoom, then have a local business attorney review it once. The review costs about $300 to $500 and will save you tens of thousands in potential disputes. That is not hyperbole. That is the arithmetic of my own experience.
The Launch Window: What Actually Happens on Day One
Day one is not a dramatic announcement. It's a quiet process of making sure everything you've built actually works. Test your payment flow end-to-end. Buy something from yourself with a $1 item to confirm the money moves correctly. Send a test invoice and verify the client receives it. Check that your contact form delivers messages to your inbox. These five-minute tests prevent twenty-hour debugging sessions later. Set up your analytics before you need them. Google Analytics 4 takes about ten minutes to configure. Having visitor data from day one gives you baseline information that you cannot recreate later. If you wait until you have traffic to set it up, you'll never know whether your growth is genuine or just seasonal fluctuation. The data you collect now becomes your reference point for future decisions. Announce your launch through the channels your potential customers actually use. LinkedIn for B2B services. Instagram or TikTok for consumer products. Local Facebook groups for community-based businesses. I wasted $800 on Facebook ads in my first launch because I assumed a broad demographic target would work. It didn't. I refined my targeting to a specific professional niche and spent $200 the second time with four times the conversion rate. The lesson: spend your marketing budget after you understand your audience, not before.
Post-Launch: Maintenance and Growth
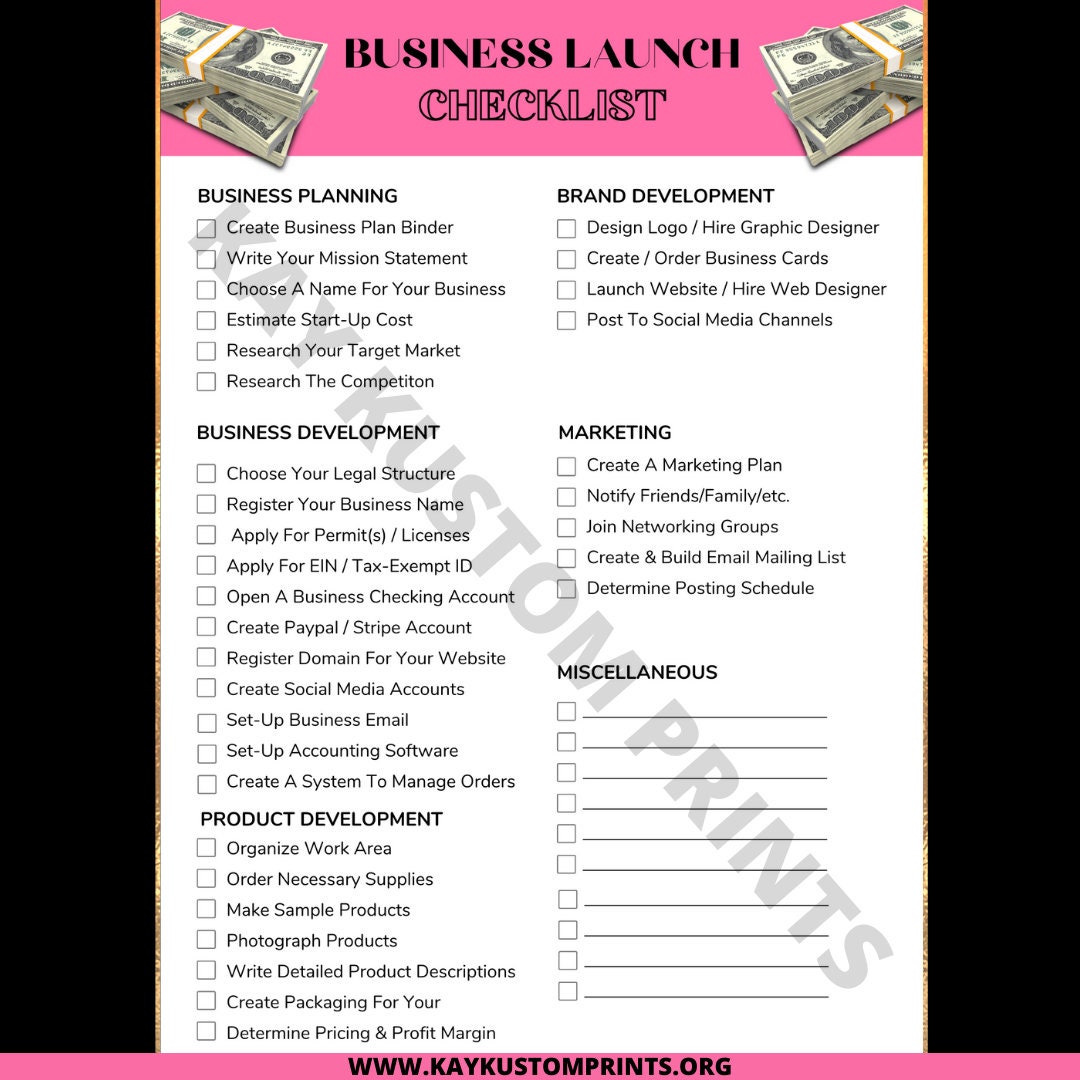
The Business Launch Checklist doesn't end when you open for business. The first thirty days are critical for establishing routines that will sustain you. Review your bookkeeping every Friday. Set aside tax payments immediately. Follow up with every early client to gather feedback and identify gaps in your process. These habits take roughly thirty minutes per week to maintain but prevent the accumulation of problems that become unmanageable within sixty days. I should mention where this framework fails. It assumes you have some baseline capital to cover formation costs, licensing fees, insurance premiums, and minimal marketing. If you're starting with literally zero dollars, the checklist needs significant adaptation. In that case, prioritize the entity formation and banking steps using free or low-cost resources, delay insurance until you have revenue, and rely entirely on organic marketing channels. The framework still applies, but the timeline stretches from weeks to months instead of days to weeks. Another limitation: this guide assumes you're operating in the United States. International founders will need to adapt each step to their local jurisdiction. The dependency chains are similar everywhere, but the specific agencies, forms, and costs will differ. The universal principle is ordering: legal structure before banking, banking before payments, payments before scaling. Follow that sequence and you'll avoid most of the mistakes that derail first-time launches.
The full Business Launch Checklist I use is maintained as a living document that I update after each launch. The current version has about forty items spanning legal formation, compliance, financial setup, operations, marketing, and post-launch maintenance. If you want a copy, the structure above covers the critical path. Everything else is detail that varies by industry, location, and scale. Start with what's common to all businesses, then layer in the specifics once you understand your particular situation. The checklist is a tool, not a destination. Use it to move forward, then refine it as you learn what actually matters in practice.