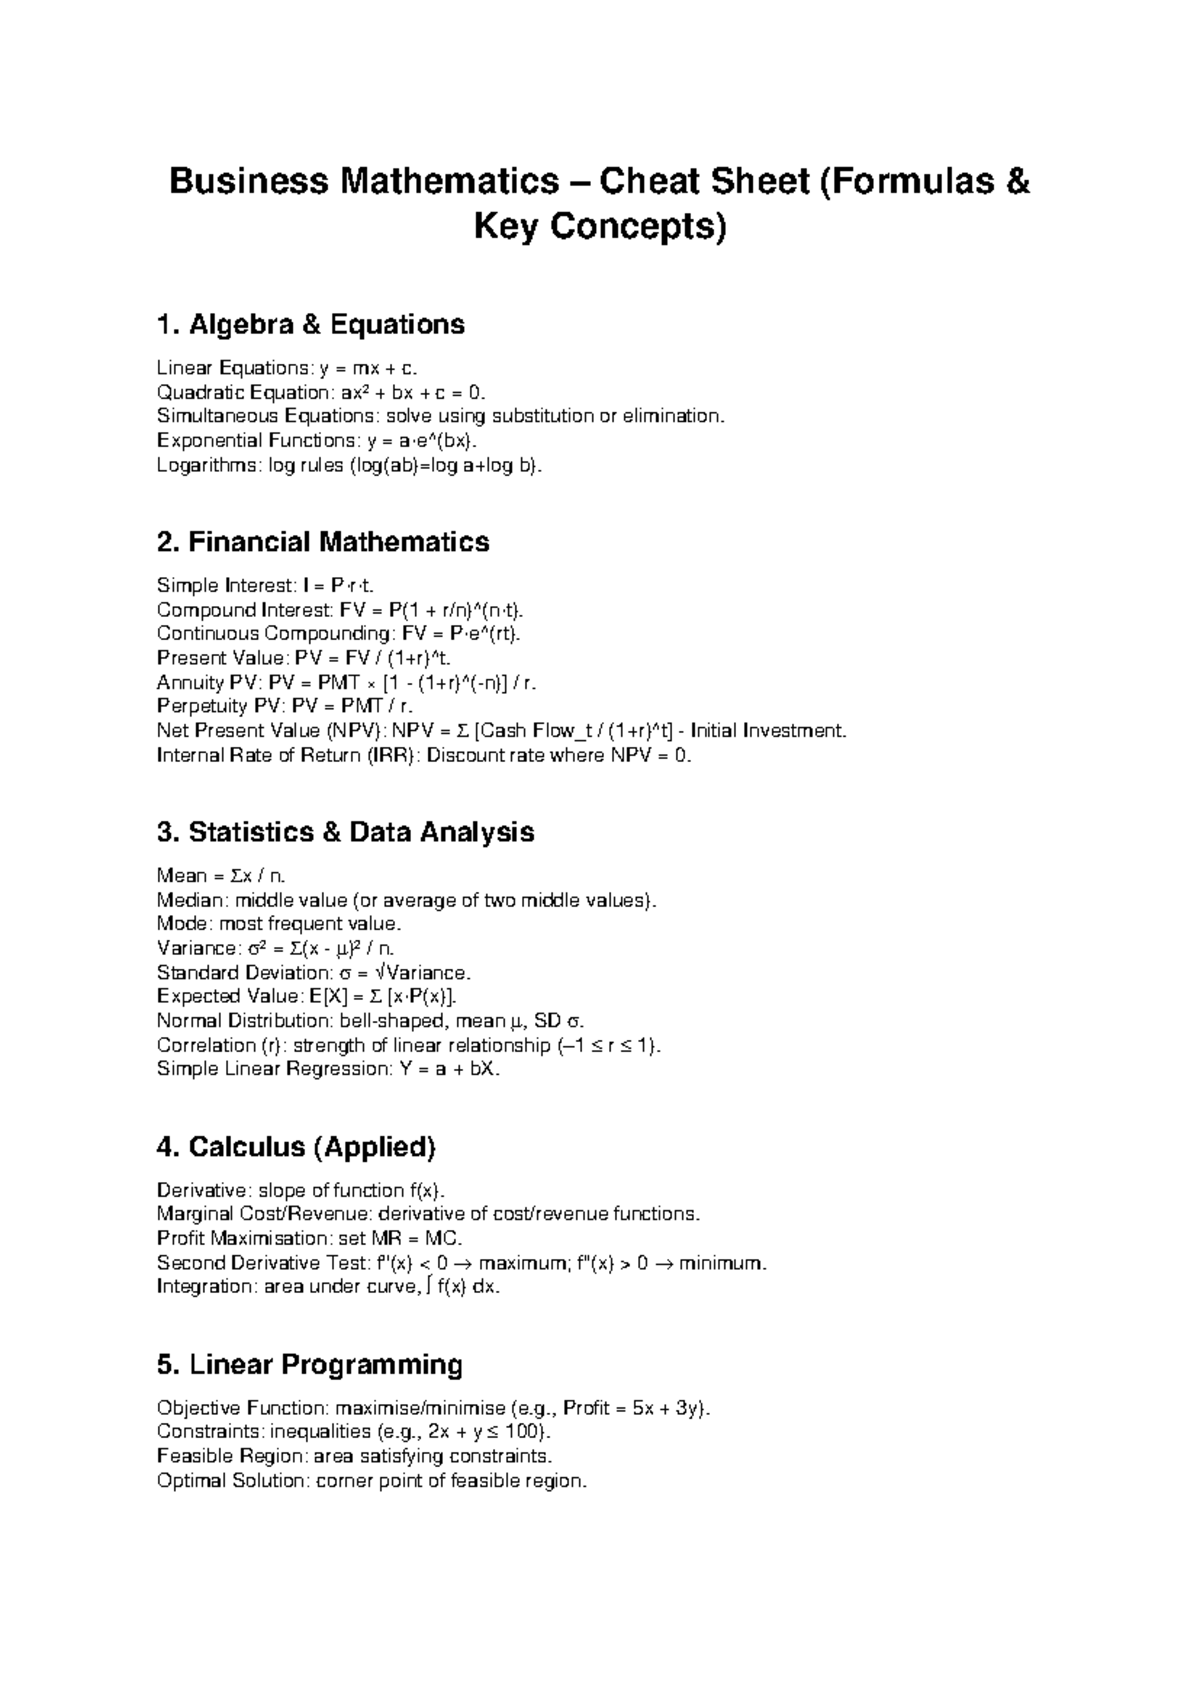
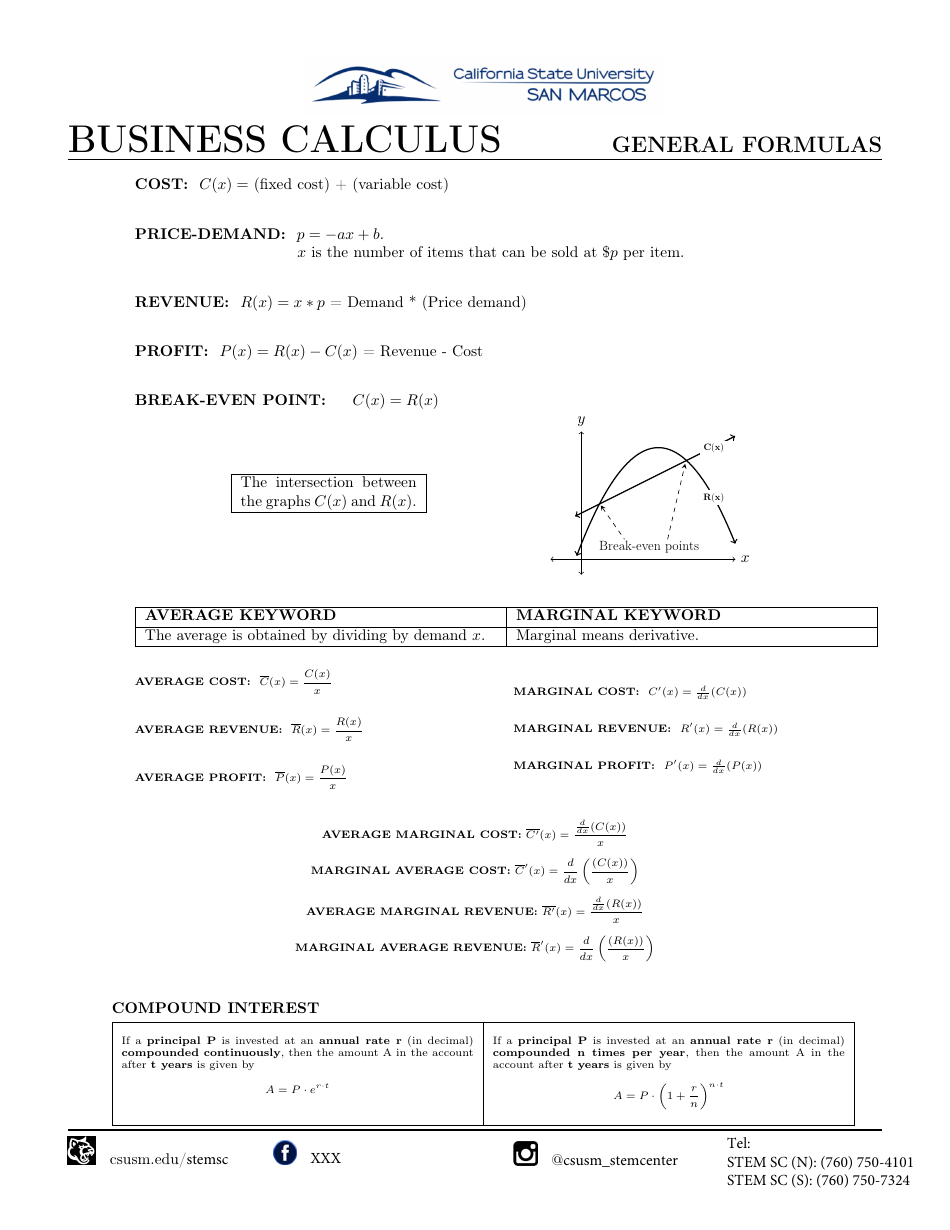
The Formula That Actually Matters
Most people keep a sheet of formulas for Gross Profit Margin, Net Present Value, and Break-Even Point because they need to calculate things quickly. The real question is whether they understand what each number represents in their actual business. I learned this the hard way during a cash flow crisis in 2019 when I had three different spreadsheets with conflicting definitions of Working Capital. One showed current assets minus current liabilities. Another used inventory-only. A third excluded prepaid expenses entirely. I wasted two days reconciling them before realizing each vendor had built their template differently. Business Math Formulas Cheat Sheet documents are everywhere. Some list 50 formulas. Others focus on twelve core calculations. The ones I keep in production are short because I only use what generates decisions. Everything else becomes noise.
Business Math Formulas Cheat Sheet
Here is how I organize mine. The first section covers profitability. Revenue minus Cost of Goods Sold gives Gross Profit. Divide by Revenue and multiply by one hundred for Gross Profit Margin. This ratio tells you whether your product pricing survives competition. Most beginners miss that Gross Margin and Markup are not the same thing. Markup uses cost as the denominator. Margin uses revenue. If you buy something for sixty dollars and sell it for one hundred, your markup is sixty-six point seven percent. Your margin is forty percent. Investors look at margin. Suppliers think in markup. Confusing them creates pricing errors that compound across large purchase volumes. The second section handles time value of money. Present Value of a single future cash flow equals F divided by one plus r raised to the power of n. F is the future amount. r is the discount rate per period. n is the number of periods. Annuity formulas extend this when payments repeat. I use these for equipment purchases and lease versus buy decisions. The formula assumes constant discount rates. Markets do not behave that way. When rates shift monthly, I build a year-by-year table instead of relying on a single annuity calculation. It takes longer but matches how actual financing works. Breakeven analysis sits in section three. Fixed Costs divided by Price minus Variable Cost per unit gives Breakeven Units. This number indicates minimum sales volume before losses stop. I applied this during a product launch where Fixed Costs included marketing commitments and tooling expenses. The formula assumes linear costs. They are rarely linear. Bulk discounts on raw materials create step changes. Capacity constraints cause sudden jumps in Variable Costs. I learned this when a competitor undercut our price and we had to run overtime to fulfill orders. Overtime multipliers increased labor costs by thirty-three percent above normal. The breakeven model I used assumed flat Variable Costs. I patched it by building a tiered cost structure into the spreadsheet. The adjustment added four breakpoints to the analysis.
Formulas Beginners Mess Up
Compound Interest looks simple on paper. Principal times one plus rate per period raised to the number of periods. Most people forget to adjust the rate for compounding frequency. Monthly compounding divides the annual rate by twelve. Quarterly divides by four. Using the wrong period creates errors that grow over long time horizons. I once calculated loan payments using annual compounding when the terms specified monthly. The difference was eight percent over the full term. That represented thousands in extra interest on equipment financing. Return on Investment divides Net Profit by Total Investment Cost. People often exclude hidden costs like training time, implementation delays, and opportunity costs. If you invest in new software but the team spends three weeks learning it instead of generating revenue, that lost productivity reduces actual ROI. I started including opportunity costs in my calculations after a software purchase that looked profitable on paper but dragged quarterly earnings down by twelve percent during the learning curve. Inventory Turnover equals Cost of Goods Sold divided by Average Inventory. High turnover sounds good until you realize it can mean stockouts. Low turnover means capital sitting idle. The optimal range depends on industry. Perishable goods need fast turns. Custom machinery can tolerate slower movement. I run into this when a supplier quoted lead times of sixteen weeks but our models assumed four. We had to carry excess safety stock that tied up working capital. The inventory formula I used did not account for supply chain variability. I patched it by building a buffer stock calculation into the model. The adjustment added eight percent to carrying costs but prevented production stoppages.
Get the Full Details

When the Math Fails
Formulas assume conditions they rarely get. Discounted Cash Flow models break when future cash flows are unpredictable. Startups cannot use them meaningfully. Revenue is too volatile. Even established companies struggle when market conditions shift suddenly. I used DCF for a facility expansion in 2020 and the assumptions proved wrong within six months. The model assumed steady demand growth. The pandemic cut commercial leases by forty percent. The formula gave a positive NPV under old assumptions. Reality told a different story. I switched to scenario analysis with conservative, base, and optimistic cases. The adjustment added three separate valuations but matched how uncertainty actually works in the industry. Economic Order Quantity calculates ideal order size using holding costs, ordering costs, and demand rates. The formula assumes constant demand. It never is constant. Seasonal products create wild swings. I learned this when a holiday merchandise order followed annualized demand. We had excess inventory that required storage fees for nine months out of twelve. The EOQ formula I used did not account for seasonality patterns. I patched it by building a monthly demand variability calculation into the model. The adjustment added twelve percent to average order sizes but reduced peak inventory costs by eighteen percent.
What I Keep on My Desk
Gross Profit Margin. Net Present Value. Internal Rate of Return. Break-Even Point. Working Capital Ratio. Current Ratio. Quick Ratio. Debt to Equity. Inventory Turnover. Days Sales Outstanding. These twelve calculations cover ninety percent of decisions. Everything else I look up when needed. The formulas are standard. The application requires judgment about which costs are fixed versus variable, which time periods matter, and which assumptions are realistic versus optimistic. I do not memorize them. I keep them in a document I update annually. Industry changes. Tax rules change. New accounting standards alter how certain items get classified. The document I maintain reflects current practices in my sector. I share versions with the finance team quarterly. They flag edge cases from their daily work. These additions usually narrow the application rather than expand it. If you are building your first sheet, start with profitability ratios. Add time value formulas once you evaluate investments regularly. Include operational metrics when you manage inventory or receivables. Do not add complexity before the basics generate decisions. A sheet with fifty formulas that nobody references is worse than a sheet with six formulas that drives daily choices.
The numbers only help when they answer questions you actually face. Revenue growth matters if you are expanding. Profitability matters if you are cost-cutting. Liquidity matters if you are managing cash flow. Match the formulas to the decisions. Everything else is academic exercise.