The difference between a business model and a business plan, explained like someone who has watched founders mix them up for years
Most people treat these two things as interchangeable. They are not. A business model describes how a company creates, delivers, and captures value. It is the engine. A business plan is a document that lays out the strategy, market analysis, financial projections, and operational details for starting or growing that company. It is the blueprint. I spent the early part of my career building business models for seed-stage startups. What I quickly learned is that the model is where the actual math lives. The plan is where the persuasion lives. If you skip the model work and jump straight into the plan, you will have a beautifully formatted document with numbers that do not add up. This happens constantly. Investors see it immediately, usually within the first thirty seconds of reading a financial section.
How to build your Business Model And Business Plan without losing your mind
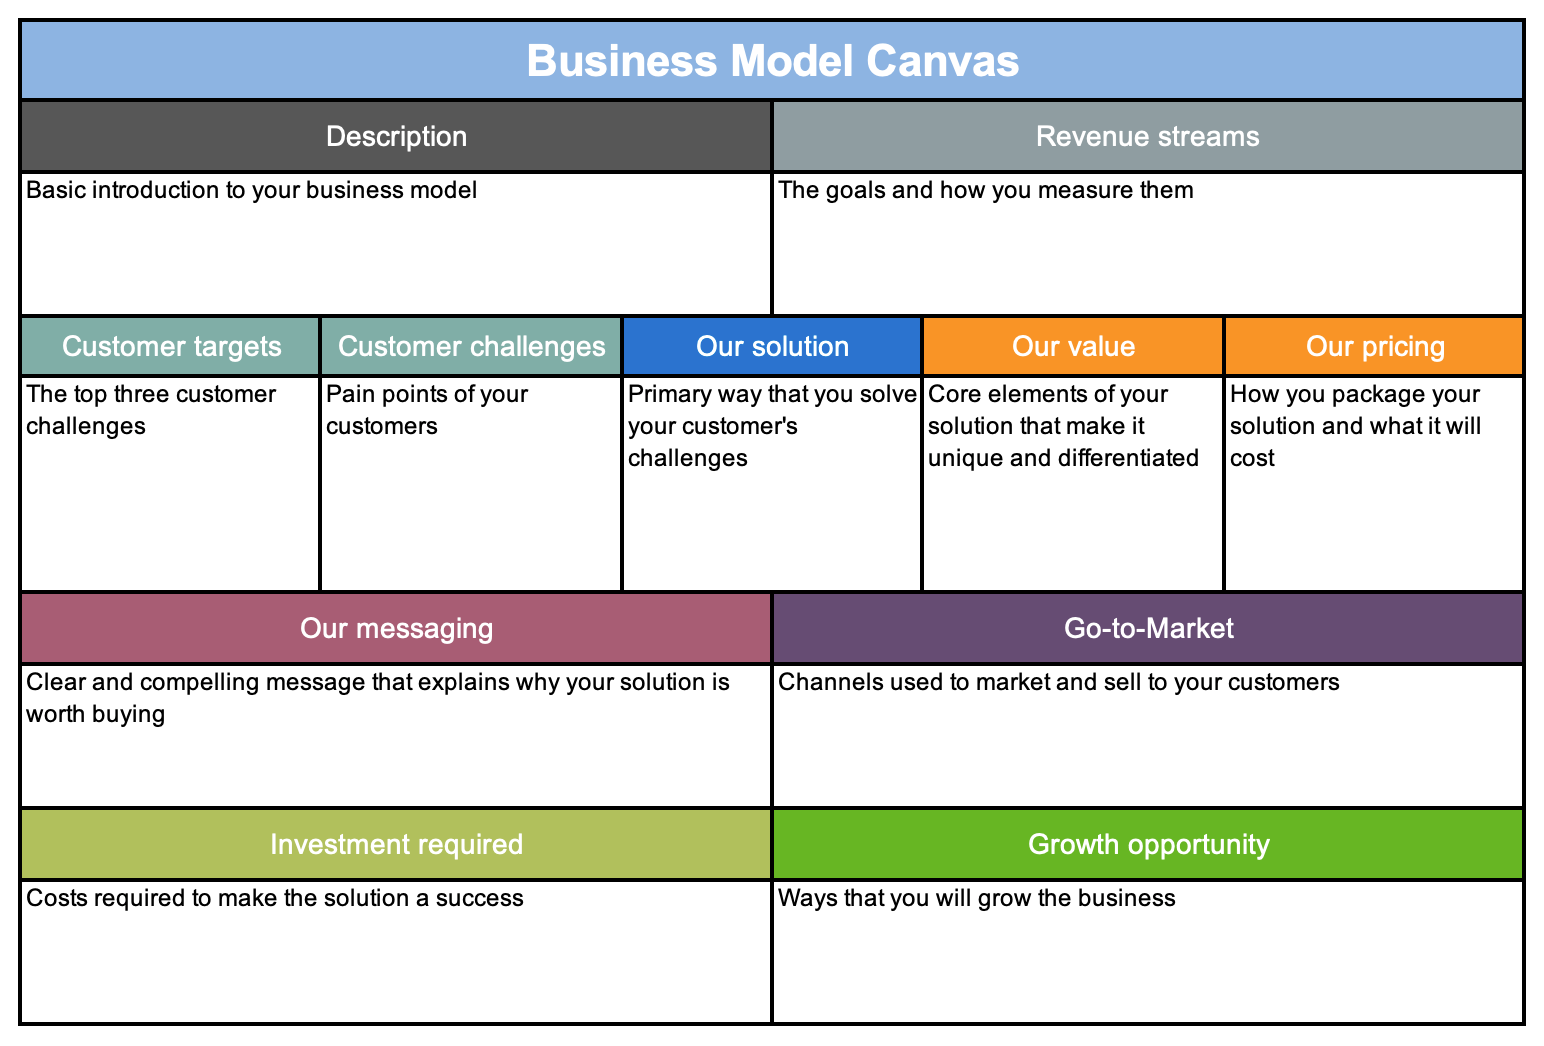
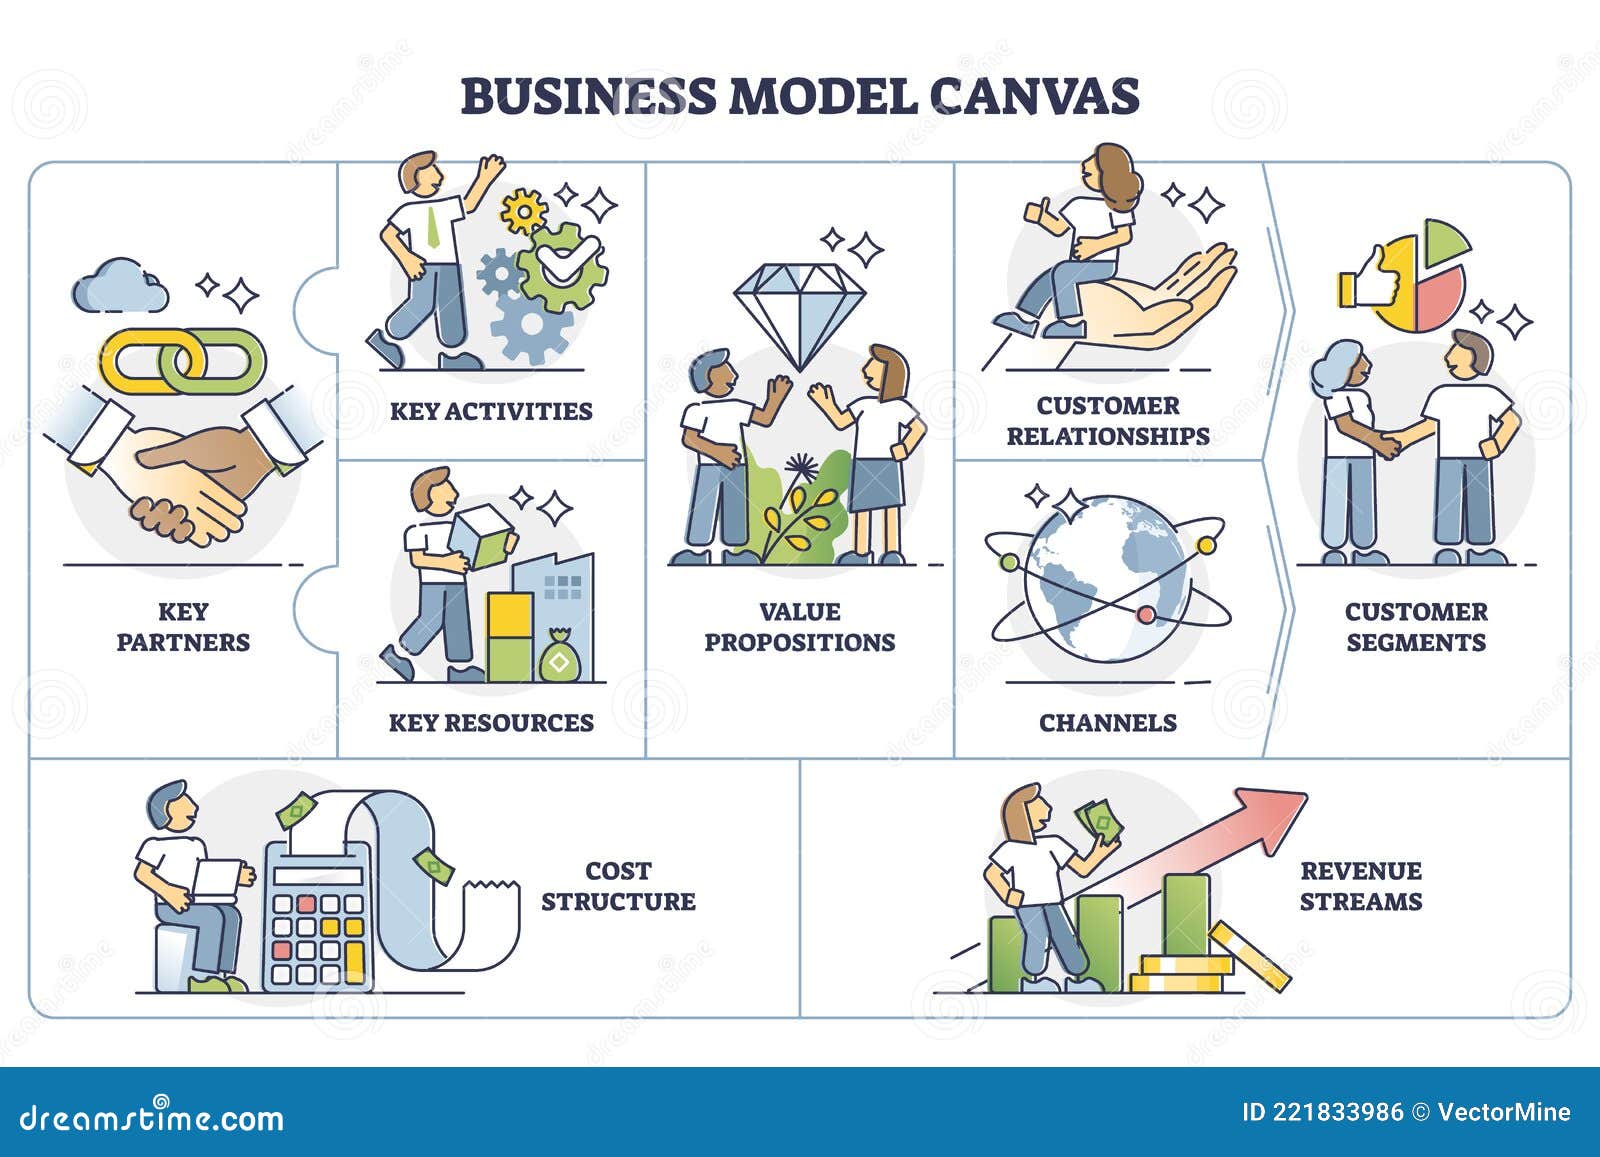
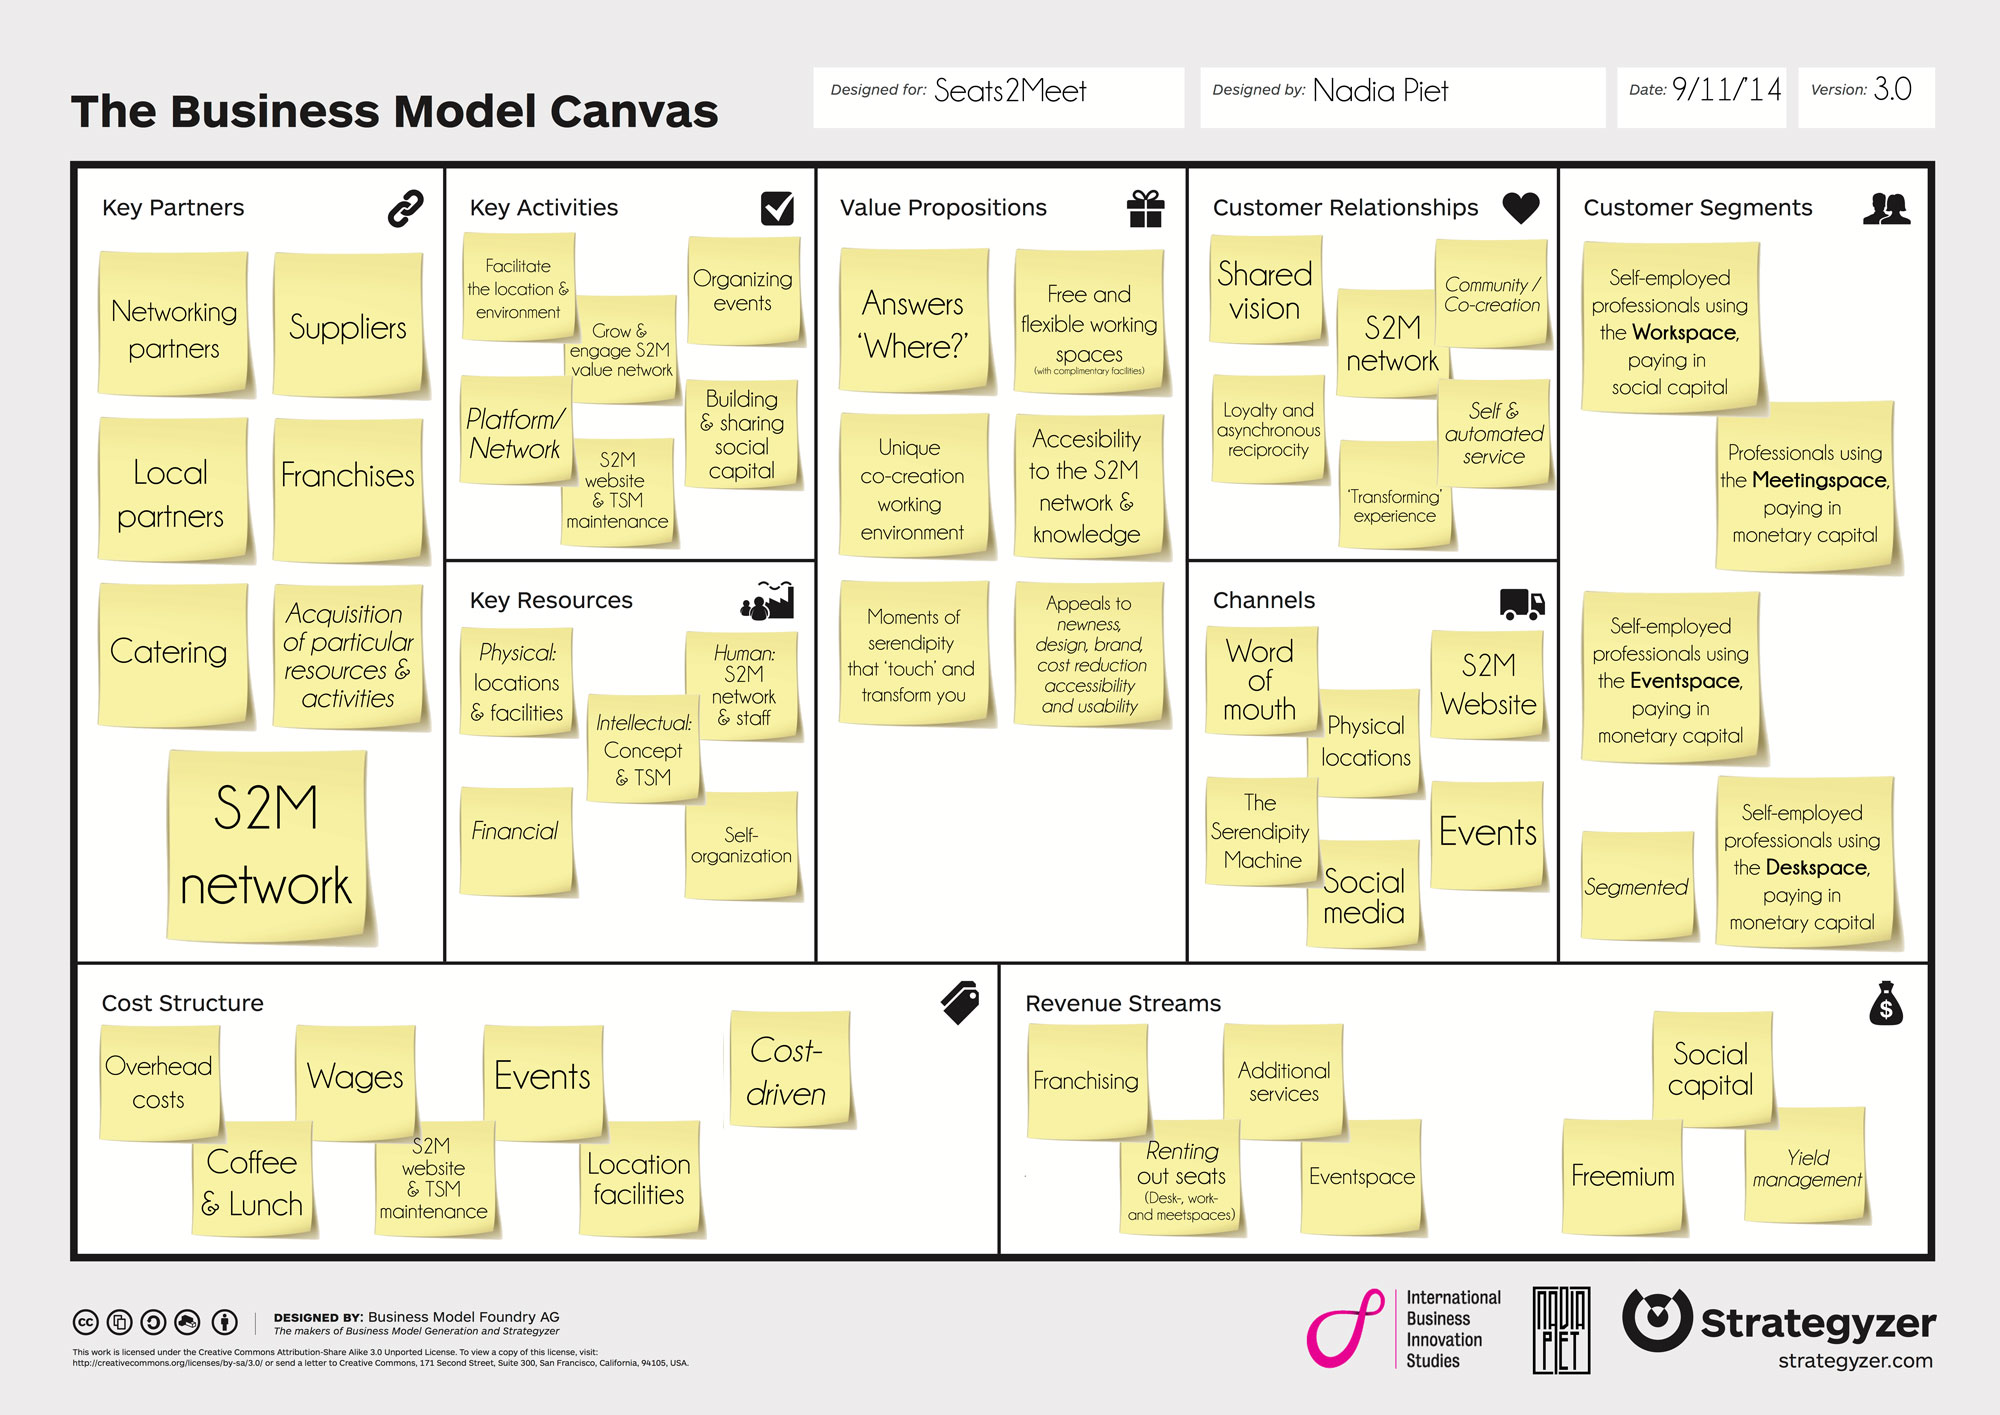
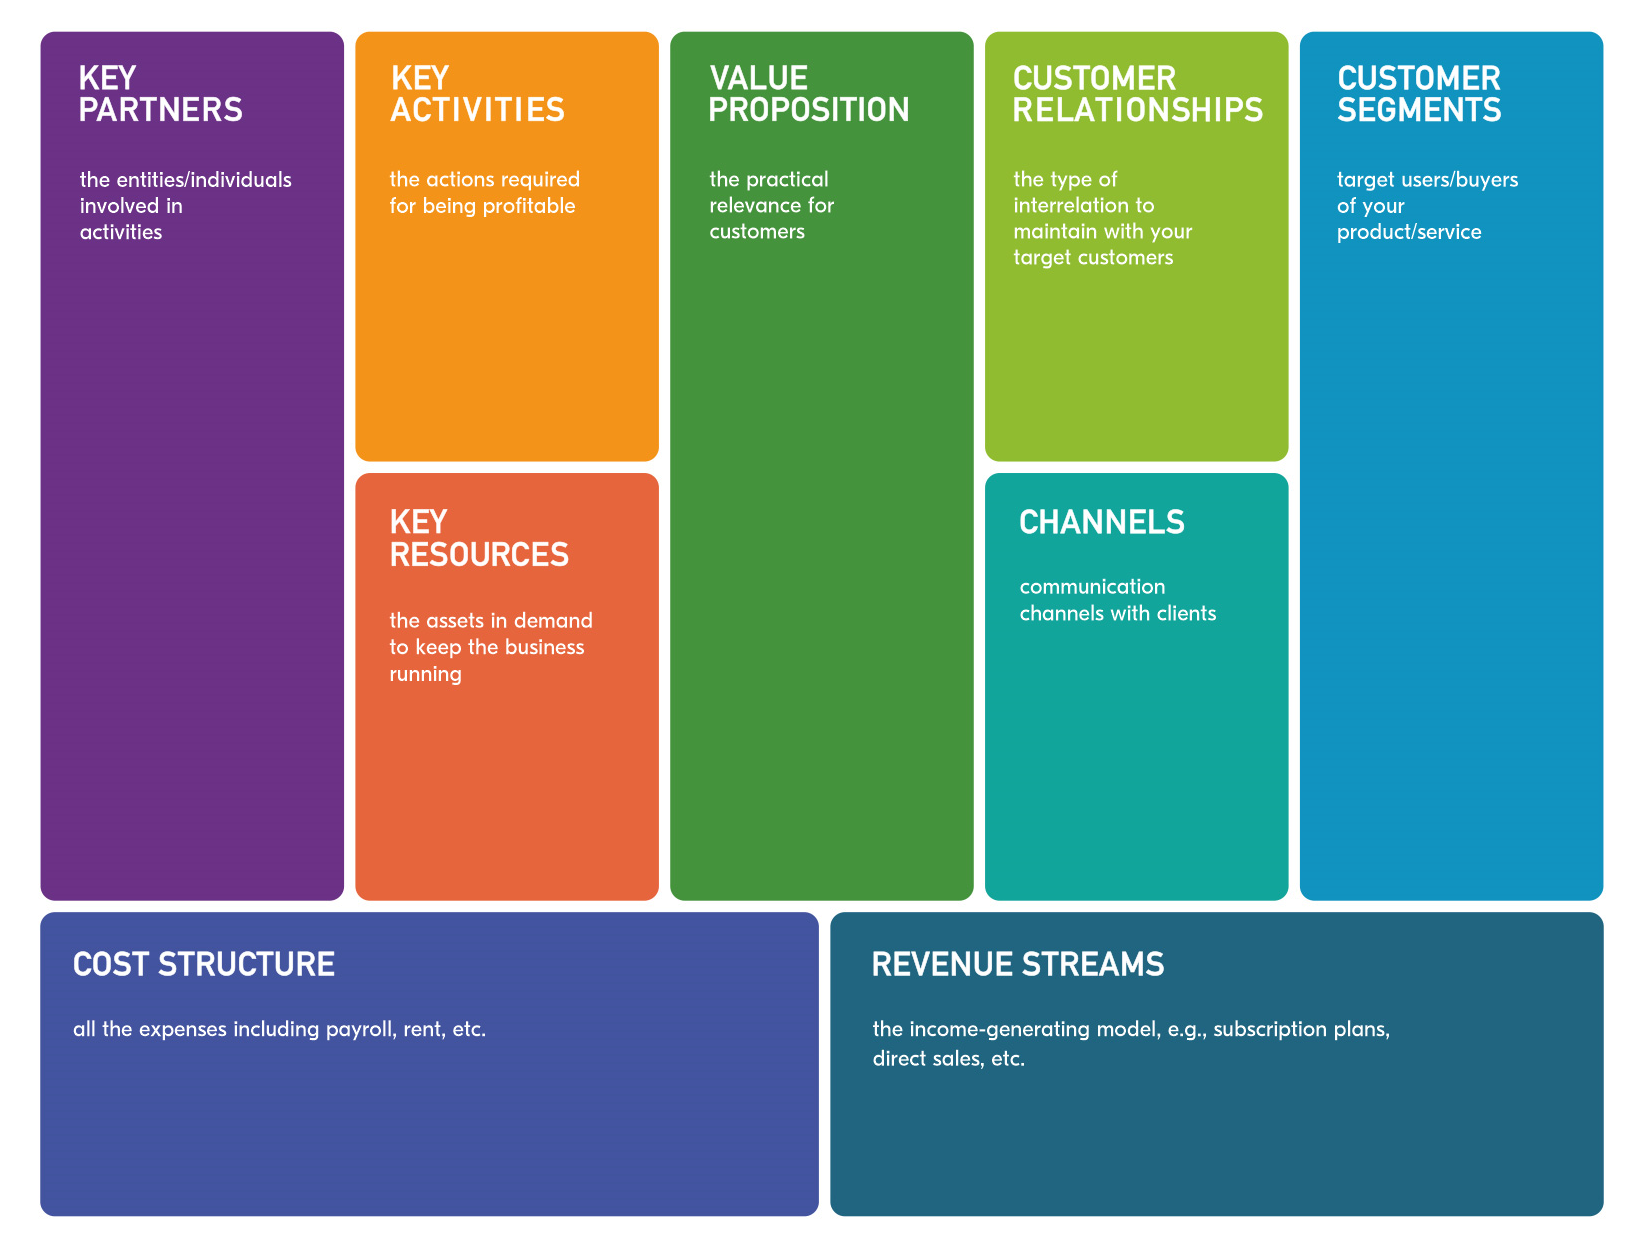
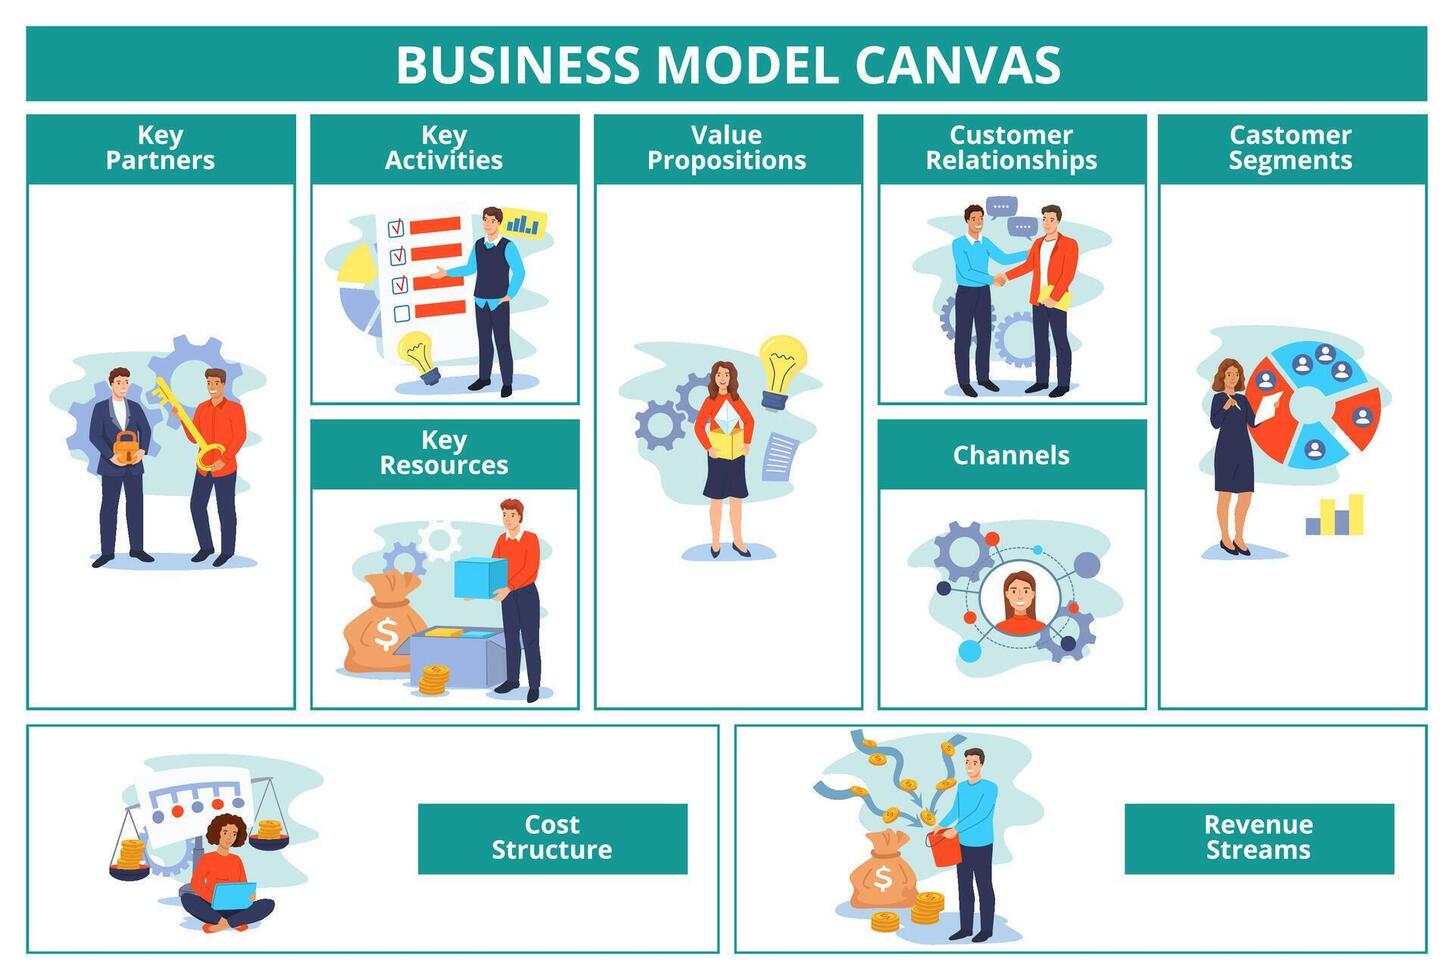
Start with the model. Not the plan, the model. Write out how your product or service makes money, who pays for it, what it costs to deliver, and where the margins actually sit. I use a modified version of the Business Model Canvas because it forces you to answer specific questions before you can move forward. The nine blocks are Customer Segments, Value Propositions, Channels, Customer Relationships, Revenue Streams, Key Resources, Key Activities, Key Partnerships, and Cost Structure. Fill them in on a whiteboard or in a spreadsheet. Do not skip any block. The common mistake is treating the Value Proposition as a marketing slogan. It is not. It is a functional statement about what problem you solve and for whom. My approach was always to write it as: "We help [specific customer segment] achieve [specific outcome] by [specific mechanism]." When this sentence was vague, the whole model fell apart during due diligence. A concrete example from my own experience: I worked with a client running a B2B SaaS product targeting small manufacturing firms. Their value proposition read as something generic about efficiency. We rewrote it to specify exactly which process they automated and by what percentage based on pilot data. The funding conversation improved noticeably because the model suddenly had measurable anchors. Once the model is solid, the business plan becomes mostly transcription and elaboration. You take each block from the canvas and expand it with research, timelines, staffing plans, and financials. The plan should reference the model explicitly so anyone reading can see the connection between the revenue engine and the projections.
Here is a practical detail most guides skip: your financial model should live in a separate spreadsheet from the narrative plan. I keep a three-statement model built on monthly granularity for the first two years and annual thereafter. The revenue assumptions feed directly from the pricing and customer acquisition blocks in your business model. The cost assumptions feed from the Key Resources and Key Activities sections. When the model and plan are decoupled, you can update projections in minutes instead of rewriting paragraphs. This usually cuts revision time from about four hours down to roughly twenty minutes after the initial setup. The counter-intuitive part most beginners miss is that a thinner business plan often performs better with early-stage investors. I have seen five-page plans pass where twenty-page plans failed. The reason is not creativity. It is that a shorter plan forces clarity in the model itself. If you cannot explain your customer acquisition cost in one paragraph, adding three more pages will not fix that. The gap in the model is still there. Another nuance nobody talks about enough is the relationship between channel economics and customer lifetime value. In one project I reviewed, the founder had impressive gross margins on paper but did not account for the fact that their primary sales channel took a thirty percent cut plus longer payment terms. The net margin collapsed once you modeled cash flow timing correctly. The workaround was building a cash conversion cycle schedule alongside the P&L. That single addition revealed a liquidity problem the original model completely missed. Most people check profitability but forget to check whether the money actually arrives on time.
Get the Full Details
When you are ready to put the plan together, use this rough order of sections: Executive Summary, Company Description, Market Analysis, Organization and Management, Product or Service Line, Marketing and Sales Strategy, Funding Request, Financial Projections, Appendix. Put the funding request in the middle if you need capital. Leading with it sounds desperate and skews how readers evaluate everything that follows. Place it after the market and product sections so the reader has context for why you need the money. For the financial section, include a break-even analysis, a cash flow forecast, and a sensitivity table showing what happens if revenue comes in twenty percent lower than expected or customer acquisition costs rise by fifteen percent. Investors expect at least one scenario analysis. Omitting it signals that you have not stress-tested your assumptions. I build a three-scenario model as a standard: base case, downside case, and upside case. The downside case usually reveals the single most fragile assumption in the business model. In my experience, identifying that fragility early saves a lot of embarrassing conversations later. Templates exist and they are fine as a starting point. I recommend the Standard Business Plan Template from SCORE or a clean template from LivePlan if you want something pre-formatted. These will give you the structural skeleton. They do not do the thinking for you. Fill them with your own numbers and logic. A downloaded template without original research is just an empty container.
There is also a scenario where a traditional business plan is the wrong tool. If you are operating in deep uncertainty with no validated customer segment, spending three weeks writing a plan is likely waste. In that case, use a lean canvas or run a series of experiments to test core assumptions first. The business model can be revised quickly on a single page. The full plan should wait until the model has survived at least one round of real market feedback. This distinction matters because several clients of mine tried to pitch with fully written plans built on untested assumptions and got turned down not because the writing was bad but because the underlying assumptions had not been proven. If you want a downloadable starting point for the financial model itself, a search for "three-statement financial model template" will surface several free options. I typically adapt one of those and strip it down to only the line items relevant to the specific business. The default templates come with too much infrastructure accounting garbage that slows you down and adds noise. The final note I will leave here is that neither the model nor the plan is a static artifact. They are living documents. Update the model quarterly. Update the plan whenever a material assumption changes. I set a standing calendar reminder for this because it is easy to let both drift into irrelevance and then pretend they are still accurate. The habit of regular updates is what keeps the numbers honest over time.