Handling B2B ACH Payments and Georgia Tax Compliance
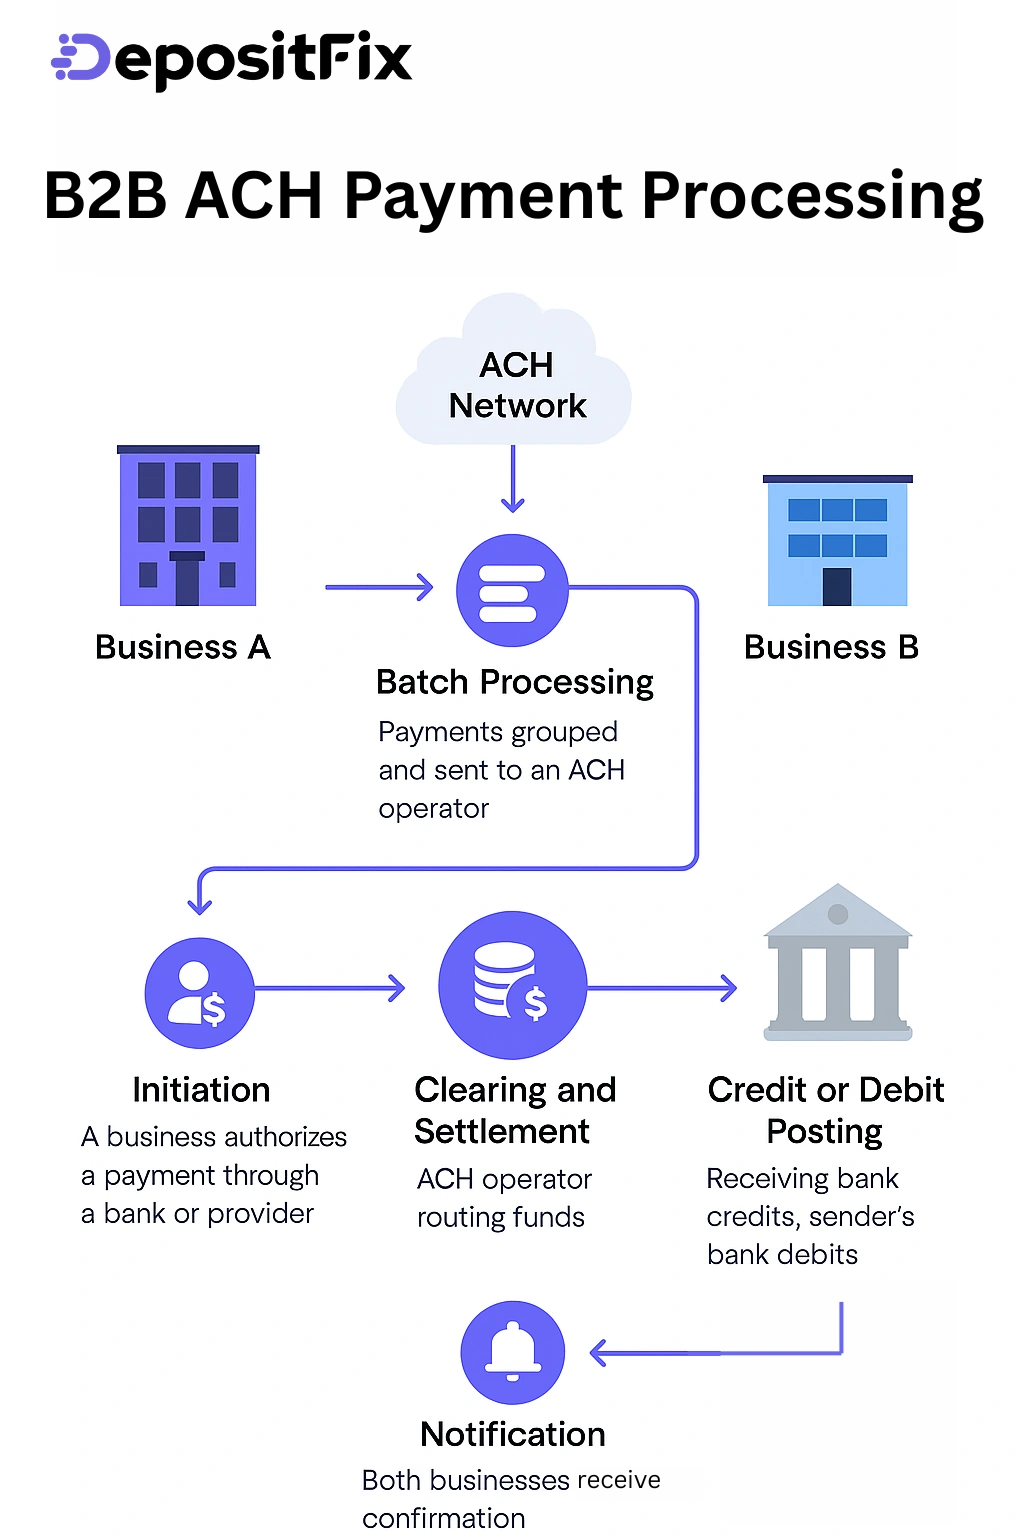
Most businesses don't think about ACH transactions until the Georgia DOR asks for documentation. You process payments, money moves, and then come April you realize you've got gaps in your records. I've been dealing with this since before online portals made everything look simpler. Here's how it actually works. When you run ACH transfers between companies, Georgia treats those as reportable transactions depending on what they're for. The main issue isn't the transfer itself — it's what the transfer represents. Payment for services, goods, consulting fees, subcontractor work. Each one has different tax treatment. If you're paying a vendor in another state for services performed partly in Georgia, you might have withholding obligations that most people completely miss until they get a notice. The practical problem: Georgia requires form GA-501 for non-resident contractor withholding when payments exceed certain thresholds. I had a client who sent $45,000 in ACH payments over a fiscal year to an out-of-state IT consultant without realizing the service was partially performed in Georgia. The DOR flagged it during an audit two years later. They owed back taxes plus interest. The workaround would have been trivial — file GA-501 quarterly and remit the proper withholding at the time of each payment. But nobody told them to do that because the ACH processor doesn't prompt for tax compliance. Your bank won't either.
Here's the counter-intuitive part that trips people up. ACH originators don't see tax liability just because money moved electronically. The electronic nature of the transaction is irrelevant to the tax authority. What matters is the underlying transaction type and where the work was performed. I've seen business owners argue with auditors that "it was just an ACH transfer" as if that changes anything. It doesn't. The tax obligation exists independently of the payment method. What you actually need to track: the nature of each B2B ACH payment, the vendor's tax status (W-9 on file or not), whether any portion of the work related to Georgia, and the cumulative annual amount paid to each vendor. Set up a simple spreadsheet or use accounting software that categorizes payments by vendor and transaction type. When you get a W-9 from a vendor, note their location and the type of work they do. If they're out of state but performing services in Georgia, flag it immediately. The thresholds that matter in Georgia: non-resident withholding kicks in at $600 or more in a calendar year for services performed in Georgia. That's per vendor, per year. So if you pay five different out-of-state consultants $500 each, you have zero withholding requirement. But if you pay one consultant $601, you're on the hook for the full amount's withholding, not just the $1 over the line.
For sales tax purposes, ACH payments between businesses generally aren't subject to sales tax unless they're for taxable goods or services. But here's where it gets messy — if you're the recipient and you're paying Georgia sales tax on a purchase, the fact that you paid via ACH doesn't change anything. You still need to collect and remit properly if you're the seller. I've watched small businesses lose sleep over this because they thought "business-to-business" automatically meant exempt. It doesn't. Georgia's resale exemption requires a valid certificate from the buyer, and the payment method is irrelevant. If you want official forms, the Georgia Department of Revenue maintains everything at dor.georgia.gov. Look under the Business Withholding section for GA-501 and GA-502. For sales tax, check the seller's permit and exemption certificate guidelines. No need to download anything right now — just bookmark it and reference it when you're processing payments. The honest downside to tracking this manually is that it's tedious and easy to forget. Most accounting software handles this reasonably well if you set it up correctly from the start, but if you're already months into operations without proper categorization, you're looking at a data cleanup exercise. Start fresh with clean records going forward. Past mistakes are past mistakes, but the statute of limitations in Georgia is generally three years for assessment, so don't ignore old problems either.
Get the Full Details