The Real Estate Purchase Checklist Nobody Actually Reads (Until It's Too Late)
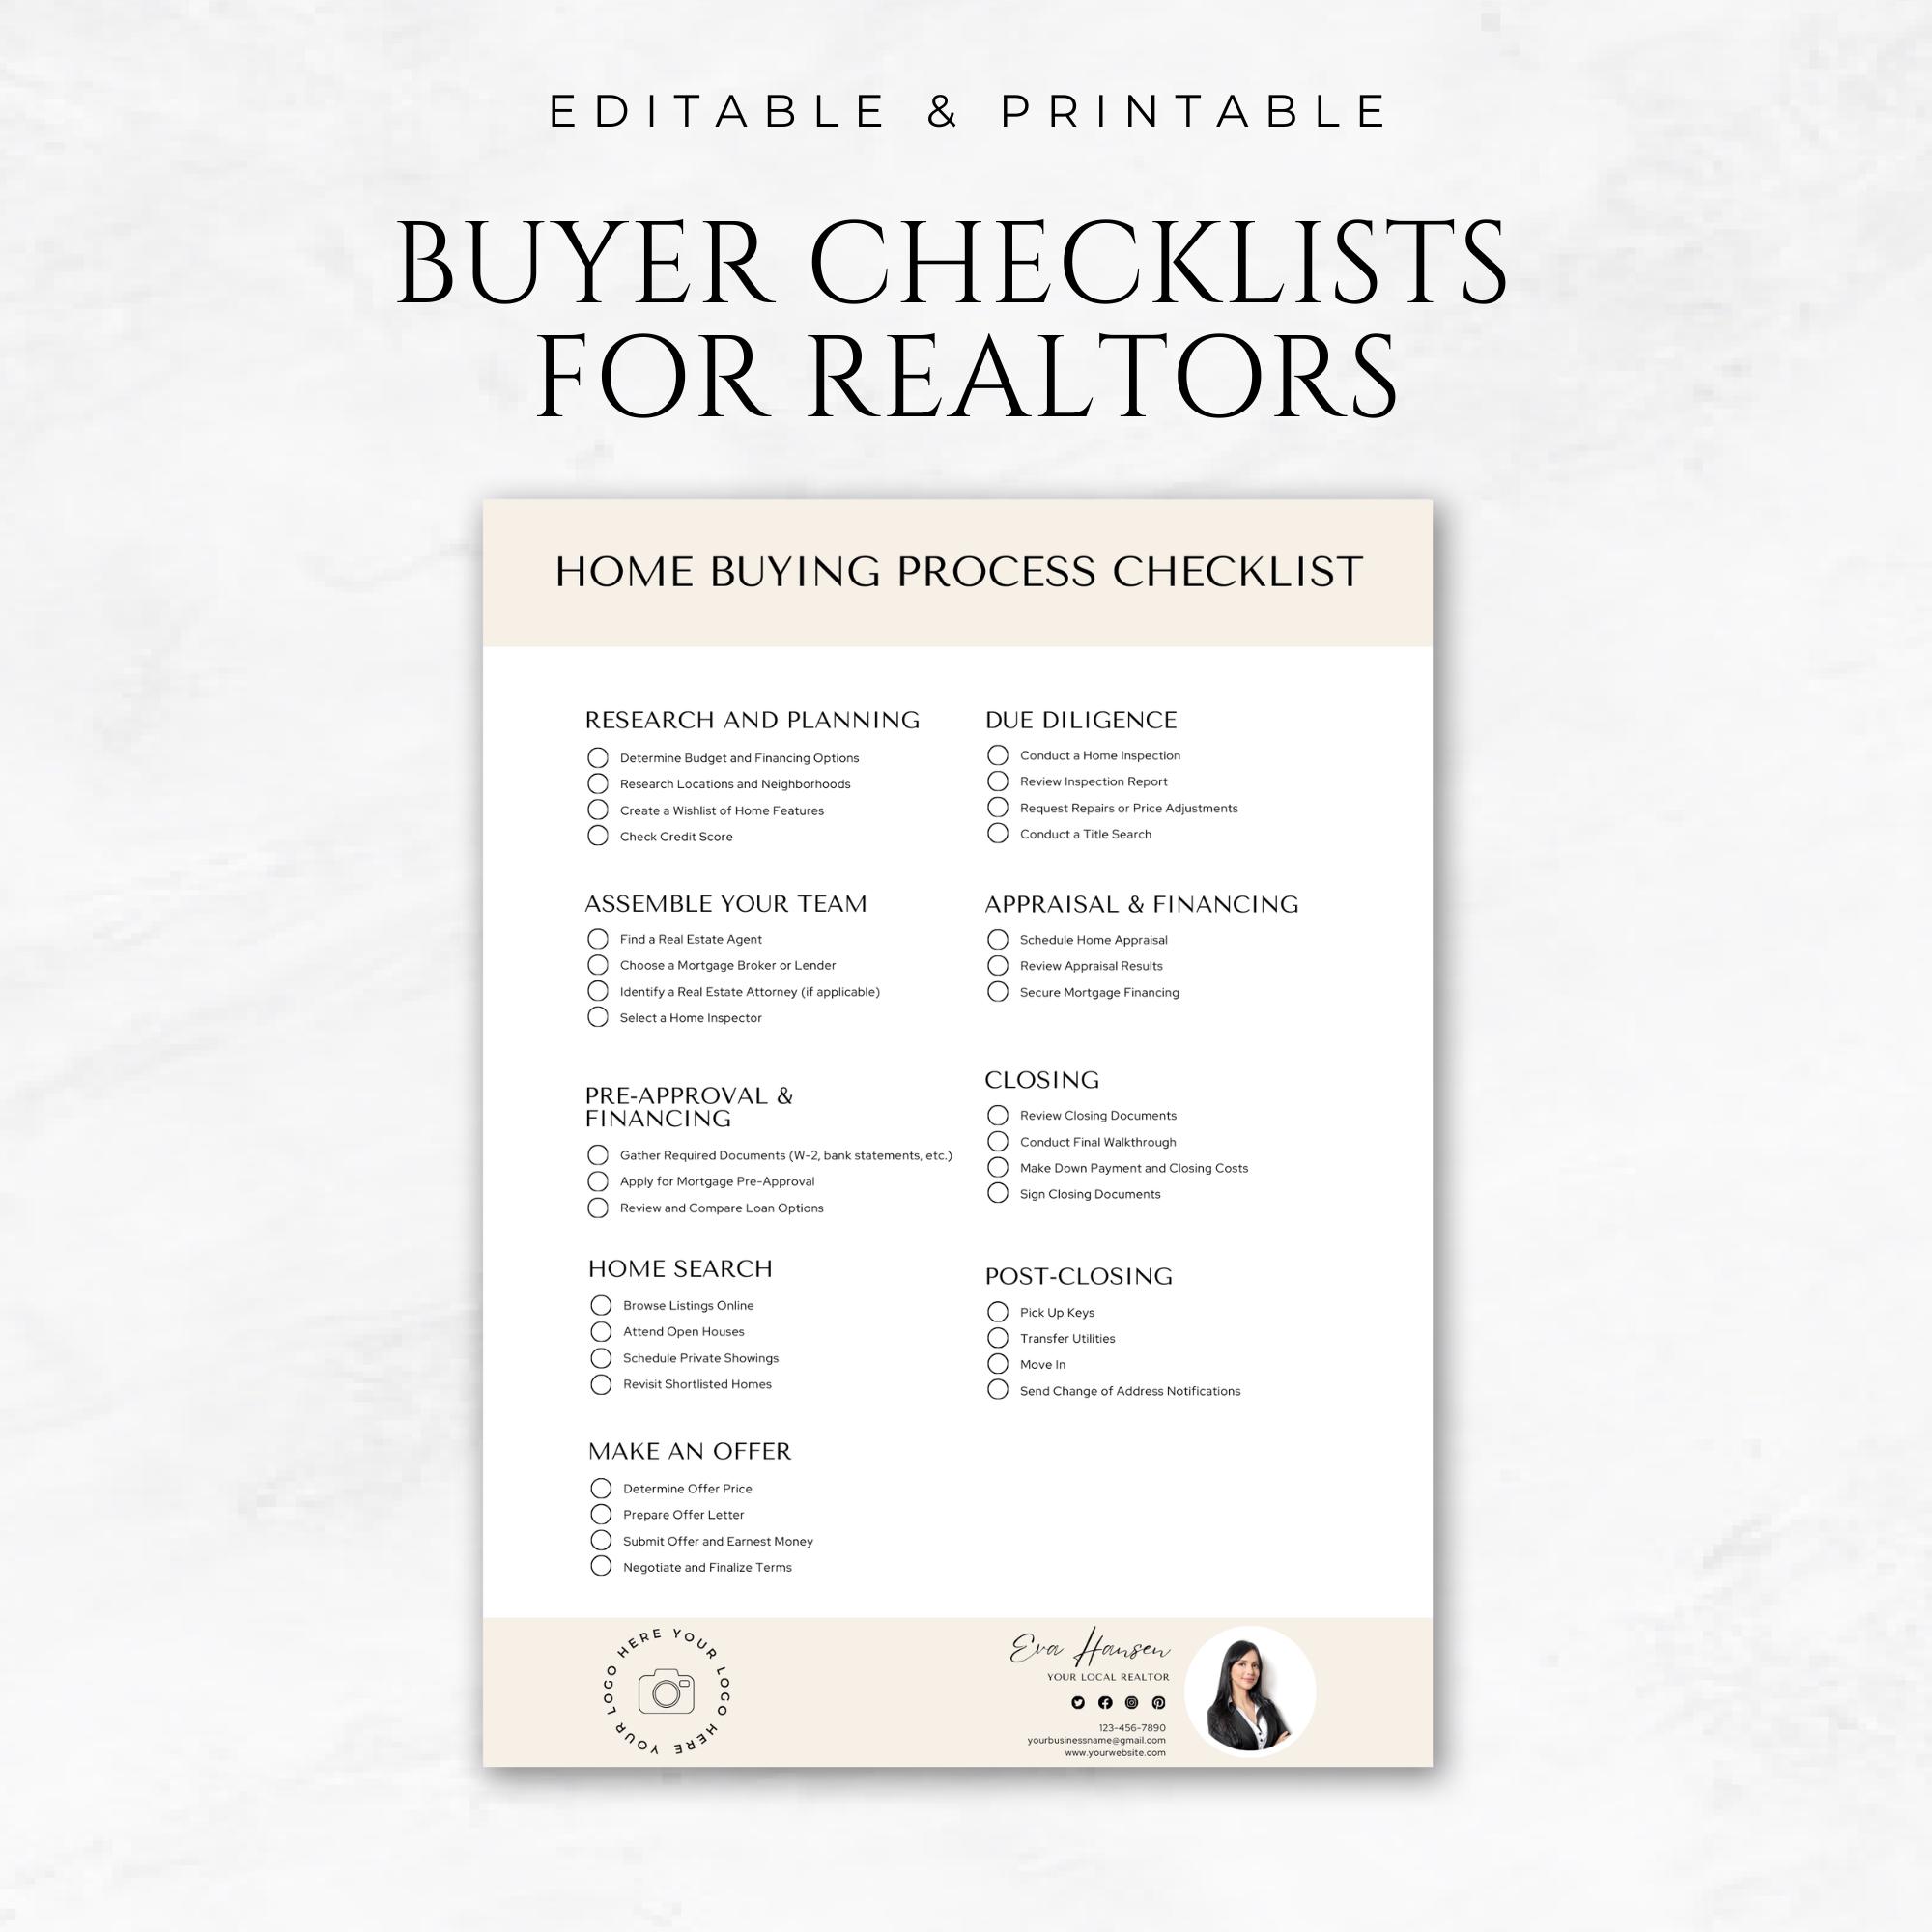
Most buyers scroll through checklists like they're reading a grocery list. They tick "inspect the house" and move on. That's how people end up with foundation cracks they didn't know about and closing costs that triple their budget. A proper Buyer Guide For Real Estate Checklist isn't about marking boxes. It's about knowing which boxes actually matter and which ones are just noise. Here's what the checklist should actually look like when you build one. Don't download someone else's generic PDF. The ones that circulate online are usually written by people who've never actually closed a deal in a competitive market. They leave out the stuff that bites you. Start with the financial pre-approval. Not pre-qualification. Pre-approval means a lender has verified your income, assets, and credit. Pre-qualification is a handshake. Sellers in any decent market won't touch a pre-qualification letter. Get the real thing before you even look at properties. It takes about 48 hours if you have your documents organized—W-2s, recent pay stubs, bank statements, and your tax returns from the last two years. Keep them in a single folder. Trust me on that.
Next comes the property search with a budget that includes more than just the sticker price. I'm talking about closing costs, which run 2 to 5 percent of the purchase price depending on where you are. Property taxes. Homeowners insurance. HOA fees, which in some developments can be $400 to $800 a month and come with special assessment clauses that can hit you for tens of thousands if the association's reserves are low. I had a client in 2022 who fell in love with a townhouse with a $38,000 annual special assessment already approved. The HOA board was quietly planning a full roof replacement. The seller disclosed it in paragraph 14 of a 47-page document. Most buyers never read paragraph 14. The inspection phase is where the checklist usually fails people. "Schedule inspection" sounds simple until you're standing in a basement at 7 AM on a Saturday with a inspector who spent 90 minutes and found nothing wrong because he was checking his phone between rooms. Don't hire the inspector your real estate agent recommends unless you've verified their work independently. Find someone through friends, local forums, or the state licensing board. Go to the inspection yourself. Ask questions. Take photos of everything. Write down the dates on repair estimates. The average inspection costs $350 to $600. Wasting that money on a mediocre inspector costs you more later. After the inspection, you negotiate. This is where your checklist should include a repair credit or price reduction request, not just a demand for fixes. I've seen buyers get their offer rejected because they asked the seller to replace the entire HVAC system rather than accept a $3,000 credit. The seller walks, you lose the house, and you're back to square one. Learn the difference between a cosmetic issue and a structural one. Cosmetic issues are negotiation leverage. Structural issues are deal-breakers or price adjustments. A cracked driveway slab isn't the same as a cracked beam.
Appraisal comes next. If the appraisal comes in low—and it does more often than people expect—you have a few options. You can renegotiate with the seller, bring the difference to closing in cash, or walk away if your contract has an appraisal contingency. About 15 to 20 percent of appraisals in busy markets come in below the contracted price. Having cash reserves ready for this scenario separates serious buyers from the ones who lose deals at the finish line. Title search and title insurance. This is the part everyone rushes through. A title search reveals liens, unpaid taxes, easements, and ownership disputes that go back decades. I once worked with a buyer who skipped a thorough title review because the agent said "it's probably clean." The title had a mechanic's lien from 1998 that hadn't been cleared. It took six months and $12,000 in legal fees to resolve. Title insurance costs about $1,000 to $2,000 for a standard policy. Don't skip it. Don't accept the seller's existing policy. Get your own owner's policy. Closing disclosure review. You'll receive this document at least three business days before closing. It breaks down every fee, every credit, and every adjustment. Read it. Compare it to your initial loan estimate. Discrepancies are normal to some degree, but large unexpected charges are not. I've seen closing costs jump by $4,000 because the lender added an undocumented processing fee that wasn't in the original estimate. You catch that in the three-day window or you pay it.
Get the Full Details
Final walkthrough. Schedule this 24 to 48 hours before closing, not the day of. You need time to act if something is wrong. The seller might have damaged the property moving out, removed fixtures that were supposed to stay, or left behind items that aren't part of the sale. The walkthrough isn't a formality. It's your last chance to verify the condition of the home matches what you agreed to buy. Here's the part most checklists don't cover: post-closing tasks. Change your locks. Transfer utilities into your name. Update your address with the bank, your employer, and the DMV. Set up a maintenance schedule for the first 90 days. New homeowners tend to ignore minor issues because they just bought a house and everything feels fine. A small water stain on the ceiling becomes a rot problem in three months if you don't address it. Keep a record of every repair, every contractor you hire, and every warranty that comes with appliances or systems. That record protects you when you eventually sell. The biggest mistake people make with checklists is treating them as linear. Real estate doesn't work that way. You'll often be doing a final walkthrough while waiting for title insurance, and reviewing the closing disclosure while the appraisal is still pending. Build flexibility into your timeline. Overlap tasks where possible. Keep a running document—Google Sheets works fine—where you track the status of each item, who's responsible for it, and the deadline. When three things are happening simultaneously, a spreadsheet prevents the kind of panic that leads to missed deadlines and lost deposits.
Another thing nobody warns you about: emotional fatigue. The process from offer to closing typically takes 30 to 45 days. You're making high-stakes decisions every single day. You'll second-guess your offer price. You'll wonder if the inspector missed something. You'll stress about the appraisal. You'll read the fine print and realize you don't understand half of it. This is normal. Take breaks. Don't make decisions at midnight. And don't let anyone pressure you into waiving contingencies because "the market is moving fast." Contingencies exist for a reason. The market will wait for you if you have the right financing and the right terms. One more thing that bites people:HOA document reviews. In communities with HOAs, you're required to receive and review their governing documents before closing. Covenants, conditions, and restrictions. Meeting minutes. Financial statements. Reserve studies. I had a buyer in 2023 who skipped the reserve study because the numbers looked complicated. Two months after closing, the HOA approved a $25,000 special assessment for a new fence and gate system. The reserve study showed the association had $18,000 in total reserves for 120 units. The buyer's share of that assessment was roughly $4,600. If they'd read the reserve study, they would have known the association was underfunded and could have renegotiated or walked away. So here's the actual checklist structure I'd recommend building for yourself:
Pre-Offer Phase Secure pre-approval from a reputable lender with documented rates and expiration dates. Research the neighborhood thoroughly—crime stats, school ratings, future development plans, flood zones.
Define your must-haves versus your nice-to-haves. Be honest about what you can actually afford, not what a calculator says you might qualify for. Offer and Negotiation Phase Draft the offer with clear terms, realistic contingencies, and a competitive but defensible price.
Schedule the inspection within five to seven days of acceptance. Review the seller's disclosure documents thoroughly—every page. Due Diligence Phase
Order the appraisal through your lender. Complete the title search and purchase owner's title insurance. Review HOA documents if applicable—covenants, financials, meeting minutes, reserve studies.
Negotiate repairs or credits based on inspection findings. Closing Phase Review the closing disclosure against your initial loan estimate for discrepancies.
Conduct the final walkthrough within 48 hours of closing. Bring certified funds or arrange a wire transfer for closing costs and down payment well in advance. Sign all documents and record the deed.
Post-Closing Change locks and update all addresses. Transfer utilities and set up ongoing payments.
Create a maintenance log and schedule for the first year. File the deed with the county recorder's office if your state requires it. Build this into a living document. Update it after every transaction. You'll start noticing patterns—things that always go wrong, lenders that consistently delay, inspectors who cut corners. That accumulated knowledge is worth more than any downloadable PDF you'll find online. The checklist isn't the goal. The goal is closing a house without losing your mind or your money.