How to Use a Buying Land Loan Calculator Without Losing Your Shirt
Most people treat a buying land loan calculator like it's going to hand them a clear path to financing. That's not really how it works. It gives you a ballpark, maybe 90% accuracy if you plug in clean numbers, but land loans are messier than home mortgages and the calculator won't tell you that. I've sat across from borrowers who came out confident because their spreadsheet showed a beautiful monthly payment, then found out their "raw land" was actually classified as agricultural with different tax implications, or that the lot had no road frontage and the bank was going to demand 40% down instead of 20. The basic inputs you need are straightforward. Purchase price of the land, your planned down payment percentage, the interest rate the lender is quoting you, and the loan term. Some calculators also ask for property taxes, insurance, and HOA fees if applicable, though vacant land usually doesn't have HOA unless it's within a subdivision that's already been developed. Plug those in, hit calculate, and you get a monthly payment estimate. Done.
Running Your Numbers with a Buying Land Loan Calculator
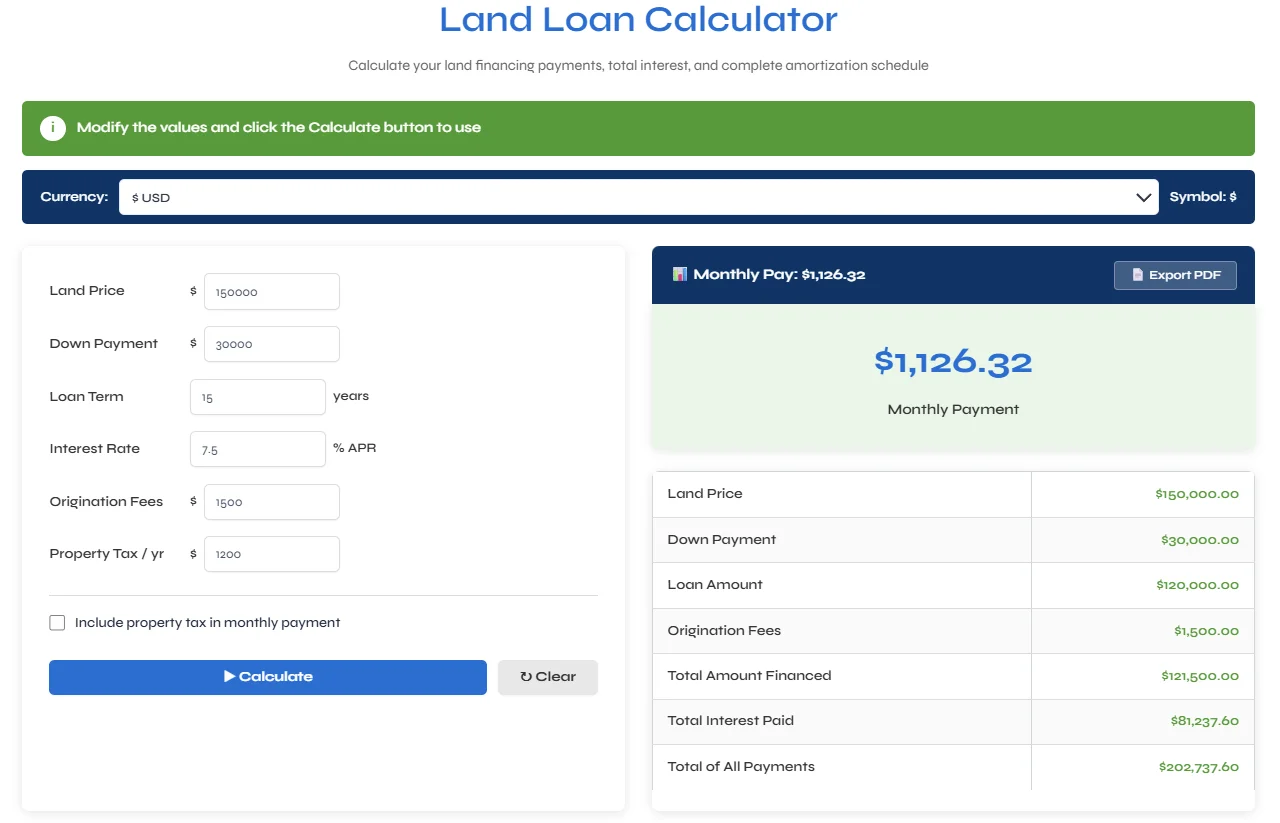
Here's what happens when you actually use one. Open the tool and start entering numbers in this order because it matters less than you'd think but people do it wrong anyway. Put the total land price first. Then enter your down payment as a dollar amount rather than a percentage if the calculator allows both options. I've seen people accidentally enter 20 as the down payment dollar amount on a $200,000 lot and wonder why the math looked insane. Switch to percentage mode after you've confirmed the dollar figure matches what you actually plan to put down. The interest rate field is where most errors creep in. If your lender gave you a quote of 8.5%, don't round it to 8% or 9%. Land loan rates vary wildly by lender, credit score, loan-to-value ratio, and whether the land is improved or unimproved. A 0.5% difference on a $150,000 loan over 20 years changes your monthly payment by roughly $60. Over the life of the loan that's $14,400. Enter the rate exactly as quoted, or if you're shopping around, run the calculator three or four times with different rates to see the spread. Loan term is another thing people gloss over. The standard for land loans is 15 to 20 years, sometimes 30 if the lender is feeling generous and your credit is solid. Shorter terms mean higher monthly payments but significantly less interest paid. I had a client once who picked the 30-year option to keep payments low, then tried to refinance into a construction loan six months later and got hit with two sets of closing costs. He ended up paying an extra $8,000 in fees because he hadn't mapped out his exit strategy before locking in the initial loan.
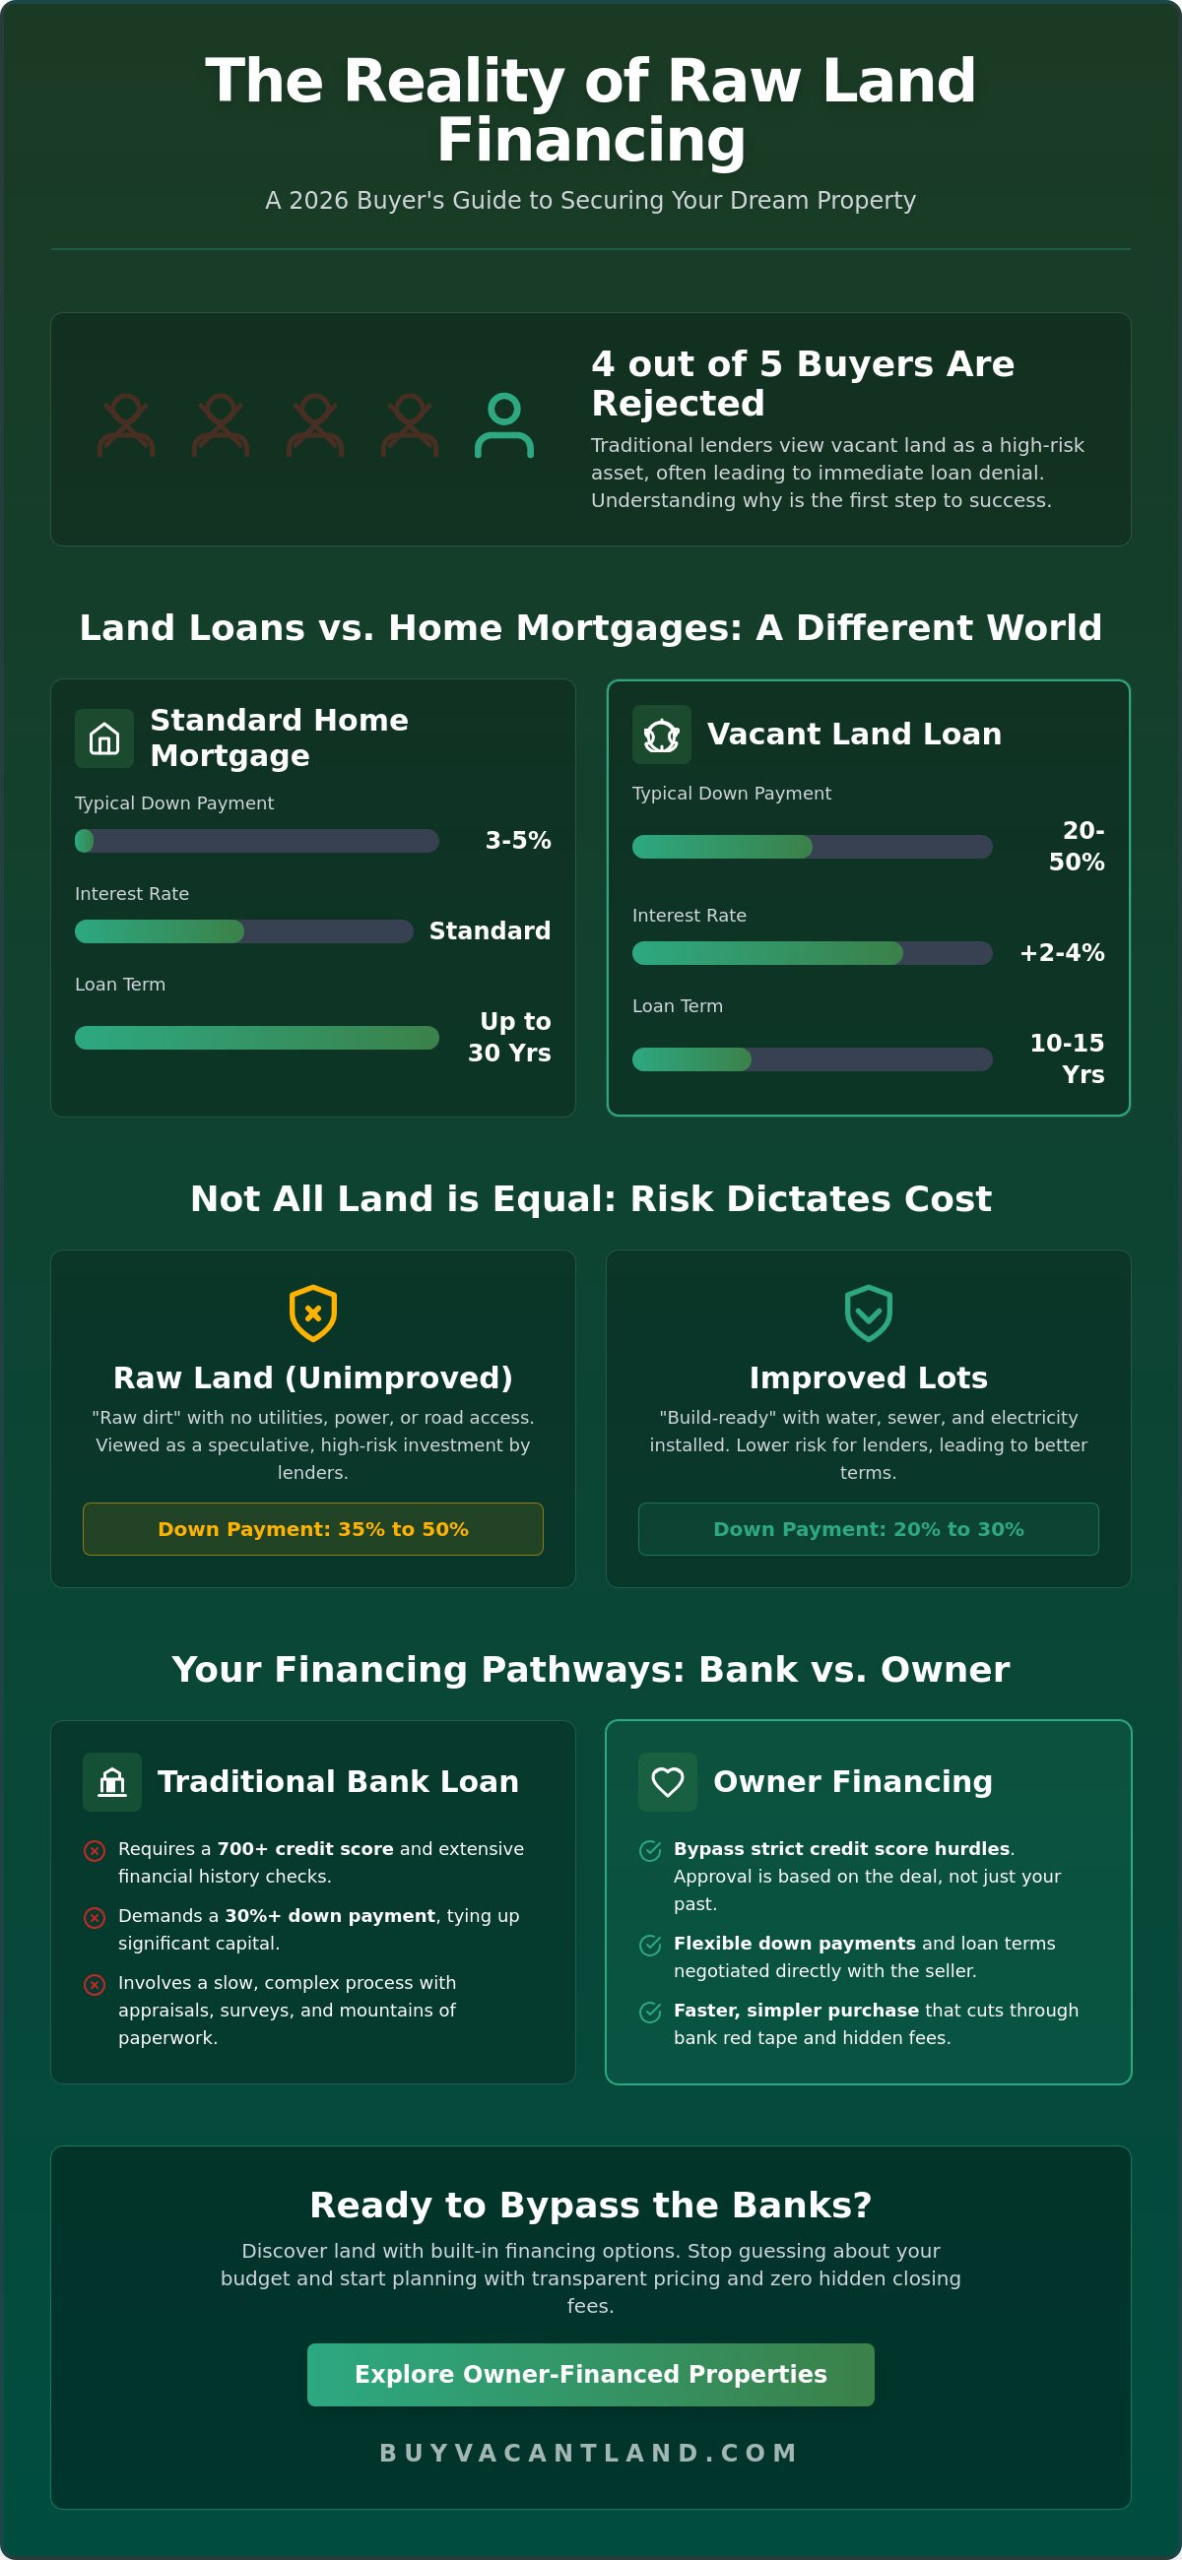
Here's a realistic scenario I deal with regularly. Say you're looking at a $120,000 parcel, putting 25% down at $30,000, with a 9.25% interest rate over 20 years. The calculator spits out a monthly payment around $890 before taxes and insurance. But then the appraiser comes back and values the land at $105,000 because it's sloped and has poor access. Now your loan-to-value ratio is based on the lower appraised value, the lender may require a larger down payment to make up the gap, and your monthly payment jumps to roughly $1,020. The calculator couldn't predict that. You have to factor in appraisal risk separately. One edge case that trips people up constantly involves perc tests and soil conditions. In rural areas, the bank will often require a successful perc test before they'll even consider the loan. If the soil fails, the land can't support a septic system, and the value drops to near zero for residential purposes. I had a buyer who ran the numbers on a beautiful wooded parcel showing a comfortable payment, closed the deal, failed the perc test, and was stuck with a loan on land that was essentially unbuildable. The calculator had no field for "perc test result" because obviously it doesn't. Before you commit, get the perc tested and the soil evaluated. It costs a few hundred dollars and saves you from walking away with a $40,000 problem. Another counter-intuitive thing about land loans: the down payment requirement goes up, not down, as the land becomes more attractive. Prime residential lots in growing suburbs might need 35 to 50% down because lenders see them as high-value collateral but also as speculative investments. Remote raw land with no utilities nearby often gets treated similarly, but for different reasons. The lender views remote unimproved land as harder to liquidate if you default, so they stack the risk with higher equity requirements. Don't assume a cheap parcel means easier financing. It usually means the opposite.
Get the Full Details
There are also limitations you should know about. Most free online calculators don't account for loan origination fees, which on land loans can run 1 to 3 points of the loan amount. On a $90,000 loan at 2 points, that's $1,800 you need to bring to closing on top of your down payment. Some calculators let you add closing costs as a separate field. If yours doesn't, factor it in manually by multiplying the loan amount by 0.02 and adding that to your total cash needed at closing. Land loan calculators also don't reflect the fact that many lenders require your debt-to-income ratio to be under 43%, sometimes lower for land-only loans. If you have student loans, car payments, and credit card minimums, your qualifying payment will be smaller than the calculator suggests. Run your DTI through your lender's underwriting guidelines before you fall in love with a property based on a spreadsheet number. If you want something more thorough than a free web calculator, there are downloadable spreadsheets that let you model multiple scenarios side by side. You can adjust down payment, rate, term, and closing costs all at once and see how each variable moves the monthly payment. I use a custom Excel file that includes columns for lender fees, title insurance estimates, survey costs, and perc test expenses. It takes about 10 minutes to set up once and then saves you from getting blindsided by the actual closing costs that the basic calculator ignores.
The bottom line is that a buying land loan calculator is a starting point, not a decision tool. It tells you what the payment would look like under ideal conditions. Real conditions involve appraisal gaps, perc failures, higher down payment requirements, and closing costs that the simple calculators don't include. Use it to get in the right neighborhood of numbers, then verify everything with a lender who actually understands land loans before you make an offer.