Understanding Reconciliation Math
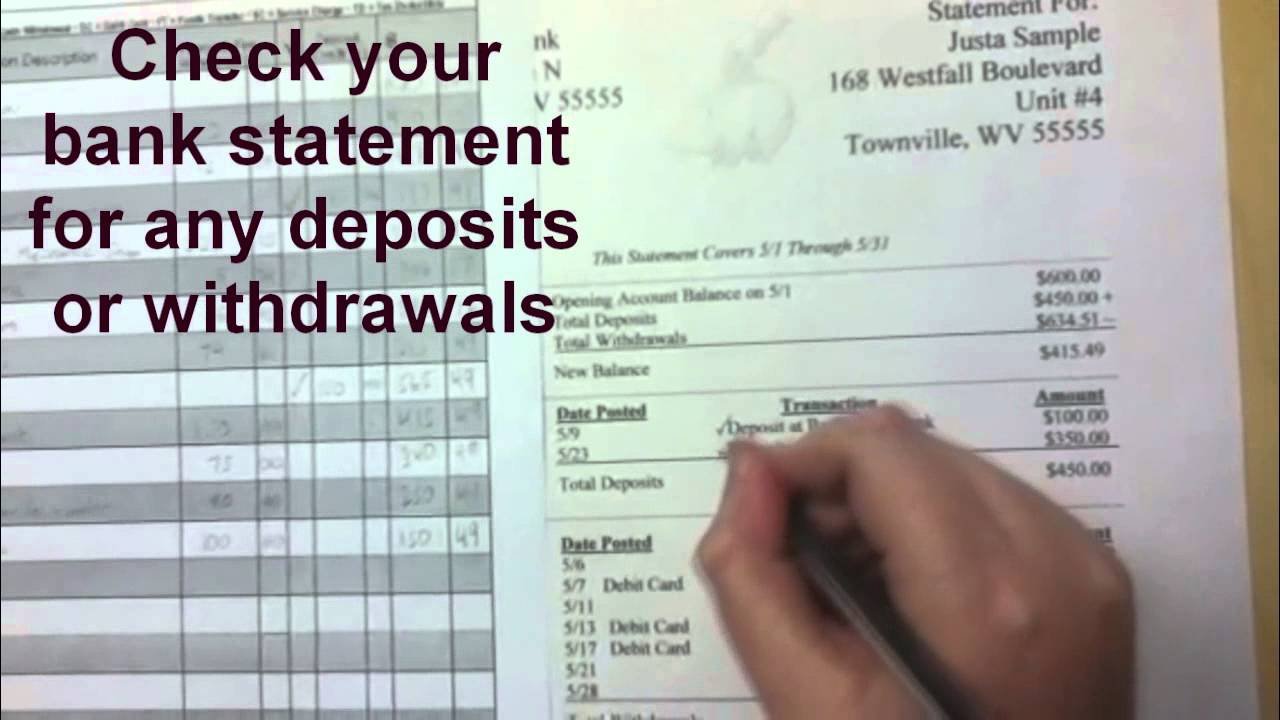
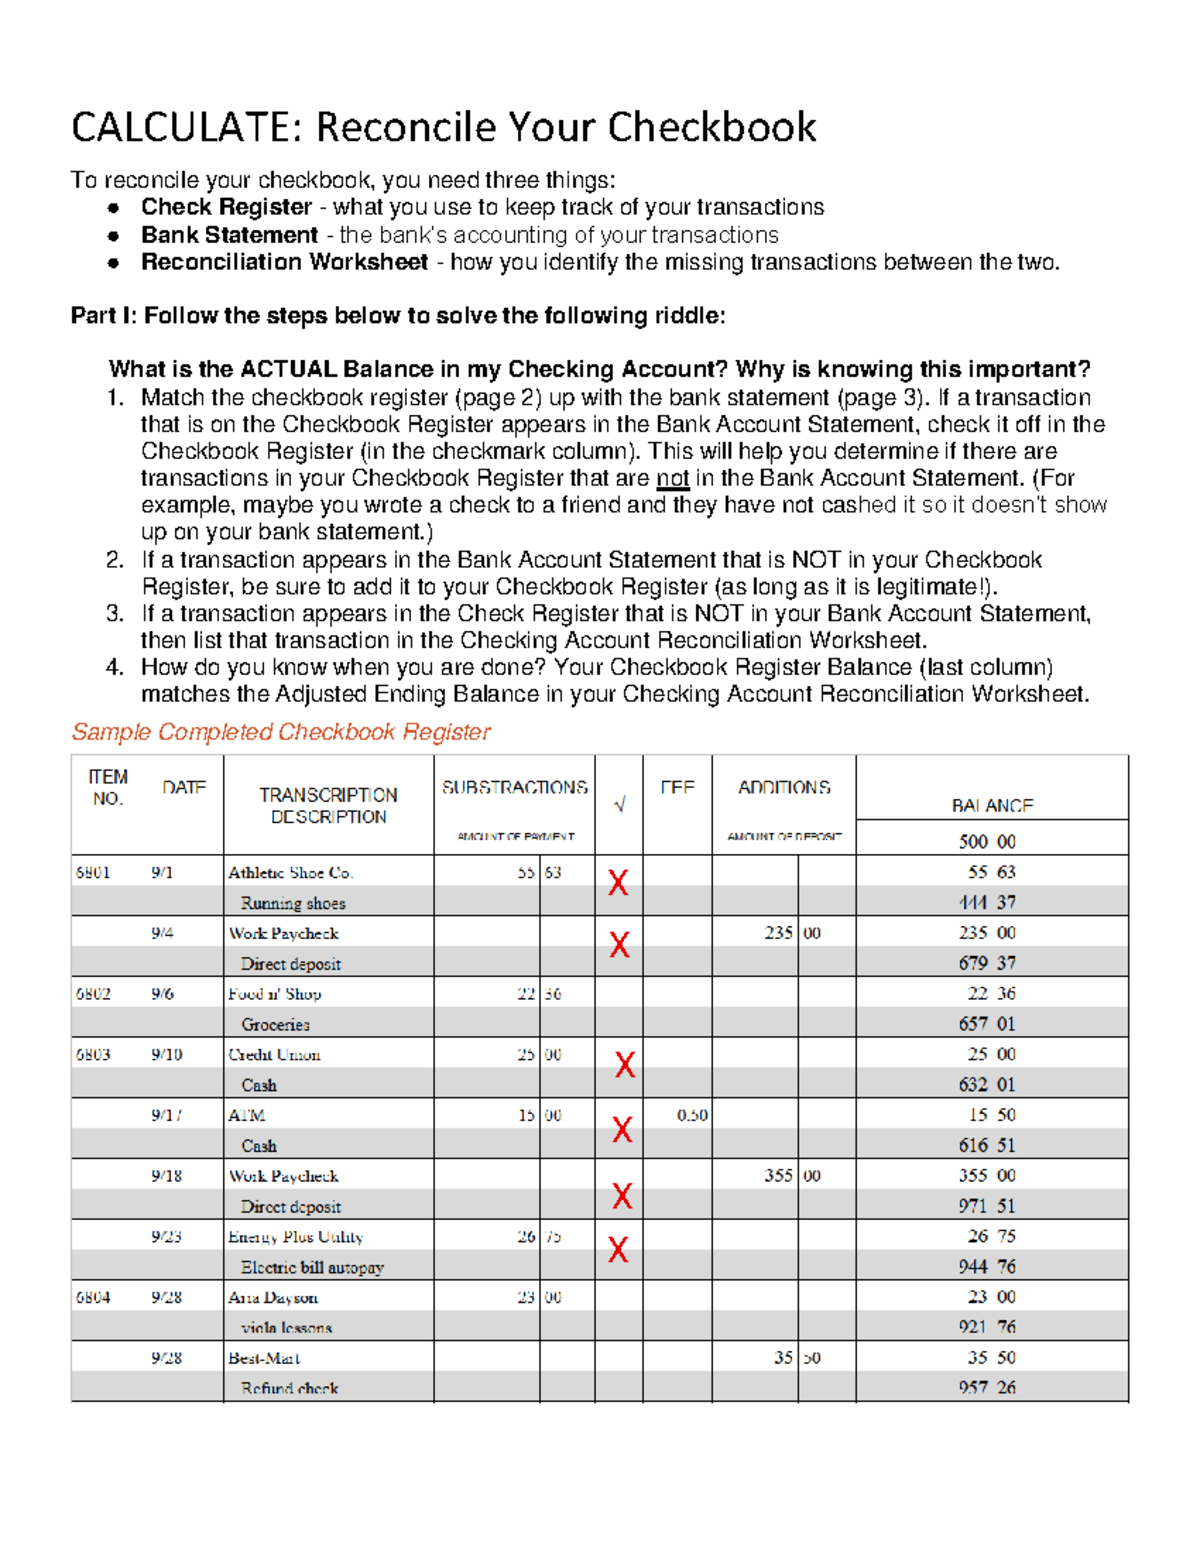
Most people think balancing a checkbook is just subtracting your deposits from your withdrawals. It's more complicated than that, especially when your bank statement doesn't match your own records. The standard method involves comparing your register against the bank's statement line by line, identifying what's different, and figuring out why. When you're working through the math, you start with your bank statement ending balance and adjust it. Then you do the same with your register balance. Both numbers should land on the same figure at the end. If they don't, something got missed or recorded wrong. The actual formula looks like this. Bank statement balance plus deposits in transit minus outstanding checks equals adjusted bank balance. Your checkbook balance plus any interest or credits the bank added minus any fees or automatic debits you didn't know about equals your adjusted book balance. Both adjusted numbers need to match.
I ran into this a while back with a client who had been reconciling monthly for years. Her register showed $4,312. She was pulling her hair out because the bank said $4,187. A thirteen dollar gap that refused to go away no matter how many times she recalculated. We spent two hours going through receipts. In the end, it turned out she'd written a check for $6.50 to a charity drive and somehow entered it twice in her register, once as positive and once as negative. So she'd subtracted it twice but the bank had only subtracted it once. The net effect created a discrepancy that looked way bigger than it actually was. Sometimes the problem isn't the math. It's the recording. Here's something most beginner guides won't tell you. The order in which you tackle discrepancies matters more than people realize. Most folks start by hunting for missing deposits. That's usually the wrong move. Outstanding checks are far more common, so verifying those first saves time. You'll often find that three or four uncashed checks account for the entire difference, and once you note them down, the rest becomes obvious. Another thing nobody mentions. Rounding differences. If you're using a spreadsheet or app that keeps decimals to three places, your manual calculations might show a difference of a few cents that isn't actually a real problem. Banks truncate or round at the cent level. Your register might not. A one or two cent mismatch after everything else reconciles is usually just a rounding artifact, not an error.
Let me walk through a real example. Say your bank statement shows an ending balance of $2,847. You have three deposits in transit totaling $620. Your outstanding checks add up to $315. So the adjusted bank balance is $2,847 plus $620 minus $315, which gives you $3,152. Now look at your register. You have $2,980 in it. The bank added $12 in interest and charged a $5 service fee that you hadn't recorded. Your adjusted book balance is $2,980 plus $12 minus $5, which is also $3,152. Both sides match. You're done. Now here's where it gets messy. Recurring automatic payments. I had a situation where a client's gym membership auto-deducted on the 15th but their statement date was the 28th. They hadn't recorded it because they never received a paper check. Two months in a row they thought their checkbook was unbalanced by the membership amount. The fix was setting a reminder to log recurring transactions on the day they post, not the day they were authorized. The timing difference between authorization and posting is something that trips people up constantly. There are tools that can help with this. Spreadsheet templates that auto-calculate both sides and highlight mismatches save a lot of manual work. I've used simple Excel sheets where column A is the bank statement, column B is the register, and column C automatically flags any line that doesn't appear on both sides. Once set up, reconciliation that used to take forty-five minutes takes about ten. The setup itself takes maybe twenty minutes, so you break even pretty quickly.
Get the Full Details

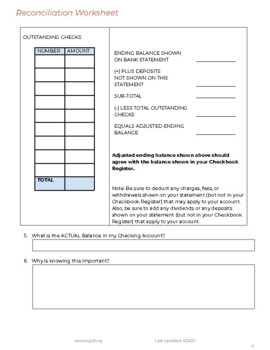
The biggest limitation with any reconciliation approach is that it only works if your starting data is accurate. If you've been skipping entries or guessing at amounts for weeks, no amount of clever math is going to fix that. You need to go back and correct the source first, then reconcile. Trying to force a reconciliation with bad data just hides the problem instead of solving it. Another issue is that some bank fees don't show up on your statement until the following month. You might reconcile in January and feel good about it, then see a $12 fee pop up on your February statement that you never recorded. This is normal. It just means your reconciliation wasn't wrong, it was incomplete. The cleanest approach is to treat each month as its own cycle and not try to carry forward adjustments from previous months unless absolutely necessary. If you're doing this manually and want a structured worksheet, there are templates available online from banking institutions and financial education sites. Search for a bank reconciliation worksheet PDF and you'll find formats that match most standard checking accounts. The key is picking one that has separate sections for bank-side adjustments and book-side adjustments, since confusing the two is the most common mistake people make.
Some people skip manual reconciliation entirely and let their banking app do it automatically. That works fine for simple accounts with no outside checks or unusual deposits. Once you start dealing with things like third-party payment apps, mobile deposits that haven't cleared, or split transactions, the automated tools often fall short and you end up doing the work manually anyway. Knowing how to do it by hand is useful even if you mostly rely on automation.