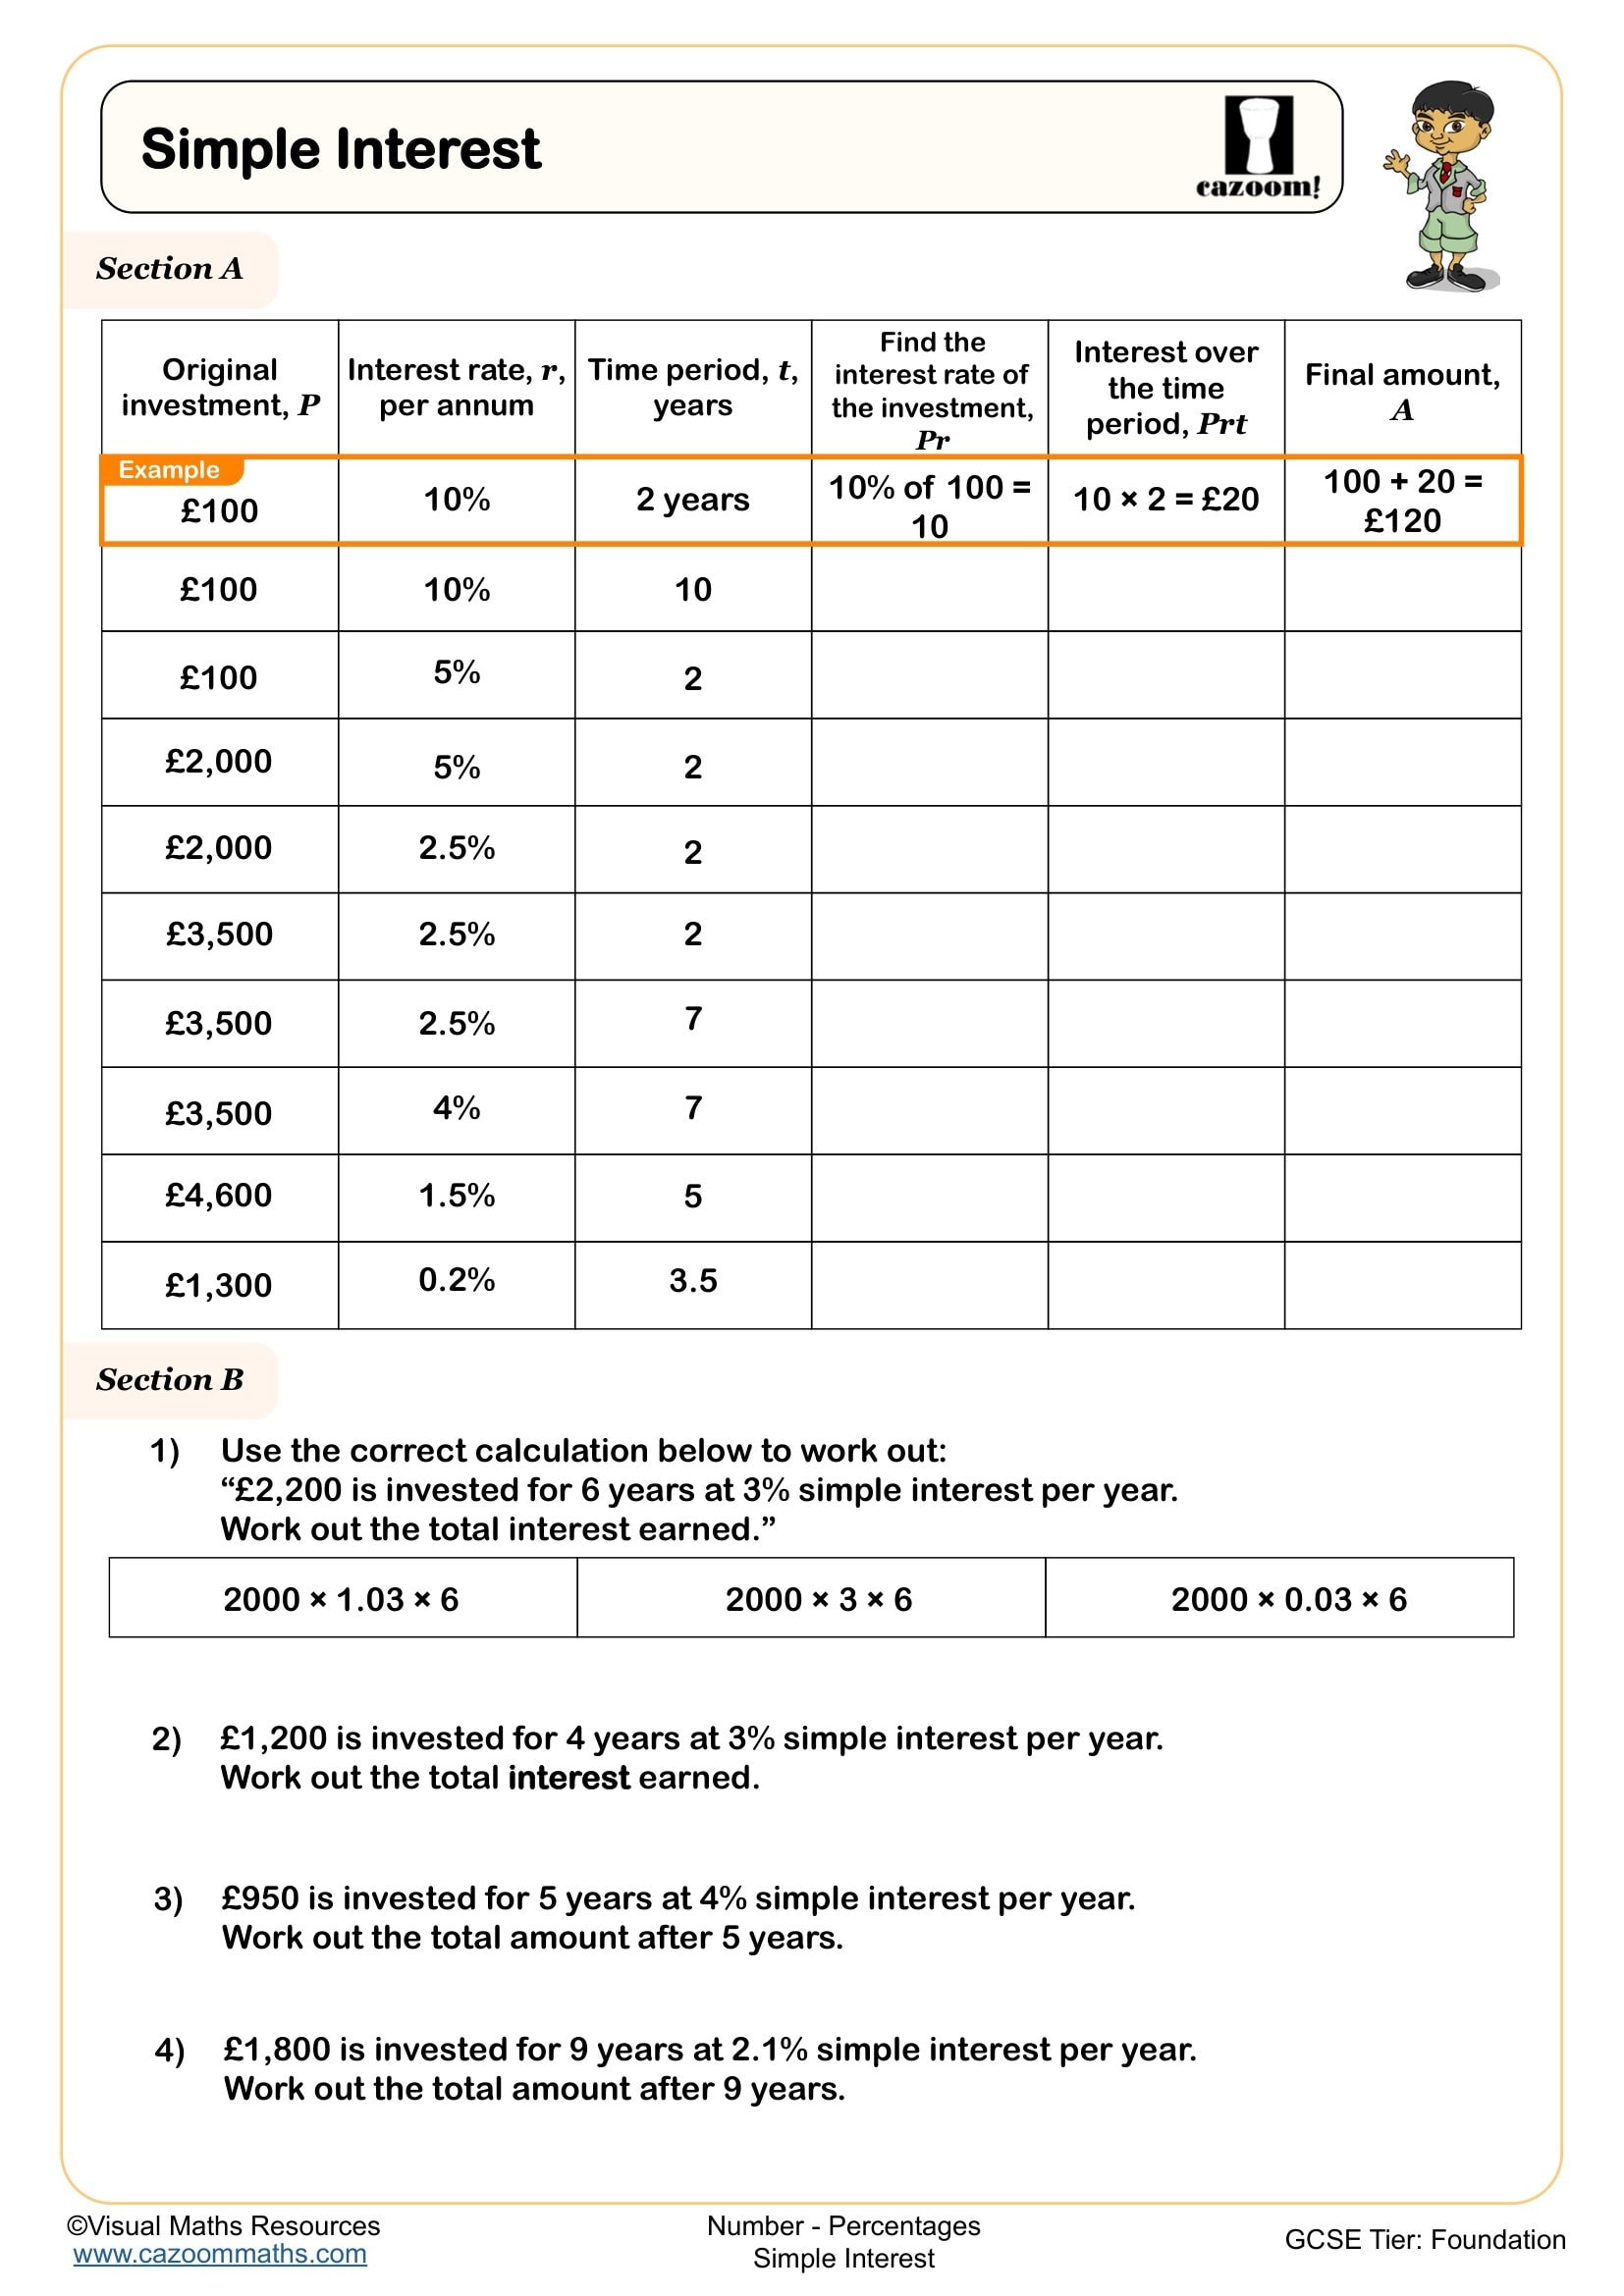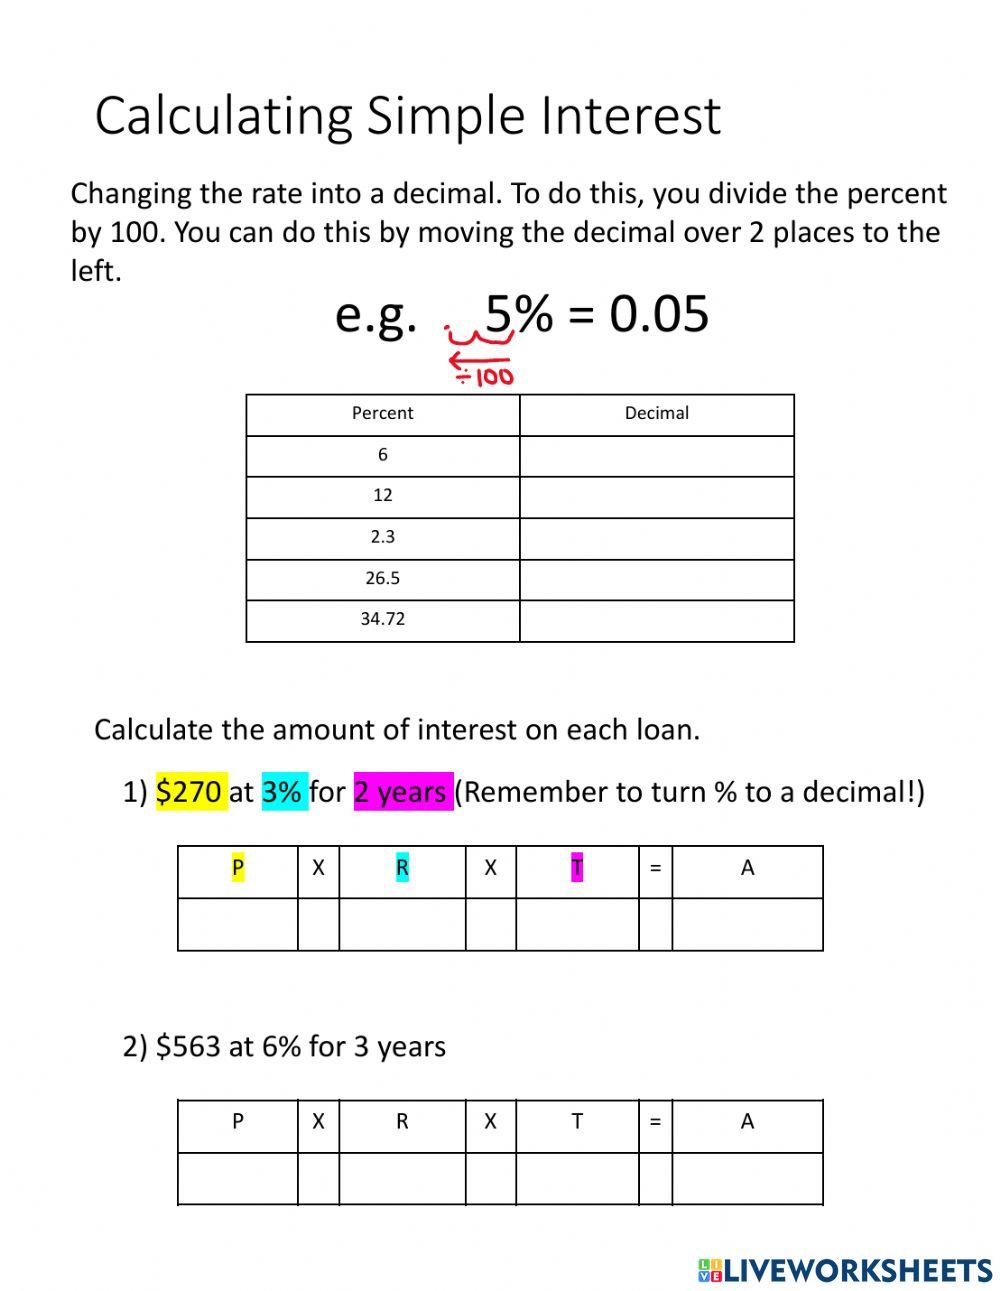
Simple interest doesn't require a finance degree, but getting it right on paper takes a method that won't break when the numbers get weird.
Most worksheets ask you to plug values into I = P × r × t. That equation is accurate enough for textbook problems where the principal is a round number, the rate is a clean percentage, and the time period is measured in whole years. Real situations are rarely that cooperative. I have sat through hours of grading sessions where half the class turned in answers that looked correct until you checked the units. A rate listed as 4.5% per month used as an annual rate is the most common error I see, followed by time periods expressed in days that nobody converted to fractions of a year. Start with the core formula and make sure every variable has a defined unit next to it. P is the principal amount in dollars or whatever currency you are using. r is the annual rate expressed as a decimal, not a percentage. t is time in years. If your problem gives you months or days, you need a conversion step baked into the worksheet layout. I usually add a small note section below the formula that explicitly states the conversion factors: months divided by 12, days divided by 360 or 365 depending on what convention your course uses. The day-count convention matters more than most students realize, and it is almost never mentioned until someone loses points on a problem involving partial years. Here is a practical example. Say you borrow 15,000 at 6.2% annually for 14 months. You convert 6.2% to 0.062. You convert 14 months to 14/12 which equals approximately 1.1667 years. Multiply 15,000 by 0.062 by 1.1667. The interest comes out to about 1,085.10. The total amount owed is 16,085.10. That is straightforward until you hit a case where the rate is quoted as a daily periodic rate, which happens more often in informal lending or payday-style arrangements.
I ran into a problem last semester where a worksheet listed the rate as 0.08% per day and expected students to calculate interest over 90 days using the simple interest formula. Students who treated 0.08% as an annual rate got wildly wrong answers. The worksheet did not flag the periodic nature of the rate anywhere in the problem statement. I had to tell my students to read the label attached to the percentage like it was the fine print on a loan agreement. The correct approach was to multiply 0.0008 by 90 to get the effective decimal rate over the period, then apply it to the principal. The result was exactly 1,080 in interest on a 15,000 principal. Same dollar amount as the earlier example, different path to get there.
What Most Worksheets Get Wrong
They present clean numbers and ignore the fact that real interest calculations often involve partial periods, rounding conventions, and rate conversions that change the answer significantly. A 90-day period calculated on a 360-day year versus a 365-day year produces a different result even when every other variable is identical. In commercial lending, the 360-day year is standard because it simplifies calculations. Academic worksheets sometimes mix conventions without warning, which creates confusion that has nothing to do with understanding the formula and everything to do with following an invisible set of assumptions. Another issue is how worksheets handle the final answer. Some expect rounding to the nearest cent after every intermediate step. Others want you to carry full precision through the calculation and round only at the end. The difference can be a dollar or two on larger principals. I recommend rounding only at the end unless your instructor explicitly requires intermediate rounding, because each rounding step introduces a small error that compounds if you are doing multiple calculations in sequence.
Get the Full Details

Using This Worksheet Approach Effectively
When you create your own Calculating Simple Interest Worksheet or work through an existing one, build a consistent layout. Write down what you know first. List P, r, and t separately with their units. Perform any unit conversions before touching the formula. Calculate the interest. Calculate the total if asked. Check whether the answer is reasonable. If you borrow 1,000 at 10% for one year and the interest comes out to 50, you made a mistake somewhere. Simple arithmetic errors are easy to miss when you are rushing. The formula itself has real limitations that worksheets rarely address. Simple interest assumes the interest does not compound. It does not account for fees, penalties, or changes in the principal balance during the term. If you are making partial payments, the interest calculation changes because the principal decreases. Some worksheets introduce this concept with problems where a payment is made mid-term, but the formula still treats the original principal as unchanged unless you adjust it manually. I once had a student submit a worksheet where the problem included a partial payment after six months and the student applied the full principal for the entire term. The answer was technically consistent with the formula but completely wrong for the scenario. You need to recalculate interest in segments when the principal changes. For cases involving partial payments or changing principals, simple interest worksheets become inadequate and you should switch to a day-by-day or period-by-period calculation method. The math is the same, just repeated across segments. It adds time but eliminates the error that comes from assuming a static principal over a dynamic timeline.
Where to Find and Adapt These Worksheets
There are dozens of free printable sets online from educational sites, but most of them reuse the same problems with swapped numbers. The better ones include a mix of straightforward applications and the trickier edge cases I mentioned here. When you download a Calculating Simple Interest Worksheet, skim through every problem before you start. Identify which ones involve unit conversions, which ones involve partial payments, and which ones might be testing your awareness of day-count conventions. The problems that look easiest often hide the most subtlety. If you are building your own set for study or teaching purposes, include at least one problem with a monthly rate, one with a daily rate, one with a partial payment, and one where the time period requires a day-count choice. Those four problem types cover the scenarios where students most commonly lose points, and they force you to think about the formula rather than just applying it mechanically. The extra effort in worksheet design pays off because it mirrors the kind of mistakes that show up on exams and in actual financial work.