How to Actually Pass the California Life and Health Licensing Exam
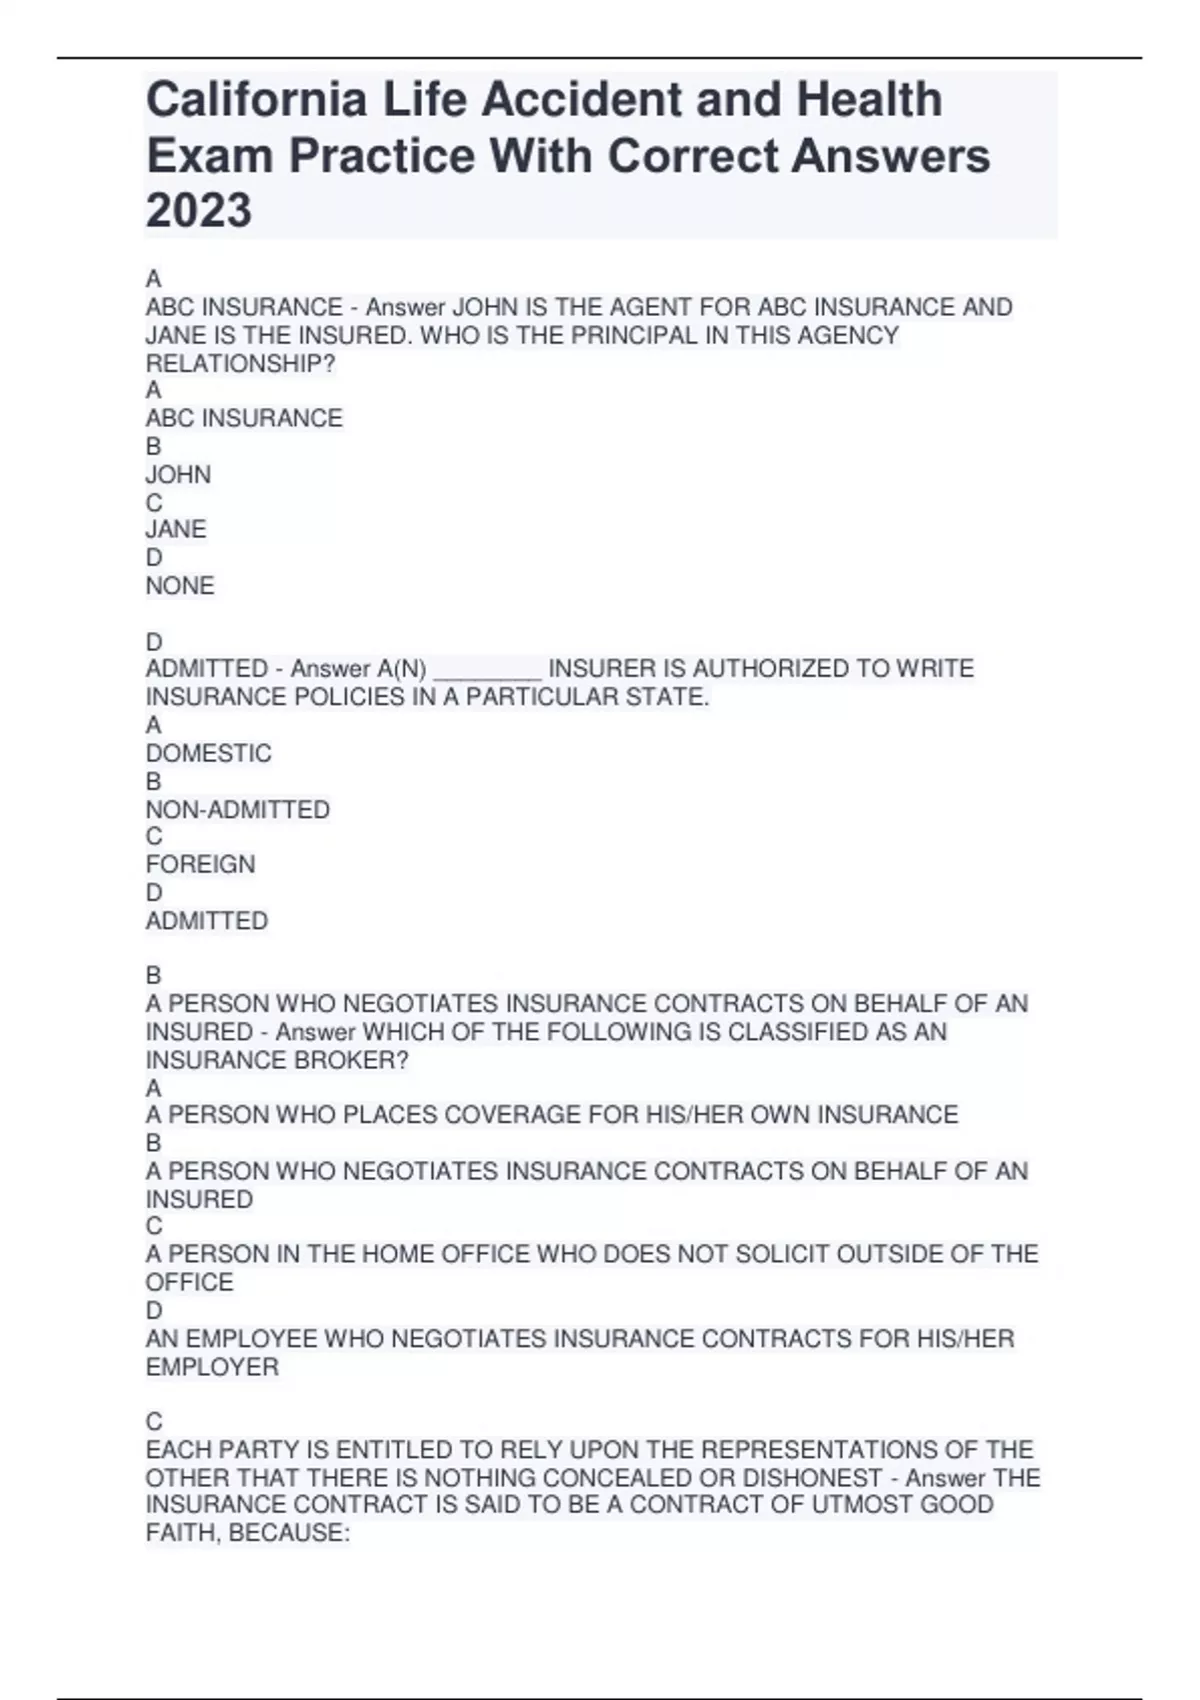
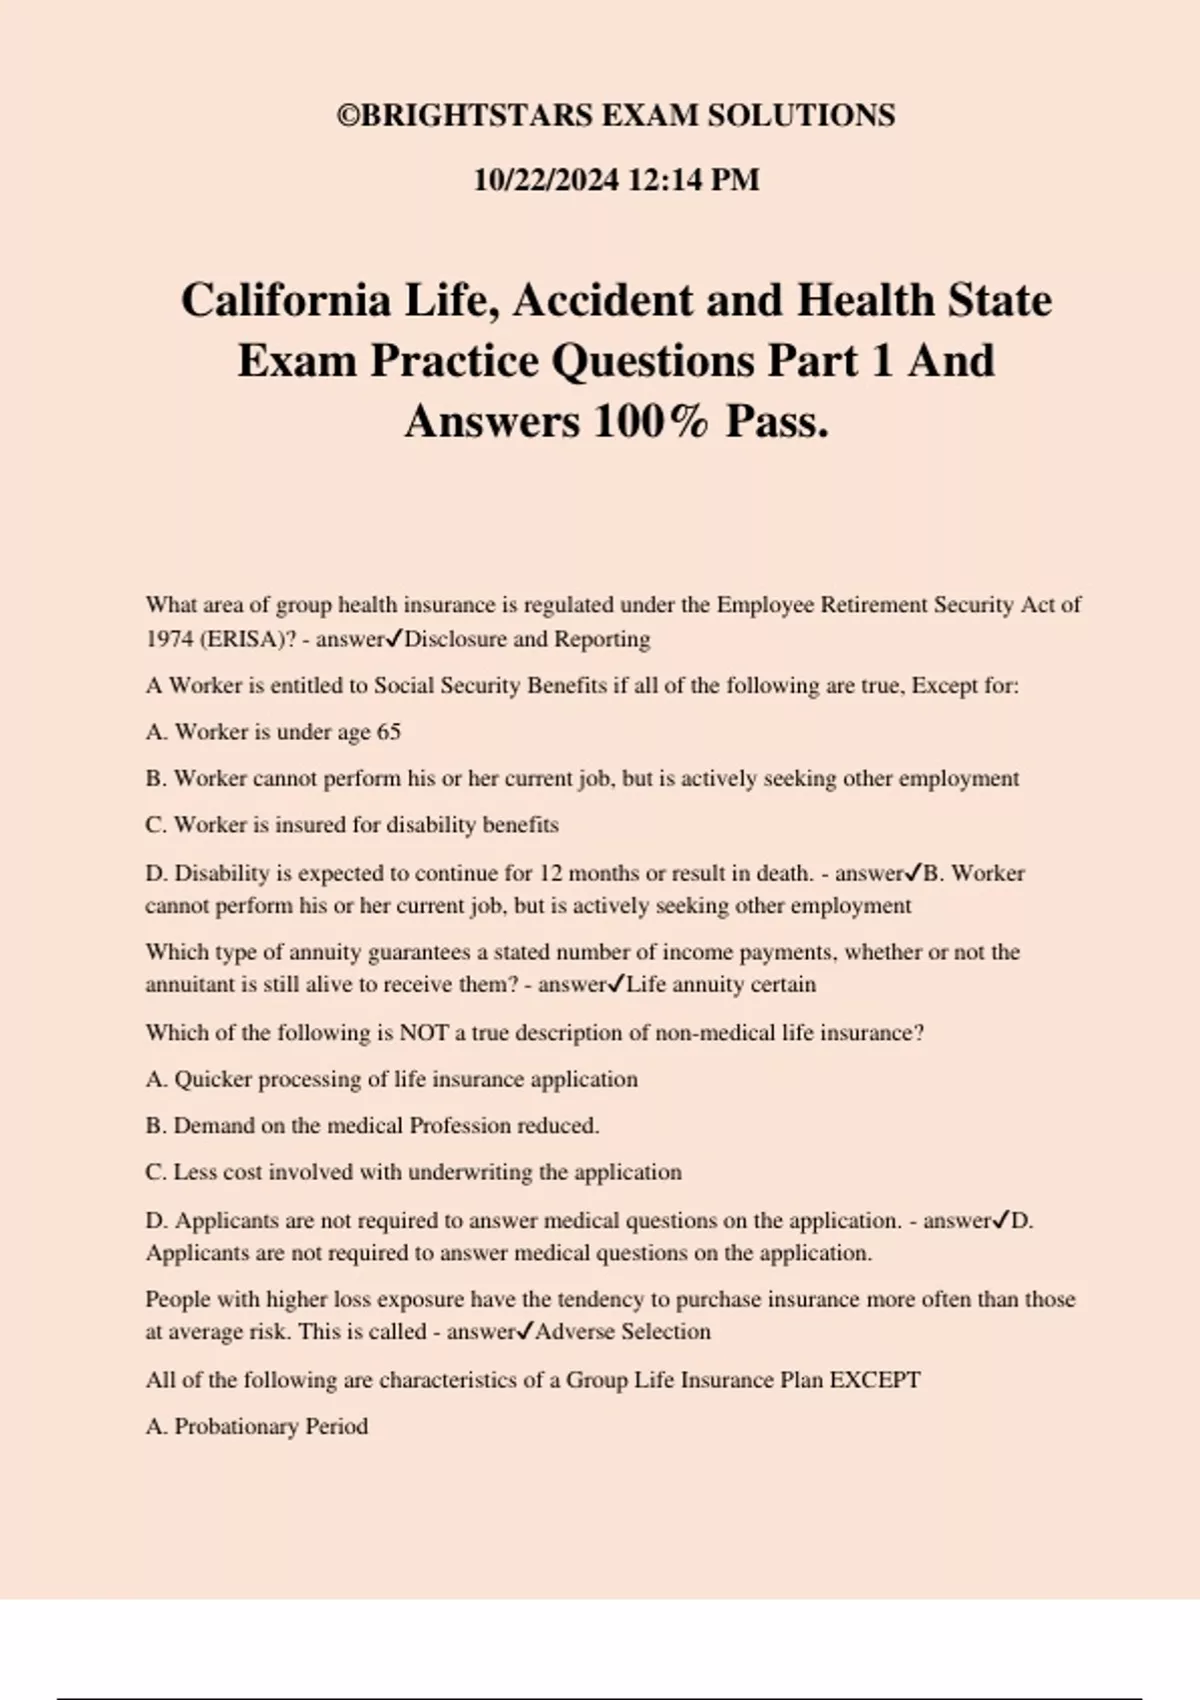
The California Life and Health Practice Exam isn't something you just Google and wing it with. It's a 2-hour computer-based test with about 100 to 120 scored questions, plus some unscored items that get mixed in. The state of California has specific requirements that differ from most other states, and if you go in with generic study material, you'll fail questions you'd get right in another jurisdiction. Here's what I'd actually use. The Pre-License Exam Prep course through the DIIR (Department of Insurance and Insurance Regulation) is the baseline. Then there's Quizlet sets that are updated regularly by people who actually took the exam, and the state's own sample questions posted on their website. The DIIR website has a practice module that mirrors the actual testing environment. Use it before spending money on anything else. Most people don't realize that California tests on its own insurance code sections, not just general principles. I went through three different prep courses and still got burned on questions about California-specific beneficiary laws and policy replacement regulations. The state loves to test on the differences between California law and the NAIC model code.
What the Exam Actually Covers
The exam breaks into four main areas, roughly weighted by how much they appear on the test. Life insurance makes up about 30 percent of the questions. This includes policy types, provisions, riders, beneficiary designations, and the mechanics of how policies work end to end. Health insurance is another 30 percent, covering medical insurance products, HMOs, PPOs, Medicare supplement policies, and long-term care considerations. Annuities account for about 20 percent, and ethics, regulation, and unfair trade practices round out the rest. Here's the thing nobody tells you: the math portion is simpler than you expect. They're not going to make you do complex premium calculations by hand. They want to know if you understand what a premium is, how it's determined, and what changes it when policy terms shift. That's it. Know the tables, know the concepts, skip the panic about math anxiety.
How to Study Without Wasting Your Time
Start with the DIIR's recommended pre-licensing course. California requires a minimum number of hours depending on whether you're going for life-only or life and health. The life and health combination is typically 75 hours of coursework. Don't skip the coursework thinking you can cram. The volume of material makes that impossible in any realistic timeframe. After you finish the course, take a full-length practice exam under timed conditions. I did this before my actual exam and scored around 68 percent. That's not passing territory, but it told me exactly where my gaps were. I spent the next two weeks focusing only on weak areas instead of re-reading material I already understood. This approach cut my study time from roughly three weeks down to about ten days. When you're doing practice questions, don't just check if you got them right. Read the explanation for every wrong answer, even the ones where you guessed correctly and happened to pick the right letter. That's how you catch patterns in how the state phrases things.
Get the Full Details
Specific Edge Cases That Trip People Up
I remember one question that stayed with me for months after I passed. It was about a policyholder who wanted to change the beneficiary on a life insurance policy, but the original beneficiary had already vested their interest. The answer wasn't the obvious one about "the policyholder can always change beneficiaries." In California, once a beneficiary interest vests, the policyholder cannot change it without the beneficiary's consent unless the policy specifically reserves the right of revocability at issuance. I got this wrong on my first practice exam because I was thinking in general insurance principles, not California-specific code. Another common trap involves the free look period. California gives a 30-day free look period for most life and health policies, which is longer than the standard 10 to 21 days in many other states. Questions will try to make you second-guess this number, so commit it to memory early.
What the Testing Environment Is Actually Like
When you show up to the testing center, you'll go through a standard check-in. No electronics, no notes, no calculators — though you won't need one. They provide a small whiteboard and marker for scratch work. The testing software lets you flag questions and come back to them later, which is important because some questions are deliberately tricky and you don't want to spend eight minutes on one when you have 90 minutes to get through everything. My advice on the exam itself is simple. Read every answer choice before you pick one. California exam writers put two answers that look correct but one that's more precisely correct according to their code language. If you see an answer that says "always" or "never," it's probably wrong. Insurance regulation is almost never absolute.
What Falls Short With Common Prep Methods
Most commercial prep courses are designed for a national audience and use the NAIC model as their base. That means they'll teach you the standard 10-day free look period and standard contestability clauses without highlighting the California exceptions. I wasted a full week studying material that didn't match the actual exam. The workaround was to cross-reference everything against the California Insurance Code sections listed on the DIIR website after each practice test. Flashcard apps are decent for memorization but terrible for understanding the nuance. You can memorize that the grace period is 30 days for life insurance in California, but if a question asks what happens when a premium is paid during the grace period and the insured dies, the answer depends on whether the policy was in force at the time of the original premium due date. Apps won't teach you that context. If you're someone who learns better from verbal explanation than reading, the YouTube channels that walk through practice questions are actually useful. But stick to ones posted within the last two years. Insurance regulation changes, and old videos will have you studying requirements that no longer apply.
The Bottom Line
The exam is passable with focused preparation. The hard part isn't the difficulty level — it's the specificity of California law. You need to study California, not generic insurance principles. Take the practice exam before you think you're ready, identify your gaps, and fill them. That's it. There's no trick, no shortcut around the actual content. It's just a matter of knowing what the state expects you to know and proving you know it on test day.