The Short Answer Is No, But Not For The Reason Most People Think
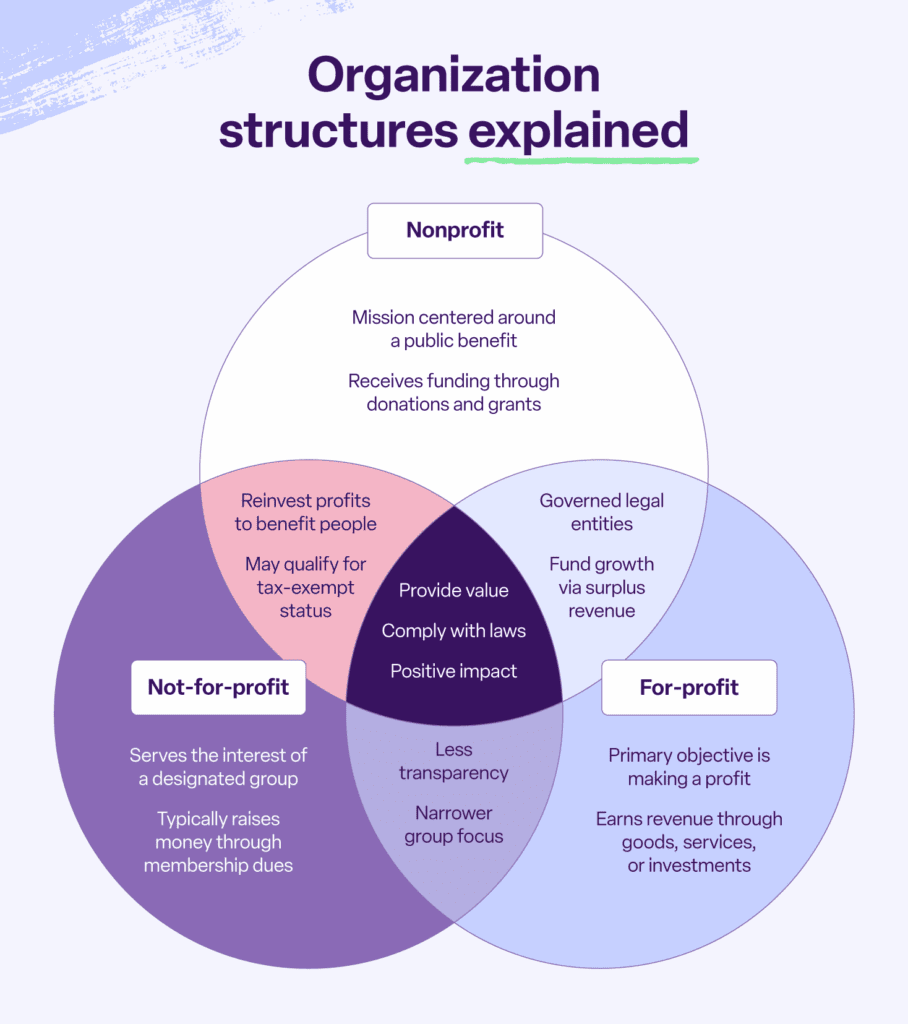
Anyone can file paperwork. The question is whether your business model can actually survive as a nonprofit. I've watched several founders go through this process and most of them didn't understand the constraints until they were already deep in it. Let me walk through what that looks like before we get into the nitty-gritty. The legal framework allows a for-profit entity to convert to a nonprofit organization, but the conversion itself triggers a chain of events most people don't anticipate. You need a qualifying purpose under section 501(c)(3) of the Internal Revenue Code — charitable, religious, educational, scientific, or literary. Something like a tech consulting firm doing work for private clients isn't going to cut it. A coding bootcamp that trains underserved communities in partnership with local governments, that's closer to the mark. The real friction point is distribution of assets. When you convert, all the equity in your existing business effectively disappears. You can't take money out. You can't sell shares. The assets become dedicated to the charitable purpose. If you've been building personal wealth through your company, that path ends the moment you file for nonprofit status. I worked with a founder who had been planning an exit strategy for a community health clinic for eight years, then decided to convert to 501(c)(3) right before a planned acquisition. He walked away from roughly $2.3 million in projected personal proceeds. He didn't fully factor this in until his lawyer showed him the asset lock clause in the conversion documents.
The Practical Pathway
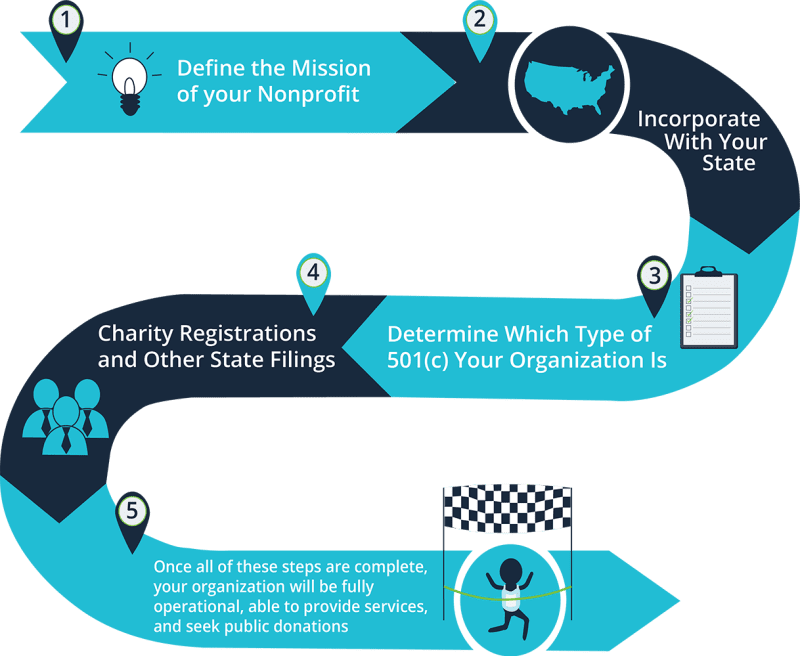
There are three main routes depending on where you're starting from. Route one: Incorporate as a nonprofit from scratch. This is the cleanest option if you haven't started operating yet. You file articles of incorporation with your state's secretary of state, draft bylaws, hold an organizational meeting, appoint a board, and then apply to the IRS using Form 1023 or the streamlined Form 1023-EZ if you qualify. The 1023-EZ is available if you expect annual gross receipts of $50,000 or less and assets under $250,000. The standard 1023 takes longer — six to twelve months depending on IRS backlog — and costs $600 in filing fees versus $275 for the EZ version. Route two: Convert an existing for-profit to a nonprofit. This is where it gets complicated. You'd typically dissolve the for-profit entity or merge it into a newly formed nonprofit. The IRS requires you to demonstrate that the conversion serves a charitable purpose and doesn't inure private benefit to any individual. This means a formal valuation of your existing business assets and careful planning around what happens to creditors, employees, and any remaining capital. Many states also have specific statutes governing nonprofit conversion, so you need to check your jurisdiction.
Route three: Operate as a for-profit with a charitable subsidiary. This is the compromise most people end up choosing without realizing it. You keep your for-profit entity and create a separate 501(c)(3) that does the charitable work. Your business can provide services to the nonprofit at fair market value, sponsor programs, or contract with the foundation. The downside is double compliance — two sets of filings, two boards, two tax returns. But it preserves your ability to generate personal income from the for-profit side.
Get the Full Details
What Nobody Tells You About the Operation
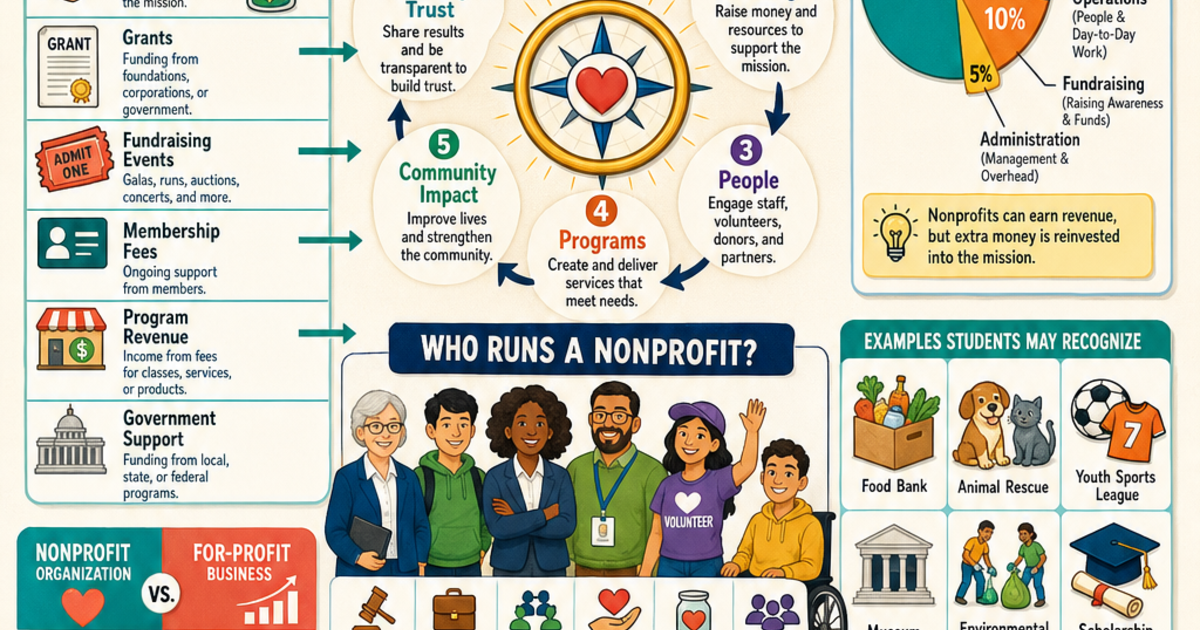
Running a nonprofit is structurally different from running a business in ways that affect daily decisions. You need a board of directors — at least three people in most states, though the IRS doesn't set a minimum, and you'll want more than that to avoid single-point-of-failure problems. Board members can't be paid for their governance work. They can receive reasonable compensation for actual services rendered, but that's a separate question with its own rules around reasonableness and documentation. Fundraising is a different beast from sales. Every dollar you solicit is subject to state charity registration requirements, and if you raise money across state lines you may need to register in each one. The federal side requires you to file Form 990 annually, which becomes a public document. Your compensation, your program expenses, your board members' names — all of it is visible. Anyone can pull your 990 from Guidestar or the IRS Exempt Organizations Select Check tool. This transparency constraint changes how you negotiate salaries, structure executive compensation, and even decide which vendors to work with. Here's a specific problem I ran into that most guides skip over: excess benefit transactions. If you pay yourself or a board member more than reasonable compensation for services, or if you provide below-market leases, loans, or other benefits to insiders, the IRS can impose excise taxes. The primary penalty falls on the individual who received the excess benefit — typically 25% of the excess amount — and if not corrected, it jumps to 200%. I had a client who was paying his nonprofit's executive director a salary that was 40% above what similar organizations in the region were paying. The IRS audit flagged it, and we had to restate three years of compensation data to demonstrate reasonableness. Took about three weeks and cost us roughly $8,000 in legal fees just to resolve it.
When Conversion Makes Sense and When It Doesn't
Conversion makes sense when your organization's primary mission is genuinely charitable and you're tired of trying to wrap charitable work inside a profit structure. It makes sense when you want access to grant funding that only goes to 501(c)(3) organizations. It makes sense when you need donors to write off their contributions, which requires actual tax-exempt status, not just a vague claim that you're doing good work. It does not make sense if you need flexibility to distribute profits, raise venture capital, or build personal equity. Nonprofits can't have owners. They can't issue stock. They can't distribute surplus revenue to anyone. If your business model depends on generating returns for investors or founders, keeping the for-profit structure is usually the right call. Hybrid models exist — L3Cs, benefit corporations, low-profit limited liability companies — but they come with their own trade-offs and aren't recognized for federal tax-exempt status. The IRS also monitors what they call "substantial non-exempt purpose." If more than an insubstantial part of your activities don't further your charitable mission, you risk losing your exemption entirely. I've seen organizations lose their status because their revenue came mostly from commercial activities that weren't substantially related to their exempt purpose. A museum that makes more money from its gift shop than from admissions and memberships might look fine on the surface, but the IRS looks at the overall picture. If the gift shop is serving a commercial function unrelated to education, it could trigger scrutiny.
The Financial Reality Check
Nonprofits aren't automatically tax-free. They're exempt from income tax on revenue related to their charitable purpose. Revenue from unrelated business activities — and there's a specific definition for that — can still be taxed. File Form 990-T if your unrelated business income exceeds $1,000 in a year. Many founders discover this after the fact when a fundraising gala, a merchandise sale, or a licensing deal generates taxable income they didn't plan for. Grant writing and donor management consume significantly more time than most people expect. A well-run nonprofit spends roughly 15 to 25 percent of its total budget on fundraising. If you're running a lean operation with a $200,000 budget, you should plan to spend $30,000 to $50,000 of it on raising the money you need. That includes staff time, events, grant applications, donor stewardship, and the software or consultants you might bring in. If you can't allocate that percentage, you'll struggle to sustain operations regardless of how good your mission is. Here's another practical constraint: insurance and liability. Nonprofits still need general liability, directors and officers coverage, and possibly cyber liability depending on your work. Premiums vary widely by activity, but a small nonprofit in a high-risk sector like youth services or healthcare should budget $5,000 to $15,000 annually for adequate coverage. I've seen organizations skip D&O insurance to save money, then face a board member lawsuit where the lack of coverage left individual directors personally exposed. That's a problem that takes years to unwind.
If You're Considering This
Get a qualified attorney who specializes in nonprofit law. Not a general practice attorney. Not a CPA who dabbles in this occasionally. Someone who handles nonprofit formation and compliance as a regular part of their practice. The difference in cost is real — expect to spend $3,000 to $8,000 on legal fees for a proper conversion — but the cost of getting it wrong is much higher. A bad conversion can trigger retroactive tax liability, excise penalties, or a failed IRS determination that wastes six to twelve months and forces you to start over. Your state's charity regulator matters too. If you plan to solicit donations in multiple states, factor in the registration costs and annual renewal fees. Some states charge modest filing fees. Others, like California, require annual financial statements and can impose penalties for late or incomplete filings. The California Registry of Charitable Trusts review process alone can take three to four months for new registrations. Most importantly, be honest about whether your organization actually needs nonprofit status. There are legitimate reasons to stay for-profit. There are also legitimate reasons to embrace the nonprofit path. The people who get into trouble are the ones who convert for the tax break or the prestige without understanding what the structure actually demands day to day.