How Capella's Financial Aid Actually Gets to Your Account
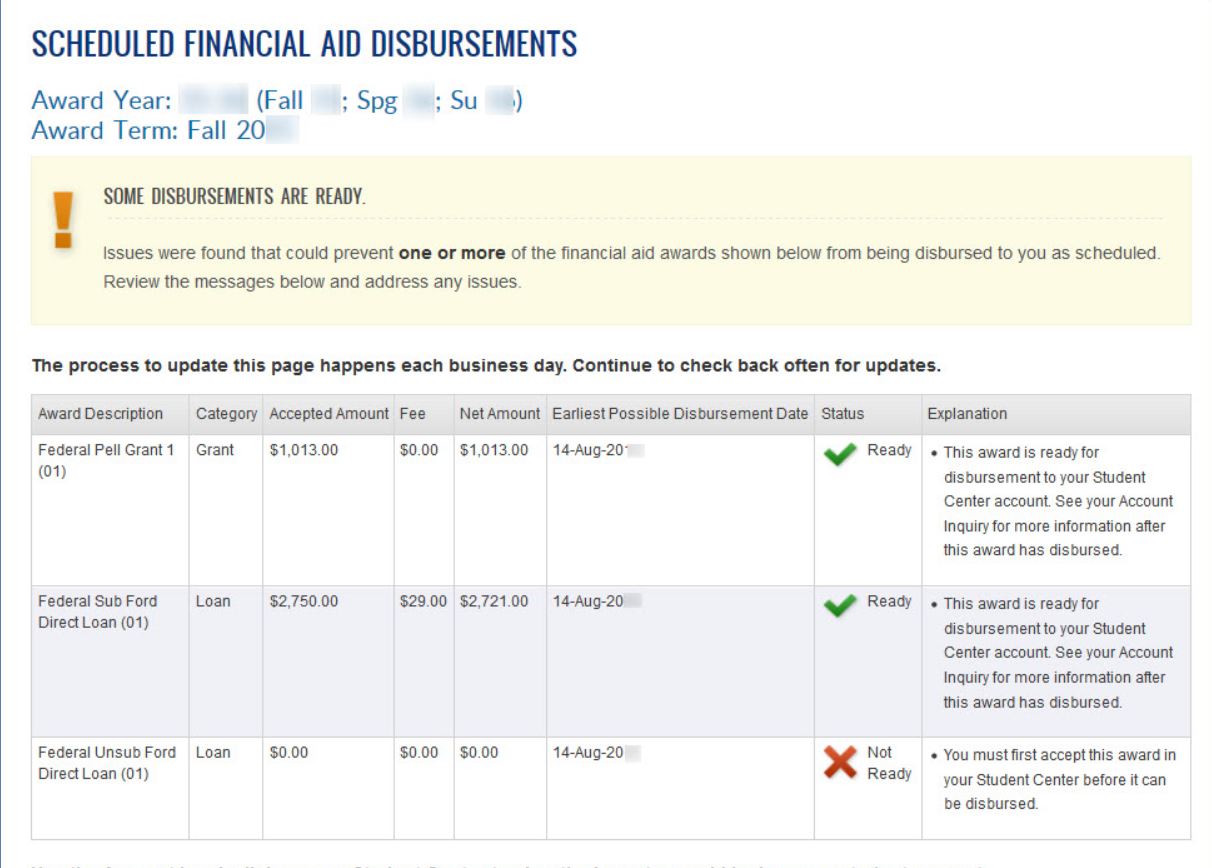
Financial aid doesn't just appear on your student account. It goes through a release process, and Capella handles it on its own schedule, which isn't always the same as what you see in the handbook. Here's how it works in practice. Before any disbursement happens, your aid package needs to be fully certified. That means all acceptance forms, master promissory notes, entrance counseling for federal loans, and satisfactory academic progress reviews are complete. If any one of those pieces is missing, the whole disbursement sits in a queue. I learned this the hard way during my second semester when my PLUS loan disbursement was delayed three weeks because I'd completed the MPN but never clicked through the annual renewal acknowledgment. The system doesn't warn you about this gap. It just silently holds the funds until the cycle runs again.
Understanding Capella Financial Aid Disbursement Dates
Capella operates on quarterly terms. Each term runs roughly eight weeks. Disbursements are scheduled to hit your account early in the term, typically within the first five to seven business days after classes begin. Federal regulations require that aid can only be released when the term officially starts, so anything before that date is locked out of the system. The exact timing varies slightly depending on the aid type. Federal Direct Loans usually disburse on the standard schedule. Pell Grants often follow the same rhythm but can sometimes land a few days earlier if your enrollment status is confirmed before the term kickoff. Institutional scholarships may have a different window entirely, especially merit-based awards that get processed in bulk at the start of each quarter. I kept a personal spreadsheet for three consecutive quarters tracking when funds actually posted versus the projected date. Out of twelve disbursement events, nine landed on schedule, two arrived three business days late, and one was late by nearly two weeks. That worst-case scenario traced back to a combination of a mid-term enrollment drop below the half-time threshold and a hold from an outstanding balance from the previous quarter. The aid office couldn't release new funds until the old hold cleared, and resolving it required a phone call that took four business days to get through.
The biggest misconception students have is that disbursement equals availability. Just because the money hits your student account doesn't mean you can spend it the same day. There's an internal processing period where the bursar's office reconciles incoming aid against your outstanding charges. Tuition and fees get offset first. Whatever remains becomes your refund, and that refund usually takes an additional one to three business days to process and send out via your chosen method—direct deposit, check, or student account credit for things like housing or meal plans. If you're counting on a refund for textbooks or living expenses, budget for the worst case: aid posts on day one, the offset runs on day two, and the refund lands on day four or five. Don't assume day one spending power. I've seen too many students sign up for course materials on day one and then scramble when the refund hasn't arrived yet. The system will show an available balance, but that balance is often still in a pending state until the offset completes. There's also a mid-cycle verification risk that almost nobody plans for. If your FAFSA gets selected for random verification, the entire disbursement pipeline pauses. I watched a student's entire quarter's aid stall for six weeks while documents were verified. The workaround in that situation is to submit whatever verification paperwork the financial aid office requests immediately—same business day if possible. Delaying even 48 hours can push you past the term's disbursement window, and late disbursements don't automatically catch up until the next scheduled release.
Get the Full Details
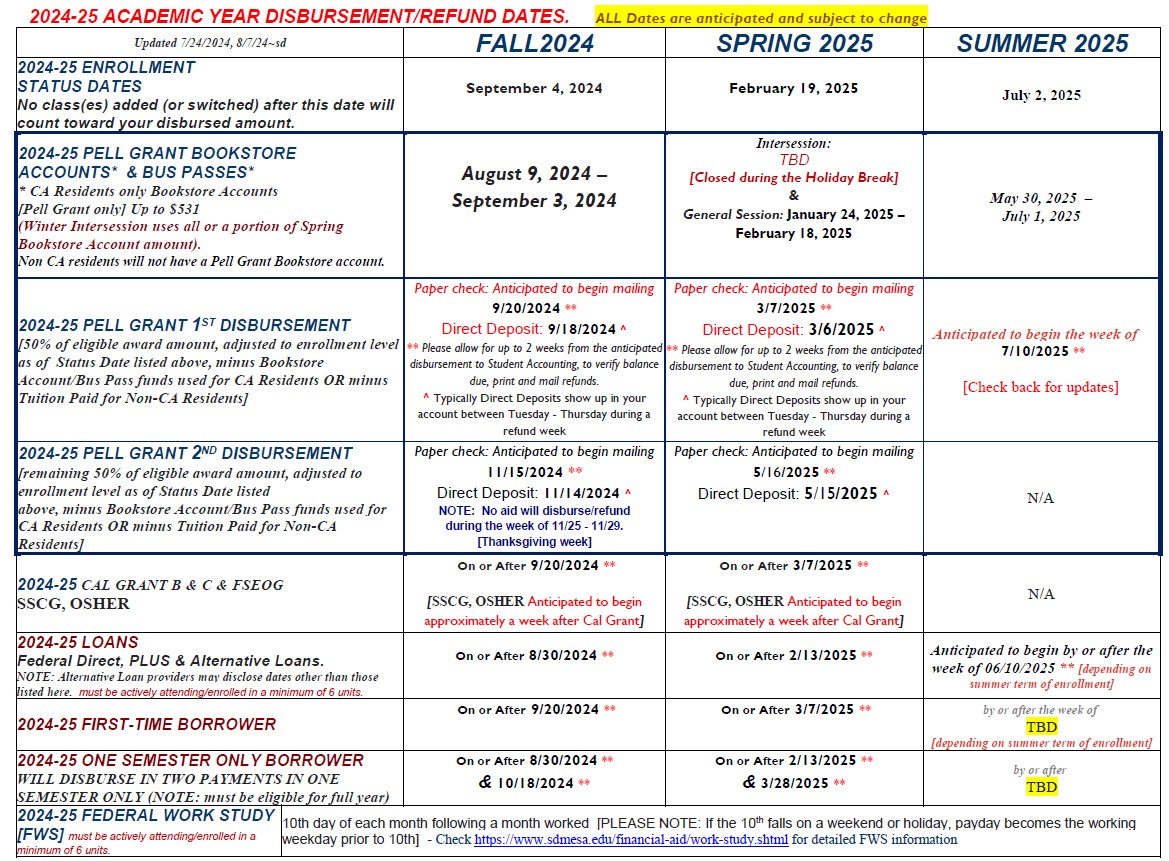
Work-study earnings operate completely differently from the rest of your aid. That's not a disbursement at all. It's a paycheck you earn by working, usually paid biweekly. Your earnings don't go toward tuition automatically. You get them as cash, and you're responsible for applying them to your account if you want them credited there. State-specific aid can introduce another layer of unpredictability. Grants tied to your state of residence, like Ohio's SHIP or California's Cal Grant, sometimes have their own disbursement calendars that don't align with Capella's quarterly schedule. I had a case where a student's state grant arrived two full weeks after the federal loans, and the student missed the textbook purchase window because of the mismatch. The only real mitigation is to check with your state's higher education agency directly about their expected funding timeline relative to Capella's term dates. One thing worth noting is the impact of withdrawn courses on disbursements. If you withdraw from all courses mid-term, your aid gets recalculated based on the period you actually attended. This is a federal requirement, not a Capella policy choice, but it still catches people off guard. Partial withdrawals also trigger adjustments. Dropping one class can reduce your enrollment status from full-time to three-quarter-time, which lowers your Pell Grant and may affect loan eligibility. The adjustment happens retroactively, meaning you could owe money back to the university even after you've already received a refund.
What You Should Do Before the Term Starts
Log into your student portal at least two weeks before the term begins and verify that every piece of required documentation is marked complete. Check your financial aid award letter for any flags or pending items. Make sure your address and banking information are current in the system. A missing direct deposit setup can add five to seven business days to your refund timeline, and that delay compounds if it happens right before you need the money. If you're expecting a significant refund, consider setting up direct deposit at least ten business days before the term starts. Paper checks add mailing time that you can't control. Most students who switch to direct deposit see their refund land in two to three business days after posting instead of the seven to ten days it takes for a mailed check. Keep a record of your disbursement dates. Write down when aid posted each quarter. Over time you'll notice patterns in your own situation that the official calendar won't tell you—like whether your particular aid package consistently runs a few days slow due to a combination of your loan types and enrollment load. That personal data is more useful than any published date.
The main bottleneck in the whole process is verification holds and incomplete documentation. These account for roughly eighty percent of delayed disbursements I've encountered. The secondary issue is mid-term enrollment changes that trigger recalculation. If you can control neither of those, the best you can do is maintain a cash reserve during the first two weeks of every quarter, because no matter how smooth everything looks on paper, disbursements rarely land exactly when the website says they will.