How Capital For Business Start Up Actually Works In Practice
The people who fund early stage businesses are not interested in your passion or your vision. They want to see traction, a clear path to revenue, and the kind of financial discipline that tells them you won't burn through their money on office furniture and brand consultants. Most founders get this wrong from day one. I spent five years helping businesses secure their initial funding across a dozen different industries. The ones that got capital weren't the ones with the flashiest pitch decks. They were the ones who had already solved the harder problems before anyone asked for money. That is the first counter-intuitive thing nobody tells you: raising capital works best when you have already proven you can operate without it.
Where to Actually Find Capital For Business Start Up
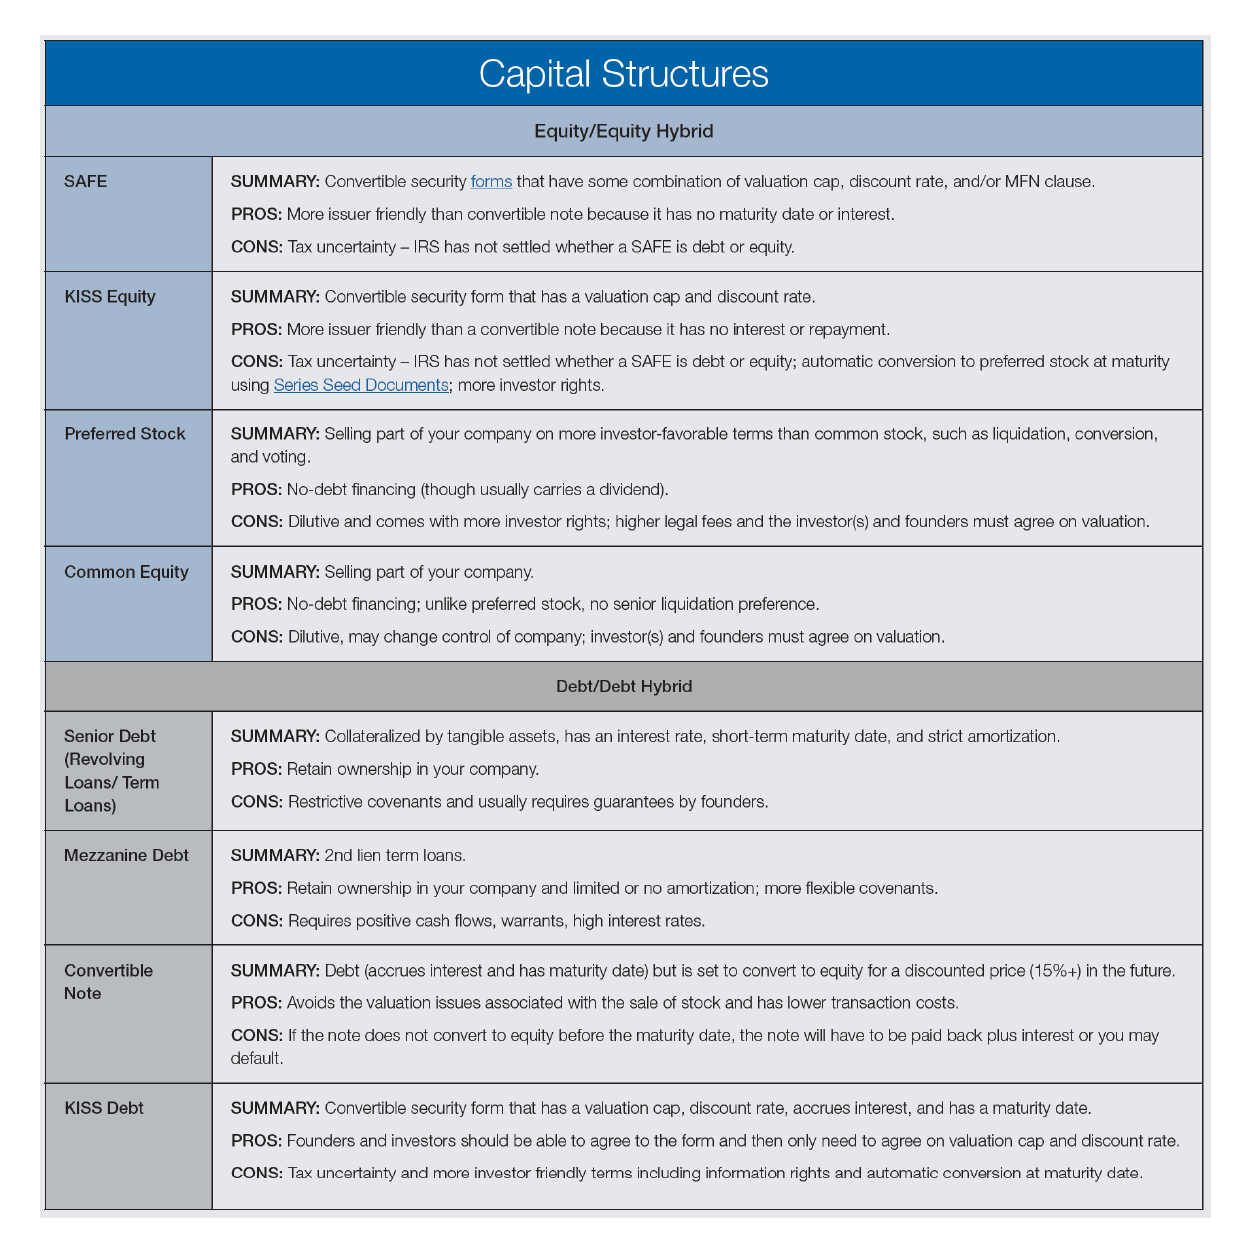
There are four main routes, and they all have very different expectations attached to them. I will walk through each one with what actually happens during the process. Traditional bank loans remain the most misunderstood option. You need personal guarantees, usually at least two years of operating history, and strong collateral. The approval timeline runs four to eight weeks. If your business is pre-revenue, this door is mostly closed. The SBA 7(a) program loosens some requirements, but the documentation burden is still significant. I once worked with a founder who submitted his application three times over eighteen months because his debt service coverage ratio kept sitting just below the 1.15 threshold banks require. He restructured his accounts receivable financing and brought his ratio to 1.32 on the fourth attempt. That single adjustment made the difference between denial and funding. Angel investors and seed funds operate on a completely different timeline and expectation model. They invest between twenty-five thousand and five hundred thousand dollars for equity stakes ranging from ten to twenty-five percent. The evaluation period is shorter, usually two to six weeks, but the due diligence is more aggressive because they are buying ownership, not lending against assets. They will look at your team, your market size, your unit economics, and your exit potential. The common mistake founders make here is undervaluing their company before the first term sheet. An early valuation below one million dollars locks you into a capital structure that becomes very expensive to fix later. I have seen founders give away thirty percent of their company at a three hundred thousand dollar valuation and then spend the next three years in painful down rounds trying to come back from it.
Venture capital follows the same model as angel investing but with larger check sizes, typically five hundred thousand to five million dollars, and much stricter growth requirements. They want to see product market fit first. Revenue traction of at least one hundred thousand dollars annual recurring revenue is the informal benchmark most VCs use before they will seriously consider a seed round. The process takes anywhere from two to six months from first meeting to wire transfer. Term sheets include provisions like liquidation preferences, anti-dilution clauses, and board seats that founders rarely understand until it is too late. The standard 1x non-participating liquidation preference is relatively fair. Anything beyond that, especially participating liquidation preferences or high conversion discounts, is a red flag that you are accepting unfavorable terms out of desperation. Crowdfunding and revenue-based financing are the alternatives that get overlooked because they do not fit the traditional mold. Revenue-based financing means a provider gives you a lump sum and takes a percentage of your daily or weekly revenue until the total repayment, including the factor rate, reaches the agreed amount. Factor rates typically range from 1.2 to 1.5. If you take a hundred thousand dollars at a 1.3 factor rate, you repay one hundred and thirty thousand total. The advantage is speed and lack of equity dilution. The disadvantage is that it becomes extremely expensive if your revenue grows slowly. A business that earns fifteen thousand dollars per month would be paying back roughly eight thousand over twelve months, which creates real cash flow pressure. I helped a client avoid revenue-based financing when their monthly revenue was already thin. Instead, we structured a line of credit secured by their accounts receivable at a much lower effective cost. It took longer to set up, about three weeks instead of three days, but it saved them roughly twenty-five thousand dollars in financing costs over the first year.
The Practical Steps Nobody Emphasizes Enough
Get the Full Details

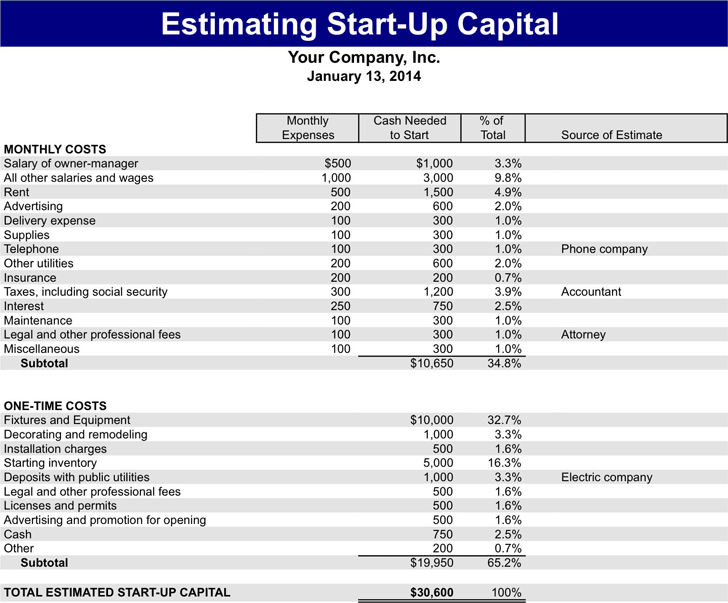
Most guides skip the unglamorous work that actually determines whether your application succeeds. The financial model is the single most important document you will produce. Not the pitch deck, not the business plan PDF, the financial model. It needs to show month-by-month cash flow projections for at least twenty-four months, realistic customer acquisition costs, churn assumptions if applicable, and a clear breakdown of how every dollar of requested capital will be spent. Investors will tear apart vague assumptions. If you write that marketing will cost fifty thousand dollars, you need to show the channel breakdown, the expected cost per lead, the conversion rate, and the resulting customer count. Generic numbers trigger generic skepticism. Specific numbers, even when they are wrong, invite collaboration and adjustment. The cap table management piece is another area where founders create permanent damage through inattention. Every convertible note, every SAFEs, every equity grant changes the ownership structure. If you issue five hundred thousand dollars in SAFEs at a four million dollar cap and then raise a seed round at a ten million dollar valuation, the original SAFE holders effectively got a discount that dilutes everyone else. Keeping track of fully diluted shares across multiple instruments requires a tool like Captable.io or Carta, and it needs to be updated after every transaction. I watched a founder almost lose his controlling stake because he failed to account for an earlier employee option pool that had not been formally approved by the board. Legal documentation should never be handled through downloaded templates. The cost of a qualified startup attorney is dwarfed by the cost of fixing bad terms later. Expect to spend between five and fifteen thousand dollars on legal fees during the initial raise. That covers the term sheet review, incorporation documents if needed, investor agreements, and closing paperwork. Some founders try to save this money and end up signing documents with definitions of standard terms like "qualified financing" or "change of control" that were written from the investor side. Those definitions can completely shift the risk profile of your investment.
There is also a timing consideration that almost no one discusses. Raising capital during a market downturn is possible but requires different messaging. In a downturn, investors favor businesses with positive unit economics over businesses with top-line growth that burns cash. If you are raising in a tight market, your narrative should emphasize profitability path and capital efficiency, not market domination and rapid expansion. The opposite is true in a hot market, where growth stories command higher valuations but also attract more skeptical scrutiny on those same growth numbers.
Capital For Business Start Up: When It Does Not Make Sense
Not every business needs outside capital, and not every business can successfully raise it. Service businesses with low margins and high labor costs, local brick and mortar operations, and companies in highly regulated industries often find that debt or bootstrapping is the only realistic path. Venture capital will not touch a business with a realistic path to ten million in revenue but not one hundred million. Angel investors will often pass on businesses that lack a technology component or scalable distribution model. These are not shortcomings of the business. They are mismatched expectations between what the business is and what the capital provider expects to return.If your business generates steady cash flow from day one, delaying outside funding entirely may be the most financially rational choice. A business that can grow at twenty percent annually using retained earnings avoids dilution, maintains control, and builds a stronger balance sheet. The tradeoff is slower growth, but speed is rarely the deciding factor in long term business survival. Most businesses that fail do not fail because they grew too slowly. They fail because they ran out of cash while growing too fast. The process of securing funding is repetitive, tedious, and often demoralizing. You will face rejection from people who did not read your materials carefully. You will revise your financial model fourteen times because each investor asked for slightly different assumptions. You will negotiate terms that you barely understand until a lawyer explains them line by line. It is a process that rewards preparation, patience, and a willingness to listen to feedback without taking silence or rejection personally. The capital is there for businesses that can demonstrate they will use it wisely. The hardest part is proving that before anyone gives you the chance to prove it after.