Working Through Capital Gains on Your 2022 Return
Most people think capital gains are simple. You sold something for more than you paid, you owe tax on the difference. That's true until it isn't, and then you're staring at a pile of forms wondering where the numbers should go. The IRS wants you to fill out a Capital Gain Tax Worksheet 2022 when your situation gets complicated enough that Schedule D alone doesn't cover it. This usually trips people up around February because they assumed their brokerage summary was enough. The worksheet comes into play when Schedule D has entries that feed into Form 1040 in ways that aren't automatic. If you have Section 1231 gains, unrecaptured Section 1250 gain from depreciation recapture on rental property, or a net positive capital gain that pushes you into the Net Investment Income Tax, the regular Schedule D lines won't calculate everything correctly on their own. The worksheet is essentially a bridge between those complex gain types and the actual tax liability on line 16 of your 1040. You also need it if you carried forward losses from previous years. Schedule D handles the current year fine, but the interaction between carried-over short-term and long-term losses and your current gains gets messy fast. I spent three hours once trying to match up a 2018 carryforward with my 2022 worksheets because my tax software auto-filled a number that didn't actually belong there. The problem was that my software had rolled a net operating loss from a different schedule into the wrong field. I had to pull up my 2018 Schedule D, manually trace the exact carryforward amount, and enter it directly on the worksheet instead of letting the program guess. That saved me about forty dollars in overpaid tax that I wouldn't have gotten back for six months.
What Goes on the Worksheet
Line by line, you're taking the figures from Schedule D and breaking them into their proper tax buckets. Short-term gains stay short-term. Long-term gains split into the 0/15/20% bracket group, the unrecaptured Section 1250 gain bucket, and the 28% rate group for collectibles and certain small business stock. Each bucket gets taxed differently, and the worksheet exists to keep them separated long enough for the tax calculation to apply the right rate to the right dollar amount. Form 8949 feeds into Schedule D first, not the worksheet. That's where people get tripped up. You report each individual sale on Form 8949 with the date acquired, date sold, proceeds, and cost basis. Schedule D totals those up. The worksheet takes the Schedule D output and applies the proper rates. Skipping Form 8949 entirely because you think you can put the numbers directly on the worksheet is a common mistake that will flag a review. The IRS cross-references these forms. Cost basis reporting is another place where things go sideways. Brokerages now report cost basis to the IRS on Form 1099-B for stocks and ETFs, but the basis they report might already be adjusted for Wash Sale rule disallowances or might not include all the lots you sold during the year. I found this out the hard way with a client who sold mutual fund shares in 2022. The 1099-B showed a cost basis of $42,000, but when we pulled the transaction history from the fund company, the actual average cost basis was $38,700 after three years of dividend reinvestments. We had to attach a statement explaining the discrepancy to the return. It added twenty minutes to the filing but prevented an audit trigger.
The Net Investment Income Tax Complication
If your modified adjusted gross income puts you above the threshold, your capital gains might also be subject to the 3.8% Net Investment Income Tax. The worksheet helps you figure out how much of your gain counts as net investment income versus other types of gain that don't trigger the NIIT. Rental property depreciation recapture is a good example. Unrecaptured Section 1250 gain is part of your capital gain on the worksheet, but it does not count as net investment income for NIIT purposes. Most software handles this automatically, but if you're preparing a return manually, you need to track which bucket each dollar falls into separately. One thing that catches people off guard is the treatment of qualified dividend income. It shows up on the same lines as long-term capital gains on Schedule D and the worksheet, but it gets its own column and its own tax calculation. Mixing them up doesn't change the total tax in most cases because both generally fall into the 0/15/20% bracket, but it can matter if you're near a phaseout threshold or if you have foreign income that changes your effective rate. Another issue is the ordering of losses and gains. The worksheet requires you to net short-term against short-term and long-term against long-term first. Only after that internal netting do you combine the two results. If you net everything together immediately, you can end up with a different outcome than if you keep the categories separate, especially when one side is a loss and the other has multiple rate groups. The order matters because the loss deduction limit and the carryforward rules depend on which category the remaining loss sits in.
Get the Full Details

Where to Get the Worksheet
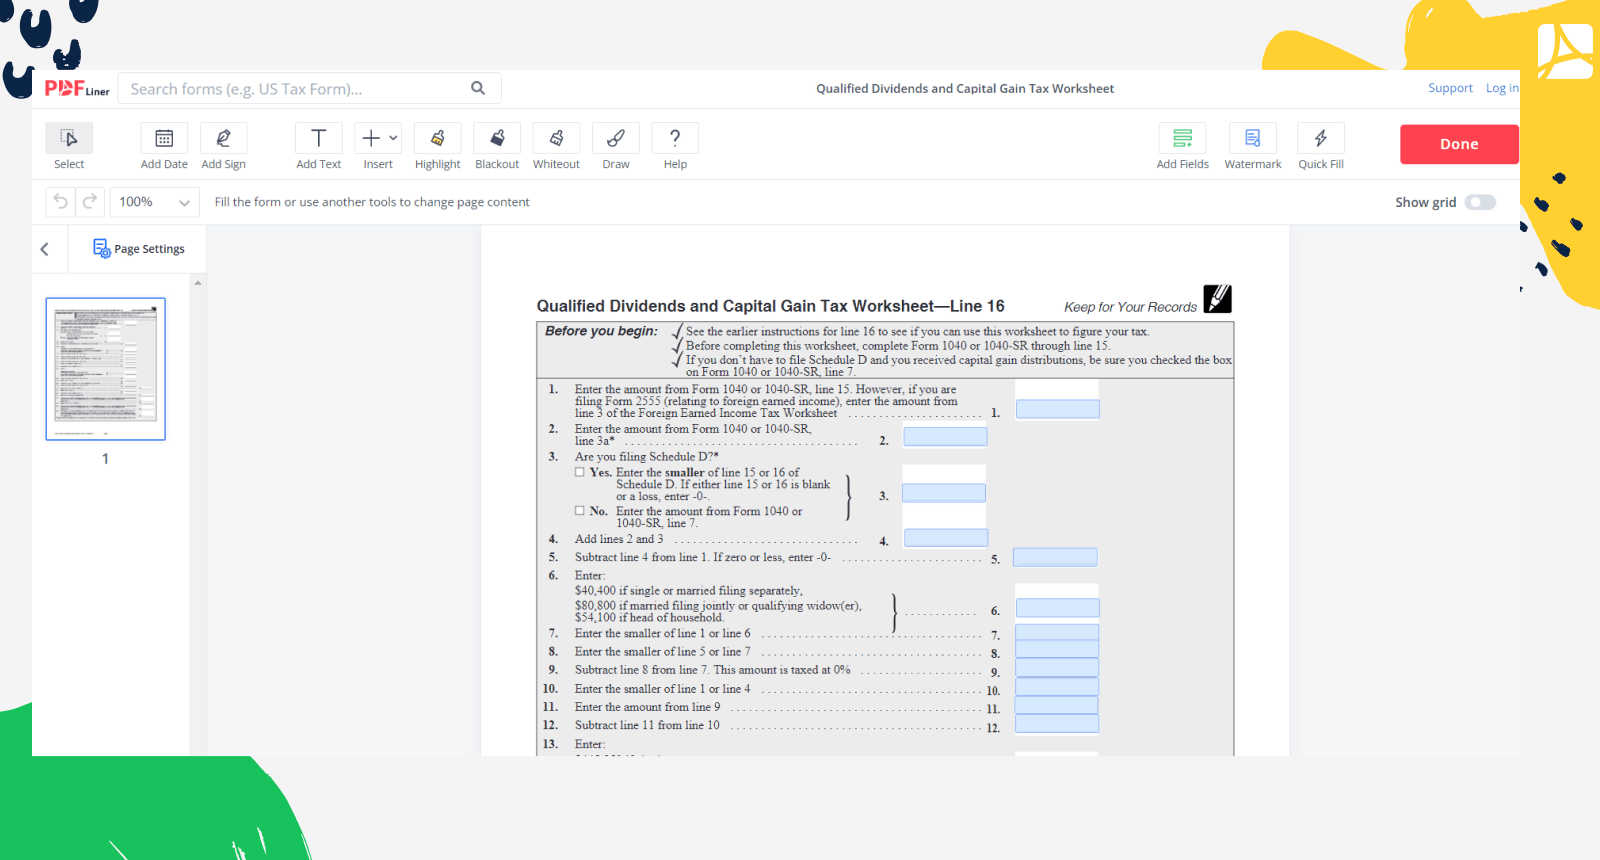
The official Capital Gain Tax Worksheet 2022 is available on the IRS website as part of the Schedule D packet. The IRS doesn't host a standalone download for just the worksheet anymore, but it's included in the Schedule D instructions PDF for the 2022 tax year. You can find it under the section labeled "Capital Gain Tax Worksheet." There are also third-party versions floating around, but they may not match the exact line references the IRS uses, so sticking with the official version is safer. If you're using tax software, the worksheet generates automatically once you input enough data to trigger it. You won't see a blank form to fill out, but you can usually view or print the calculated version from the final return preview. The worksheet assumes you have all your documentation ready before you start. It does not prompt you for missing information. If you're missing a Form 8949 or don't have the cost basis for a particular lot, the worksheet will either produce a wrong number or leave a blank line that looks correct but is actually incomplete. There is no built-in validation. You're responsible for making sure every line corresponds to a real transaction. For straightforward stock sales with clean 1099-B reporting, the worksheet is rarely necessary. You can use Schedule D alone and move on. The worksheet adds complexity without adding accuracy in simple cases. It only becomes useful when you have multiple rate groups, depreciation recapture, or carryforwards. Don't reach for it out of habit. Use it only when your situation actually requires it, and save yourself the extra half-hour of work.