Working With Capital Loss Carryover on Your 2020 Return
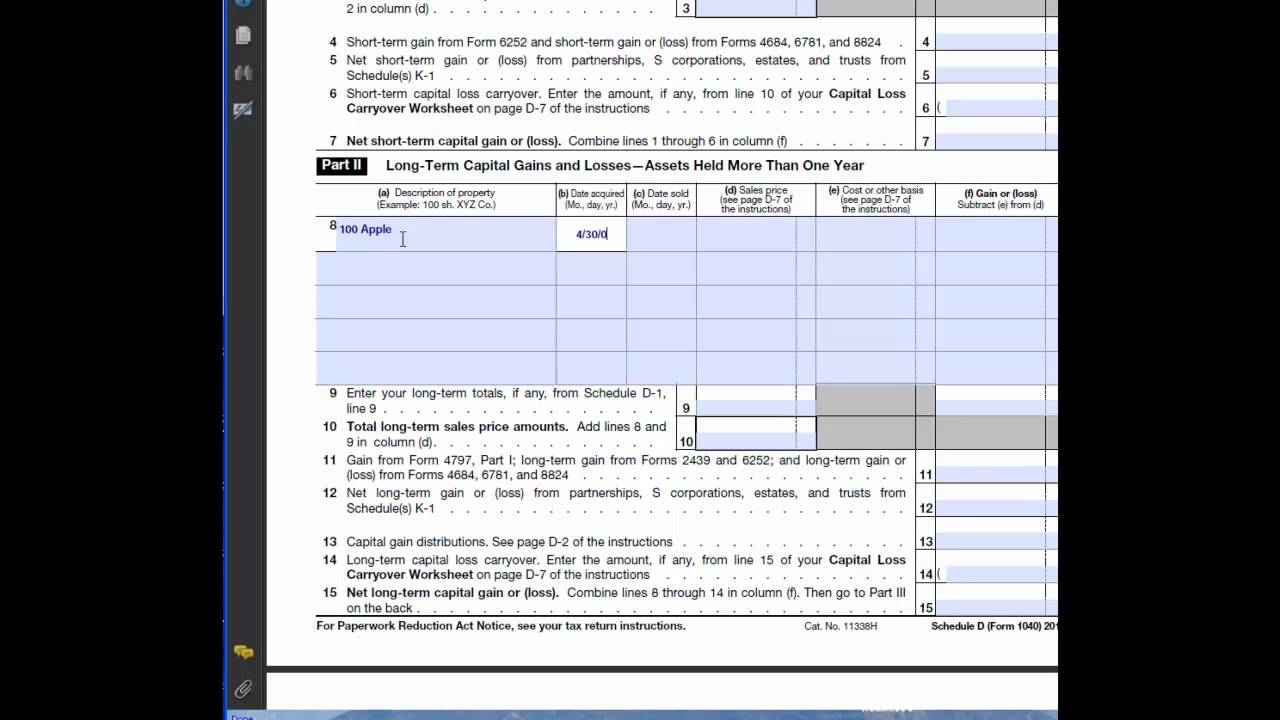
If you have investment losses that exceeded your gains, you are probably looking at a capital loss carryover. The worksheet you need lives on Schedule D, and it is not particularly complicated, but it has a few trapdoors that will trip up anyone who rushes through it. The actual form is Schedule D, Part II. There is no separate document that the IRS mails you or that has "worksheet" in the title. Tax software pulls from it automatically, but the underlying calculation is always the same: your net capital loss from the current year gets carried forward to future years up to a limit.
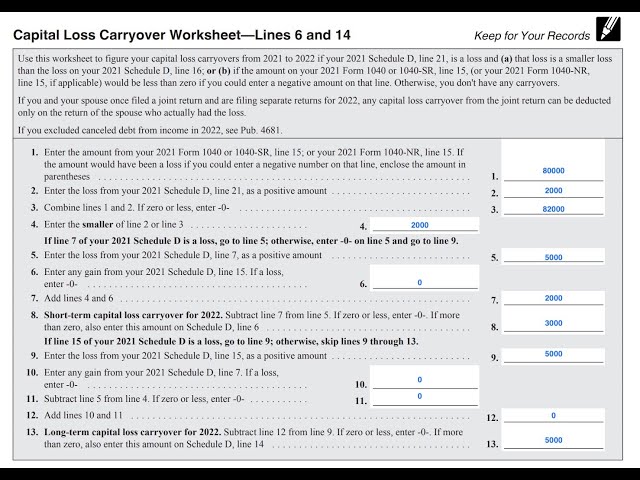
Capital Loss Carryover Worksheet 2020
The carryover itself is capped at $3,000 per year against ordinary income. That limit applies to both single filers and married filing jointly. Married people filing separately can only offset $1,500 per year, which makes splitting losses over time a lot less attractive. Here is how the work actually flows. You start with line 7 of Schedule D, which is your combined net short-term and net long-term gain or loss after the wash sale and farmer/rancher adjustments. If that line is a loss and it is larger than your gains, you then move to line 13. Line 13 is where the $3,000 cap gets applied. The worksheet on the back of Schedule D tells you what portion of your loss can be used this year and what portion carries over.
Line 9 of Schedule D is your total gains if you had any. Lines 10 through 12 handle the deduction against ordinary income, which is the capped $3,000 or $1,500 depending on filing status. Whatever is left becomes your carryover, and it goes on line 14. You enter the carryover amount onto line 9 of Schedule D for the following year. That is how it moves forward. It carries indefinitely until it is fully used. I ran into a situation last year where a client had a large recognized loss in 2020 but also received a 1099-B with a basis adjustment from a wash sale. The software initially put the carryforward number at the wrong value because the adjustment had already been deducted on the current year's return. The fix was to back out the basis adjustment from the gross loss before running the worksheet. Once I removed the double-counted adjustment, the carryover dropped by about $4,200 and matched the correct amount. This happens more often than it should with software that does not reconcile basis adjustments first.
Get the Full Details
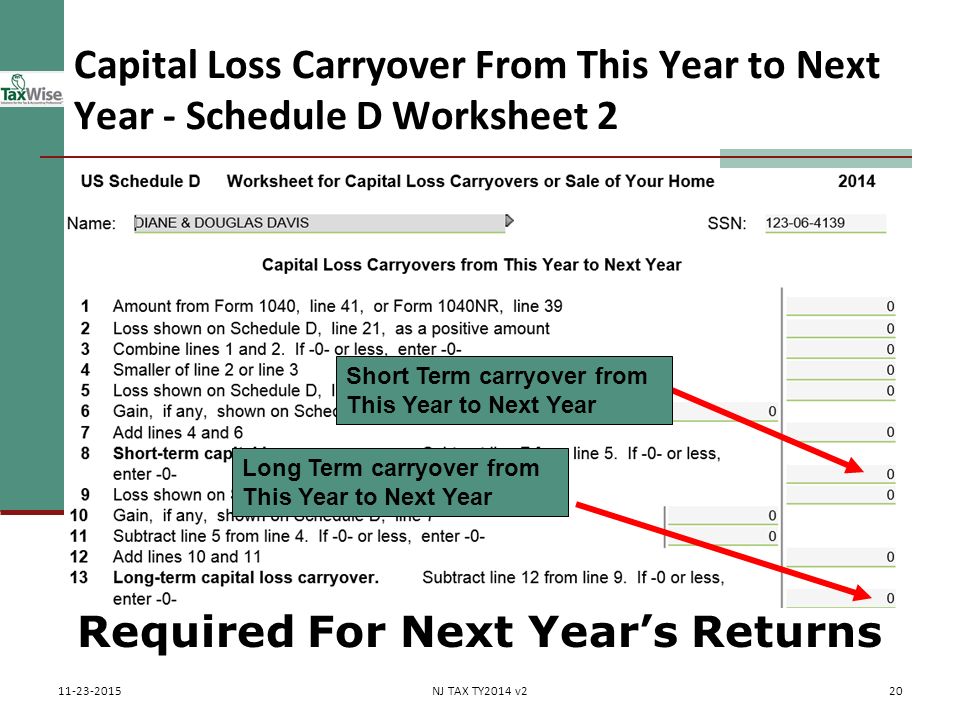
Another thing people routinely mess up is the character of the carryover. Short-term losses stay short-term when they carry forward. Long-term losses stay long-term. You do not get to reclassify them just because you prefer one treatment over the other. If you ignore this on line 14 and mix the categories, the next year's Schedule D will calculate your net position incorrectly and your tax liability will be off. The worksheet also has a quirk with section 1256 contracts. If you trade regulated futures or options, those gains and losses are automatically treated as 60/40 regardless of holding period. They are separate from the regular Schedule D lines and should not be folded into the same bucket before running the worksheet. If you combine them too early, the $3,000 cap may not be applied correctly to the non-section 1256 portion. For 2020 returns, the rules did not change materially from prior years. The $3,000 limit is still in effect and the carryforward mechanism remains the same. The main difference this year is some taxpayers had pandemic-related portfolio swings that generated unusually large losses, which means the carryover could extend several years into the future for people who did not have offsetting gains.
There is a reason I prefer keeping the carryover in a spreadsheet instead of relying solely on software. Tax programs do not always preserve the original character breakdown when you amending or when information returns arrive late. If you lose track of how much is short-term versus long-term, you cannot reconstruct the correct numbers without going back to the original Schedule D. A simple table with columns for year, character, amount, and expiration if any will save you the trouble of reconstructing it later. The IRS does not publish a standalone Capital Loss Carryover Worksheet 2020 form you can download separately. You get it directly from the Schedule D instructions, which are available on irs.gov under the 2020 Schedule D and Instructions PDF. That document includes the line-by-line worksheet in the back. Most preparers use it as a reference even when the software handles the math. If your loss is very large and you expect it to take multiple years to absorb, it is worth considering whether you should realize some gains in an upcoming year to offset it. There is no penalty for recognizing gains alongside carried-over losses. The offset happens on Schedule D in the year you take the action, and the net figure flows into the regular capital gain tax brackets. Doing this strategically usually reduces the total tax paid compared to letting the carryover sit unused through years where you have no other gains.
One more edge case that catches people: if you receive a loss from a partnership or S corporation, that loss retains its character when it flows to your individual return. It is not reclassified as an ordinary loss just because it came from a pass-through entity. It still belongs on Schedule D, and the carryover rules apply the same way. The worksheet works, the limits are fixed, and the process is straightforward once you get past the initial setup. The hard part is keeping the records clean so the carryover is accurate the next time you file.