What Capital Resources Actually Mean In Practice
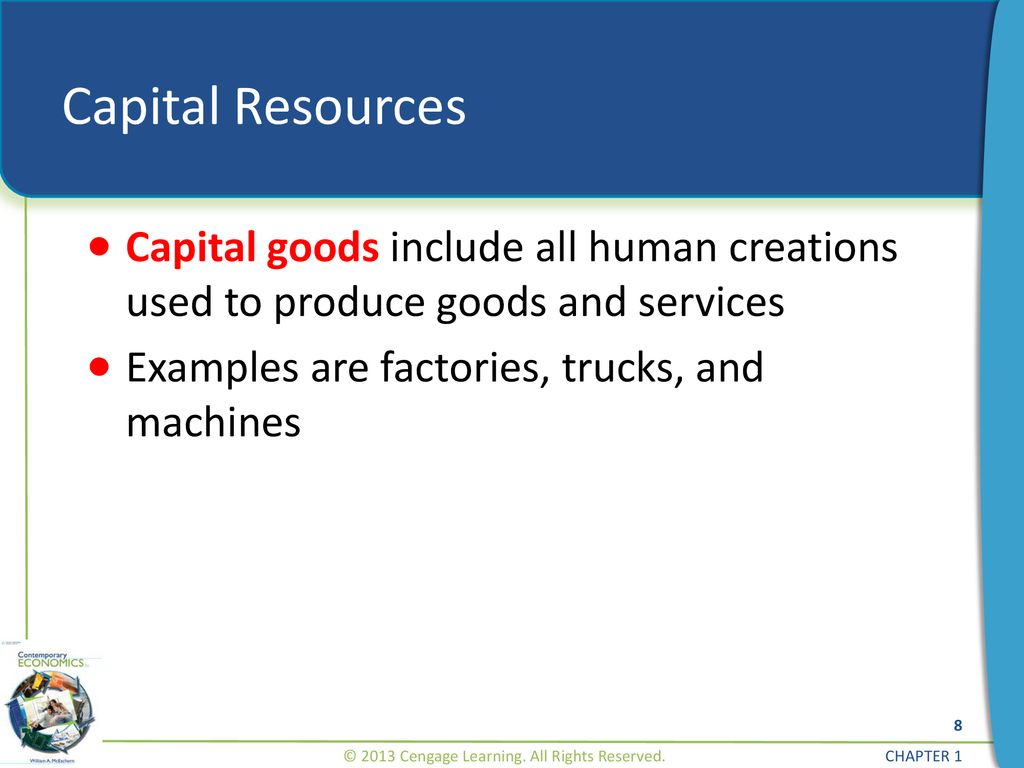
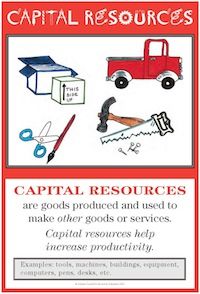
When a firm decides whether to buy new machinery, upgrade software, or hire more engineers, it is looking at capital resources. These are the inputs that are themselves produced and used to create other goods and services. In most real operations, this splits into two buckets. Physical capital includes machinery, buildings, vehicles, tools, and technology infrastructure. Human capital covers the skills, training, and knowledge that workers bring to production. Both count as capital resources, and both require investment decisions that carry tradeoffs. The standard textbook framework treats these resources as factors of production. Output depends on how much capital you deploy, how efficiently you use it, and what alternative investments could have produced more value elsewhere. This sounds straightforward until you are sitting in a meeting trying to justify a $400,000 machine purchase while your cash flow statement shows tight margins. That is where the theory runs into the day-to-day problem of limited budgets and competing priorities.
Understanding Capital Resources In Economics
At its core, this concept addresses how firms allocate scarce resources toward productive assets. The key question is not whether you need more capital but whether deploying capital into one area generates a better return than deploying it elsewhere. This connects directly to the idea of opportunity cost, which is the return you give up by choosing one investment over the next best alternative. I ran into a specific problem a few years ago when a client was evaluating whether to modernize an aging production line or expand their warehouse capacity. The numbers looked reasonable for both projects on paper. The machine upgrade promised a 14% return over five years. The warehouse expansion offered a 12% return with lower risk. But when I actually mapped out the resource constraints, the situation changed. The machine upgrade required a specialist technician for six weeks during installation, which meant pulling that person from the warehouse project. The warehouse expansion needed the same specialist for four weeks, but at a different time in the schedule. We ended up modeling both scenarios together rather than in isolation, and the combined analysis showed that doing both sequentially would delay the warehouse project by eight weeks and increase labor costs by roughly $47,000 in overtime. The single best option was actually neither project on its own but a phased approach that spread the machine investment over two quarters and kept the warehouse timeline intact. This is exactly the kind of problem that textbook models do not capture well, because they assume resources can be shifted without friction. The practical takeaway is that capital resource decisions are rarely independent. They interact through shared labor pools, competing use of management attention, and overlapping timelines. The most common mistake I see is evaluating each capital project in a separate spreadsheet and then adding the results together. This approach misses the interaction effects that often determine whether a portfolio of projects actually works.
The Real Mechanics Of Allocation
Allocating capital resources involves three steps that most organizations handle poorly in sequence. First, you identify the pool of available resources, which includes not just money but also time, personnel, and operational bandwidth. Second, you rank competing uses based on expected returns adjusted for risk and timing. Third, you implement the allocation while monitoring for changes in assumptions that could invalidate earlier decisions. The part that usually gets missed is the monitoring step. Capital resources lose value when conditions shift faster than your allocation process can adapt. I worked with a mid-size manufacturer that had allocated $1.2 million in capital toward automated testing equipment in Q1. By Q2, their primary customer had shifted specifications, making that equipment largely unsuitable for the new product line. They had committed the funds before locking in the customer requirements. The equipment sat idle for eleven months before being repurposed at a 40% loss relative to the original cost basis. This is not a rare failure mode. It happens frequently in industries where demand shifts occur on shorter timelines than typical capital budgeting cycles. One way to reduce this risk is to structure capital commitments as staged investments rather than single lump-sum decisions. Each stage includes a go-or-no-go checkpoint tied to specific milestones. This approach slows down the deployment process slightly but dramatically improves the odds that capital ends up where it generates the strongest returns. The tradeoff is that staged commitments require more governance overhead and can create delays if teams are not disciplined about making timely decisions at each checkpoint.
Get the Full Details

Common Pitfalls That Cost Money
The first major pitfall is treating capital resources as interchangeable when they are not. Physical capital and human capital behave very differently. You can sell a machine relatively quickly in most cases. Training a worker to use new technology takes months, and that knowledge is tied to specific people and processes. When companies assume capital is fully liquid and transferable, they overestimate their ability to pivot and underestimate the cost of switching between capital types. The second pitfall is confusing accounting depreciation with economic depreciation. Accounting depreciation follows tax rules and company policy. Economic depreciation reflects the actual decline in an asset's productive capacity or market value. A piece of equipment might be fully depreciated on the books after seven years, but it could still operate at full capacity for another three. Conversely, software infrastructure might show a five-year accounting life but become obsolete in two years due to security vulnerabilities or compatibility issues. Using the wrong depreciation schedule distorts your assessment of ongoing capital costs and can lead to premature replacement or delayed investment decisions. I encountered a situation where a company was replacing servers every five years based on their accounting schedule. When I recalculated using economic depreciation and factored in increasing maintenance costs and declining uptime after year three, the optimal replacement window was closer to four years. The difference in net present value between the two approaches amounted to roughly $23,000 annually across their infrastructure portfolio. That number is small in isolation but reveals a systematic error that compounds over time.
Where The Framework Falls Short
The capital resources model works well for planning and analysis in stable environments with predictable demand. It becomes much less useful when you are dealing with rapid technological change, regulatory uncertainty, or markets where customer preferences shift unpredictably. The model also assumes you can measure returns accurately, which is difficult for investments in training programs, research initiatives, or brand building where the payoffs are diffuse and uncertain. When capital allocation involves high uncertainty, the traditional net present value approach can give misleading signals. In those cases, real options analysis provides a more flexible framework. Instead of treating an investment as a single decision, you model it as a series of optional decisions that you can make as new information arrives. This approach is more complex to implement but captures the value of waiting and adapting in ways that standard capital budgeting techniques do not. Another limitation is that the model does not adequately address organizational factors. Capital decisions are made by people with competing incentives, incomplete information, and cognitive biases. A project that looks attractive on paper may not get funded because it does not align with the priorities of the person controlling the budget. Understanding these dynamics is often more important than getting the financial calculations exactly right.
Practical Steps For Better Allocation
Start by building a single view of all capital commitments across your organization. Most companies have capital requests scattered across different departments, each tracked in separate spreadsheets or systems. Bringing this together into one repository lets you see the full picture of what is funded, what is pending, and what is competing for the same resources. Next, apply a consistent evaluation framework to all proposals. The framework should account for risk, timing, resource dependencies, and strategic alignment. Use a weighted scoring model rather than relying solely on financial metrics. This forces explicit consideration of factors that are easy to overlook when you focus only on return calculations. Then, implement regular review cycles rather than treating capital decisions as one-time events. Quarterly reviews are usually sufficient. At each review, assess whether the assumptions behind each active commitment still hold and whether conditions warrant reallocating resources to a different priority. This keeps your capital allocation process responsive instead of rigid.
Finally, track outcomes against expectations. When a project delivers different results than predicted, document why and use those lessons to improve future evaluations. This feedback loop is where most organizations fail, but it is also the simplest improvement to make. The data already exists. You just need to connect it back to the decisions that drove it.