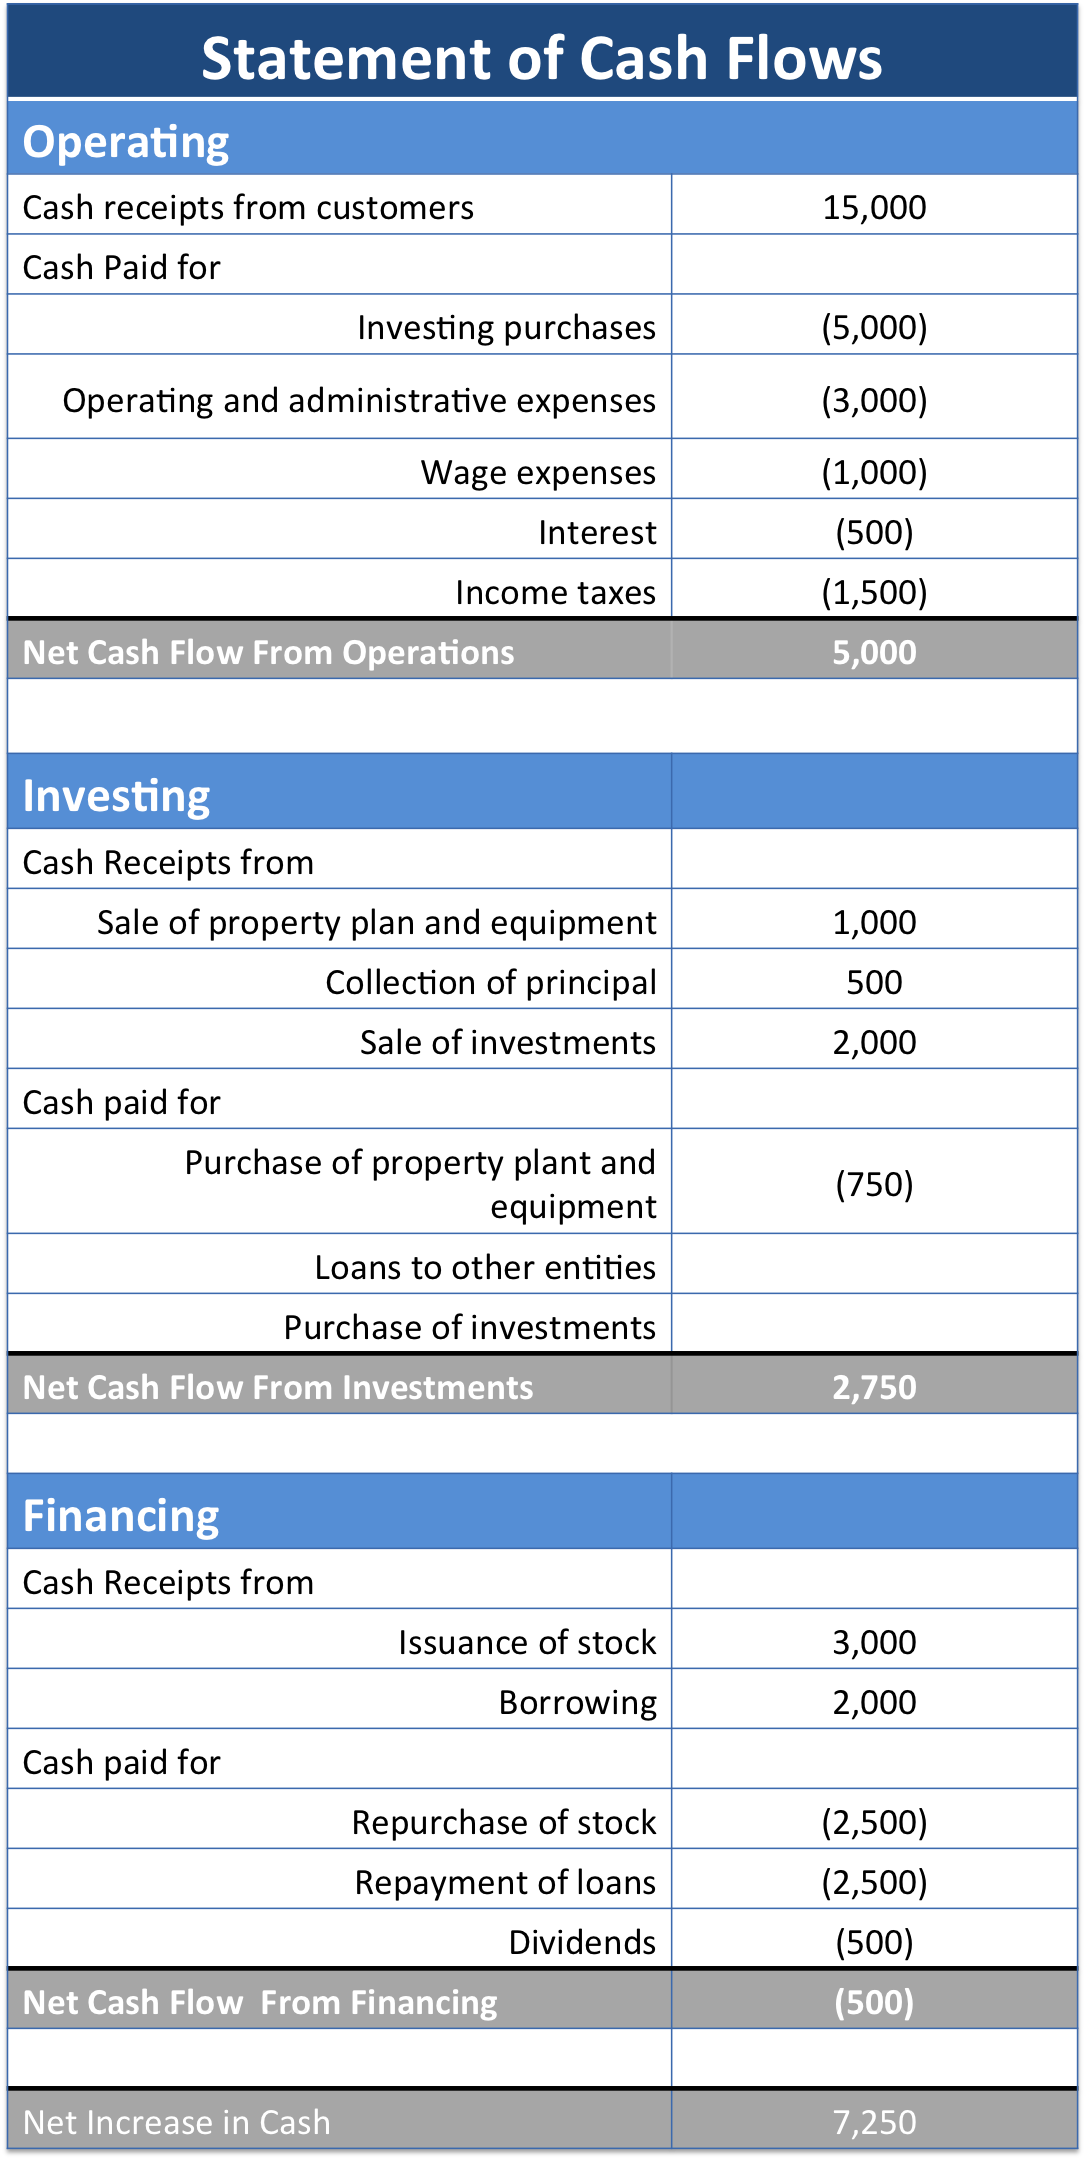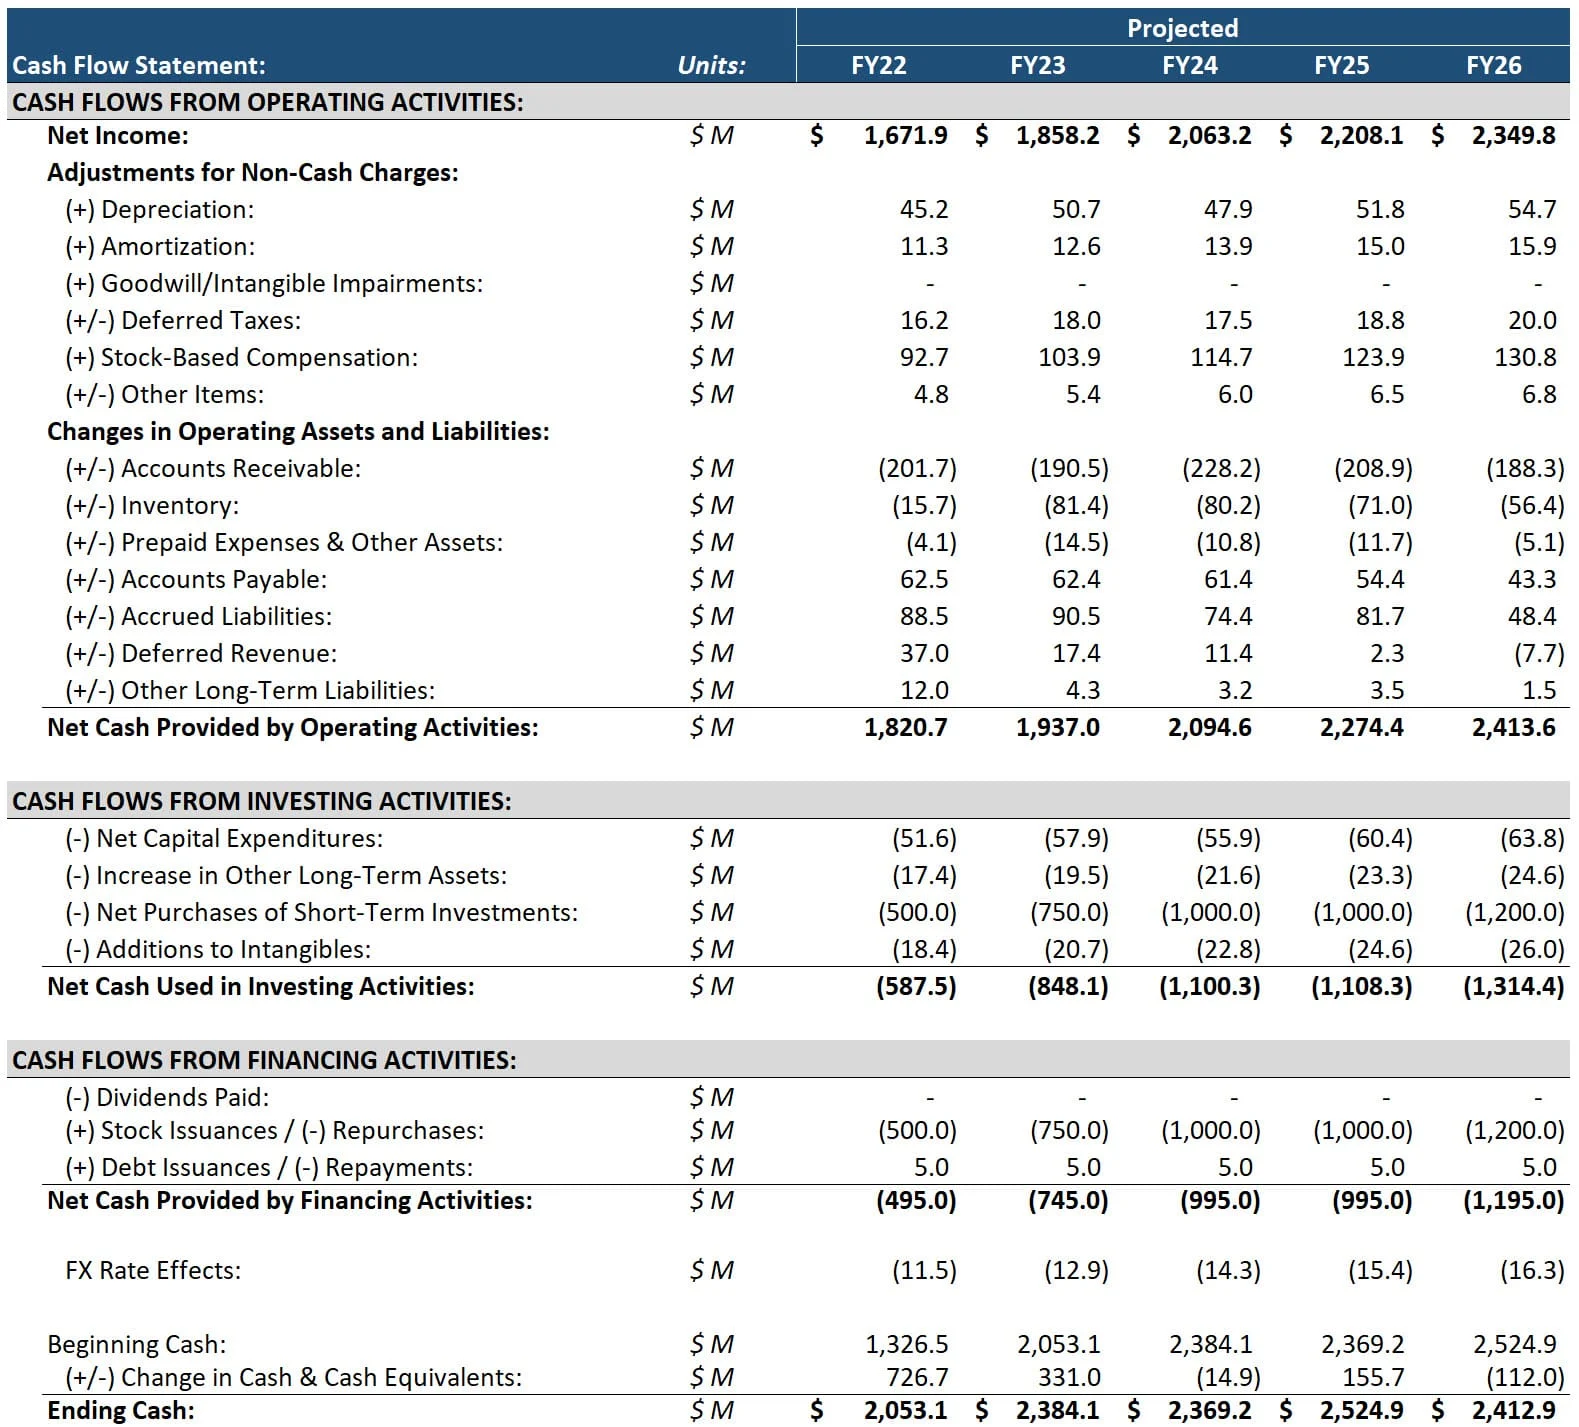
Reading the actual numbers behind the spreadsheet
Most people look at a cash flow statement and see three sections they vaguely remember from accounting class. That's enough to get you in trouble, not enough to keep you out of it. The statement itself is straightforward on the surface - operating, investing, financing - but the interpretation part is where things fall apart quickly if you're not paying attention to the edges. Start with operating cash flow. This is your base layer. Net income sits at the top of the statement, but it's been through accrual adjustments, non-cash charges, and a bunch of other items that make it look very different from actual cash moving in and out. You need to work backwards through the indirect method starting point, looking at changes in working capital, depreciation add-backs, and any unusual items that inflated or deflated reported earnings. The difference between net income and operating cash flow tells you something important - if it's consistently large and positive, the company is converting earnings to cash efficiently. If it's negative over multiple periods, you have a structural problem regardless of what the income statement says. Investing cash flow is usually the easiest section to read but the hardest to interpret correctly. Capex shows up here as a negative number. That's normal. What matters is whether the company is investing enough to maintain its operations versus growing them. Maintenance capital expenditures are the threshold - anything above that is expansionary. The problem is most companies don't break this out explicitly, so you have to estimate it. A rough rule of thumb is that maintenance capex tracks with depreciation over time for mature businesses. If a company reports depreciation of 80 million and total capex of 200 million, you can reasonably assume roughly 80 million is maintenance and 120 million is growth investment. Your mileage will vary depending on the industry and whether the business is capital intensive.
Financing cash flow covers debt issuance and repayment, equity transactions, and dividends. This section tells you whether the company is leveraging up or paying down, buying back shares, or distributing cash to shareholders. Negative financing cash flow isn't inherently bad - it could mean the company is reducing debt, which is fine if operating cash flow can support it. Negative financing combined with negative investing and positive operating cash flow is actually the healthy pattern most mature companies show. You're extracting cash from operations, reinvesting some of it, and returning the rest. I ran into a situation a few years ago where a manufacturing company showed strong operating cash flow of 45 million, negative investing cash flow of 30 million, and negative financing cash flow of 15 million. On paper, that looked like a company generating plenty of cash and using it wisely. When I dug into the working capital changes, I found that accounts receivable had grown by 28 million over the year while revenue had only grown 6 percent. The operating cash flow number was being propped up by a supplier payables increase of 22 million. In other words, they were paying suppliers slower to make the cash flow look better. The real story was much weaker. I flagged this to the credit committee and the relationship was renegotiated two weeks later. That's the kind of thing you catch when you stop looking at the headline number and start pulling apart the components.
Free cash flow and what it actually means
Free cash flow to the firm is operating cash flow minus maintenance capital expenditures. This is the cash available to all capital providers, debt and equity. It's the number that matters for valuation, debt service coverage, and dividend sustainability. The formula is simple but the inputs are where people go wrong. Using total capex instead of maintenance capex will understimate free cash flow for growing companies and overestimate it for declining ones. You need to separate the two, and that requires judgment calls based on the business lifecycle and industry norms. For free cash flow to equity, you subtract net debt repayments from free cash flow to the firm. This gives you the cash available specifically to shareholders. It's the relevant metric for companies with volatile debt structures or those that frequently issue and retire debt. A company with strong FCFE but weakening FCF is worth understanding - it might be taking on more debt to fund operations, which is sustainable only as long as creditors remain comfortable. One counter-intuitive point that beginners consistently miss: a company can have negative free cash flow for several years and still be perfectly healthy. Think about high-growth technology or pharmaceutical companies in development stages. They're investing heavily in capacity or pipelines, and their operating cash flow hasn't caught up yet. The question isn't whether free cash flow is negative right now. It's whether the investments are likely to generate returns that exceed the cost of capital. If the answer is yes, the negative FCF is a feature, not a bug. If the answer is unclear or no, you're looking at value destruction that will eventually show up in the numbers.
Get the Full Details
Another thing people get wrong is treating cash flow from operations as a stable, predictable number. It's not. Working capital swings can be enormous quarter to quarter. Inventory buildups before product launches, seasonal receivable patterns, one-time vendor payment terms - all of this creates noise. You need to smooth operating cash flow across at least two to three years before drawing conclusions about quality of earnings or cash generation ability. A single quarter is rarely informative unless something dramatic happened that you already know about.
Red flags and limitations you should know about
Cash flow statement analysis has real blind spots. The biggest one is that it doesn't capture obligations that haven't hit the cash statement yet. Operating leases used to be a major issue before the accounting standards changed, but there are still off-balance-sheet arrangements, contingent liabilities, and contractual commitments that don't appear in the three sections. You need to read the footnotes to get the full picture. The cash flow statement alone will mislead you about the true liquidity position of any company with significant lease obligations or vendor financing arrangements. Another limitation is that cash flow doesn't tell you about the timing of future cash needs. A company might show strong positive cash flow today because it delayed equipment replacements or postponed R&D spending. Those decisions create cash now but generate larger outflows later. Without looking at the capital expenditure plan and management commentary, you can't distinguish between genuine cash generation and temporary cash conservation through deferral. This distinction matters a lot when you're assessing whether a dividend is sustainable or whether a buyback is funded by borrowing or by cutting necessary investments. The indirect method of presenting operating cash flow also creates interpretation challenges. Some line items get buried in the reconciliation between net income and operating cash flow. Stock-based compensation is a common example - it's added back as a non-cash expense but it dilutes existing shareholders. Someone could argue it's a real cost even though it doesn't affect cash. Similarly, gains and losses on asset sales get removed from operating cash flow and shifted to investing, but the economic substance of those transactions is mixed. You're better off looking at the total picture across all three sections rather than isolating operating cash flow as the single measure of performance.
If you're doing this analysis regularly, I'd recommend building a simple template that auto-calculates maintenance versus growth capex based on historical depreciation trends and revenue growth rates. It takes about twenty minutes to set up in Excel and saves you from doing the manual estimation every time. The model doesn't need to be fancy - just cells that pull the relevant line items from the statement, compute the ratios, and flag outliers relative to the company's own history. You'll spot problems faster that way instead of staring at raw numbers and trying to do the comparison in your head.