Building a Cash Flow Statement From Scratch
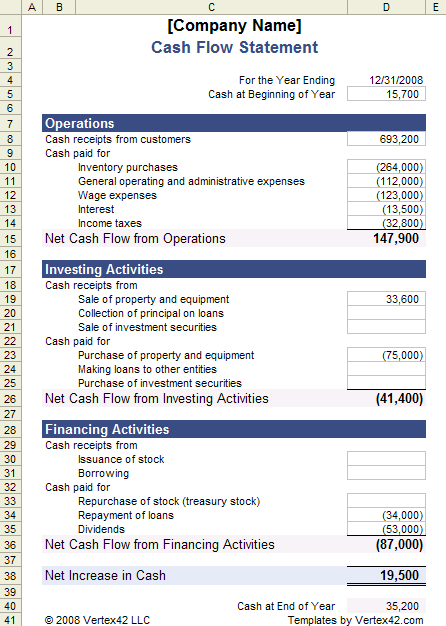
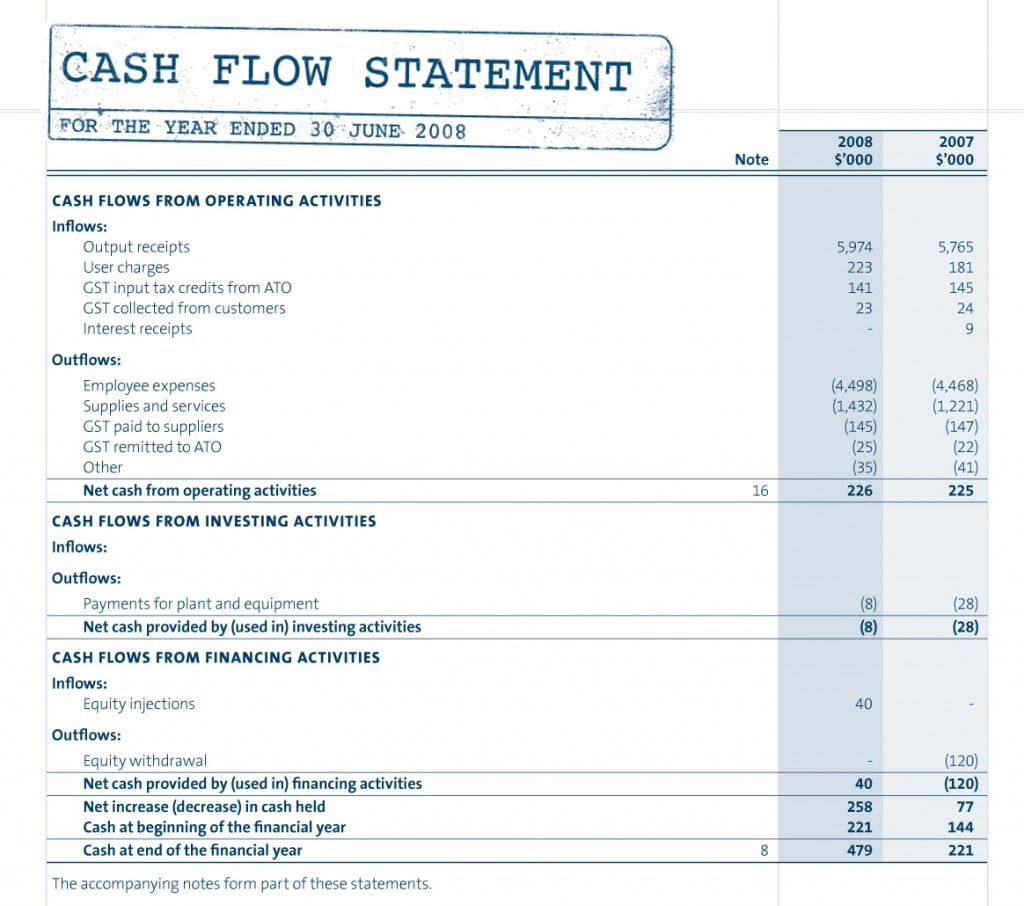
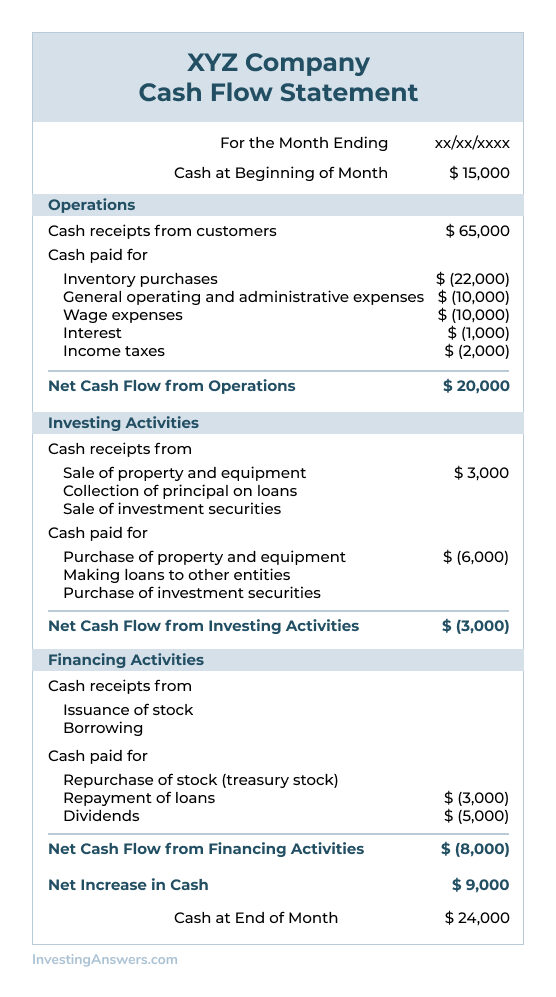
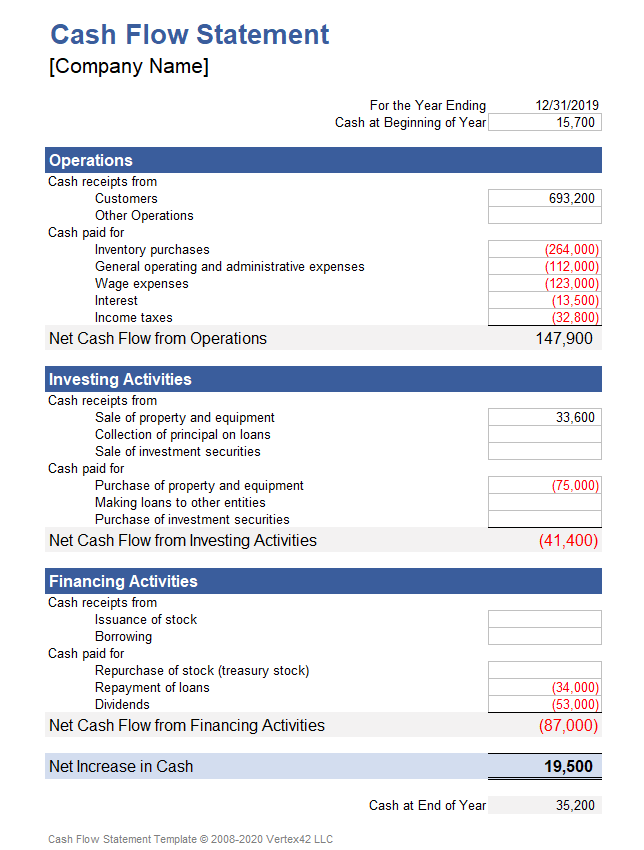
Most people start by dumping their general ledger into Excel and staring at it. That never works well. The actual process begins with pulling your bank statements and comparing them line by line against recorded revenue and expenses. I spend about an hour on this reconciliation step alone because accounts payable and accounts receivable timing differences will destroy your numbers if you skip it. The cash flow statement shows you where money actually entered and left the business, separate from what the income statement claims. That distinction matters more than most small business owners realize. The income statement uses accrual accounting. Revenue gets recorded when an invoice is sent, not when the bank account actually receives the deposit. The cash flow statement fixes that gap by showing real movement. There are three sections you need to build: operating activities, investing activities, and financing activities. Operating activities cover the day-to-day business. Investing activities track equipment purchases, sales of assets, or capital expenditures. Financing activities capture loans taken, loan repayments, owner draws, or equity injections.
I learned this the hard way during a quarterly close for a manufacturing client who had significant inventory buildup. The income statement looked fine on paper. The cash flow statement revealed that $47,000 was sitting in raw materials and finished goods instead of in the bank account. We had over 90 days of inventory turnover at that point. The owner was taking distributions based on net income while the business was slowly bleeding out from working capital strain. I restructured the purchasing schedule and negotiated longer payment terms with two key suppliers, which freed up about $28,000 within six weeks. That kind of fix is invisible if you only look at profit and loss statements. The indirect method is the most common approach and it starts with net income, then adds back non-cash items like depreciation and amortization. Then you adjust for changes in working capital accounts. An increase in accounts receivable means you recorded revenue but havent collected the cash yet, so you subtract that amount. An increase in accounts payable means you recorded an expense but havent paid it yet, so you add that back. These adjustments can feel mechanical, but they reveal the actual cash story hidden inside the accrual numbers. The direct method is technically clearer because it lists actual cash receipts and payments directly. Cash received from customers. Cash paid to suppliers. Cash paid for salaries. The problem is that most accounting systems do not track this data in a ready-to-use format. You end up spending several hours compiling transaction-level detail that you could have extracted in fifteen minutes using the indirect method. I recommend the indirect method for most businesses unless you are preparing statements for a bank that specifically requests the direct format.
Here is a practical example. Say your net income for the quarter is $12,000. Depreciation expense was $3,200. Accounts receivable increased by $4,500. Accounts payable decreased by $2,100. Inventory increased by $6,800. Your operating cash flow would be $12,000 plus $3,200 minus $4,500 minus $2,100 minus $6,800, which equals $800. Net income was twelve thousand dollars but actual cash generated from operations was only eight hundred. That single number tells you everything you need to know about the quality of earnings that quarter. Several things trip people up repeatedly. The first is forgetting that owner personal expenses running through the business account distort the cash flow. I see this constantly with sole proprietors who use the business account as a personal checking account. You need to classify those transfers clearly as owner draws or equity contributions, not operating expenses. The second is misclassifying loan proceeds. Loan money coming in is a financing activity, not operating income. Paying down the principal is a financing outflow. The interest portion goes into operating activities. Mixing these up makes the operating cash flow look artificially high or low depending on which direction you err. A third pitfall involves prepaid expenses and deferred revenue. If you paid twelve months of insurance upfront, that entire payment shows as a cash outflow in the month you paid it, even though the expense is recognized monthly on the income statement. On the cash flow statement, you add back the portion that was not expensed yet. Deferred revenue works in reverse. If a customer paid you six months in advance, the cash came in but the revenue has not been earned yet. You subtract that from net income on the cash flow statement.
Get the Full Details

Software like QuickBooks, Xero, and FreshBooks can generate these statements automatically now. The reports are decent but rarely accurate enough to submit to a lender without manual review. I always pull the report and spend twenty minutes validating the numbers against the bank statements. Most errors come from misclassified transactions, duplicate entries, or categories that were switched around after the fact. One edge case that took me forever to solve involved a client with multiple subsidiaries doing intercompany transactions. The parent company recorded revenue from the subsidiary while the subsidiary recorded an expense. Both entities showed healthy net income. But from a consolidated cash flow perspective, those intercompany transfers canceled out and needed to be eliminated entirely. The standard reporting template did not handle this automatically. I built a reconciliation schedule that identified every intercompany invoice and tagged them for elimination before running the consolidated cash flow statement. Without that step, the operating cash flow was overstated by roughly $34,000 per quarter. Here is the uncomfortable truth about cash flow statements. They do not tell you whether a business is fundamentally viable. A company can show positive cash flow for three years straight and still be deeply unprofitable if it is funding operations through debt or selling off assets. Conversely, a fast-growing company with negative operating cash flow might be making sound long-term investments in receivables and inventory that will pay off. Context matters more than the raw number. You need to read the notes and understand the business model behind the figures.
For most small business owners, generating this statement monthly rather than quarterly makes a dramatic difference. Quarterly reporting lets problems accumulate. You might spot a slow-paying customer in the income statement but by the time the quarterly cash flow statement arrives, three months of overdue invoices have stacked up and there is nothing you can do about it except absorb the delay. Monthly reporting gives you four to six weeks to follow up, adjust credit terms, or renegotiate payment schedules. If your business handles a lot of fixed assets, tracking the gain or loss on asset sales separately is important. The cash received from selling equipment goes into investing activities at the actual dollar amount. But the book value of that asset needs to be removed from your depreciation schedule, and any difference between the sale price and book value appears as a gain or loss on the income statement. The cash flow statement adjusts for this gain or loss because it is a non-cash item that distorted net income. I usually set up a fixed asset register with columns for purchase date, original cost, accumulated depreciation, and current book value. It takes extra time upfront but saves hours during each reporting period. Taxes deserve special attention on the cash flow statement. Income tax expense on the income statement rarely matches the actual tax payment made during the period. You might have deferred tax assets or liabilities that affect the timing. I reconcile the tax payable account each period and adjust the operating cash flow section accordingly. The difference between tax expense and tax paid can easily reach thousands of dollars depending on your depreciation methods and any carryforward losses.
Finally, a word about benchmarking. Industry norms vary significantly. A retail business with high inventory turnover will naturally show different cash flow patterns than a software company with minimal physical inventory. Comparing your operating cash flow margin to the wrong industry average leads to false conclusions. Look at your own trend over time first. If operating cash flow has been declining for four consecutive quarters while net income remains stable or grows, something is eroding your cash position that the profit figure hides. Dig into the working capital changes immediately before the situation becomes unrecoverable.