Why Nobody Talks About the Friction
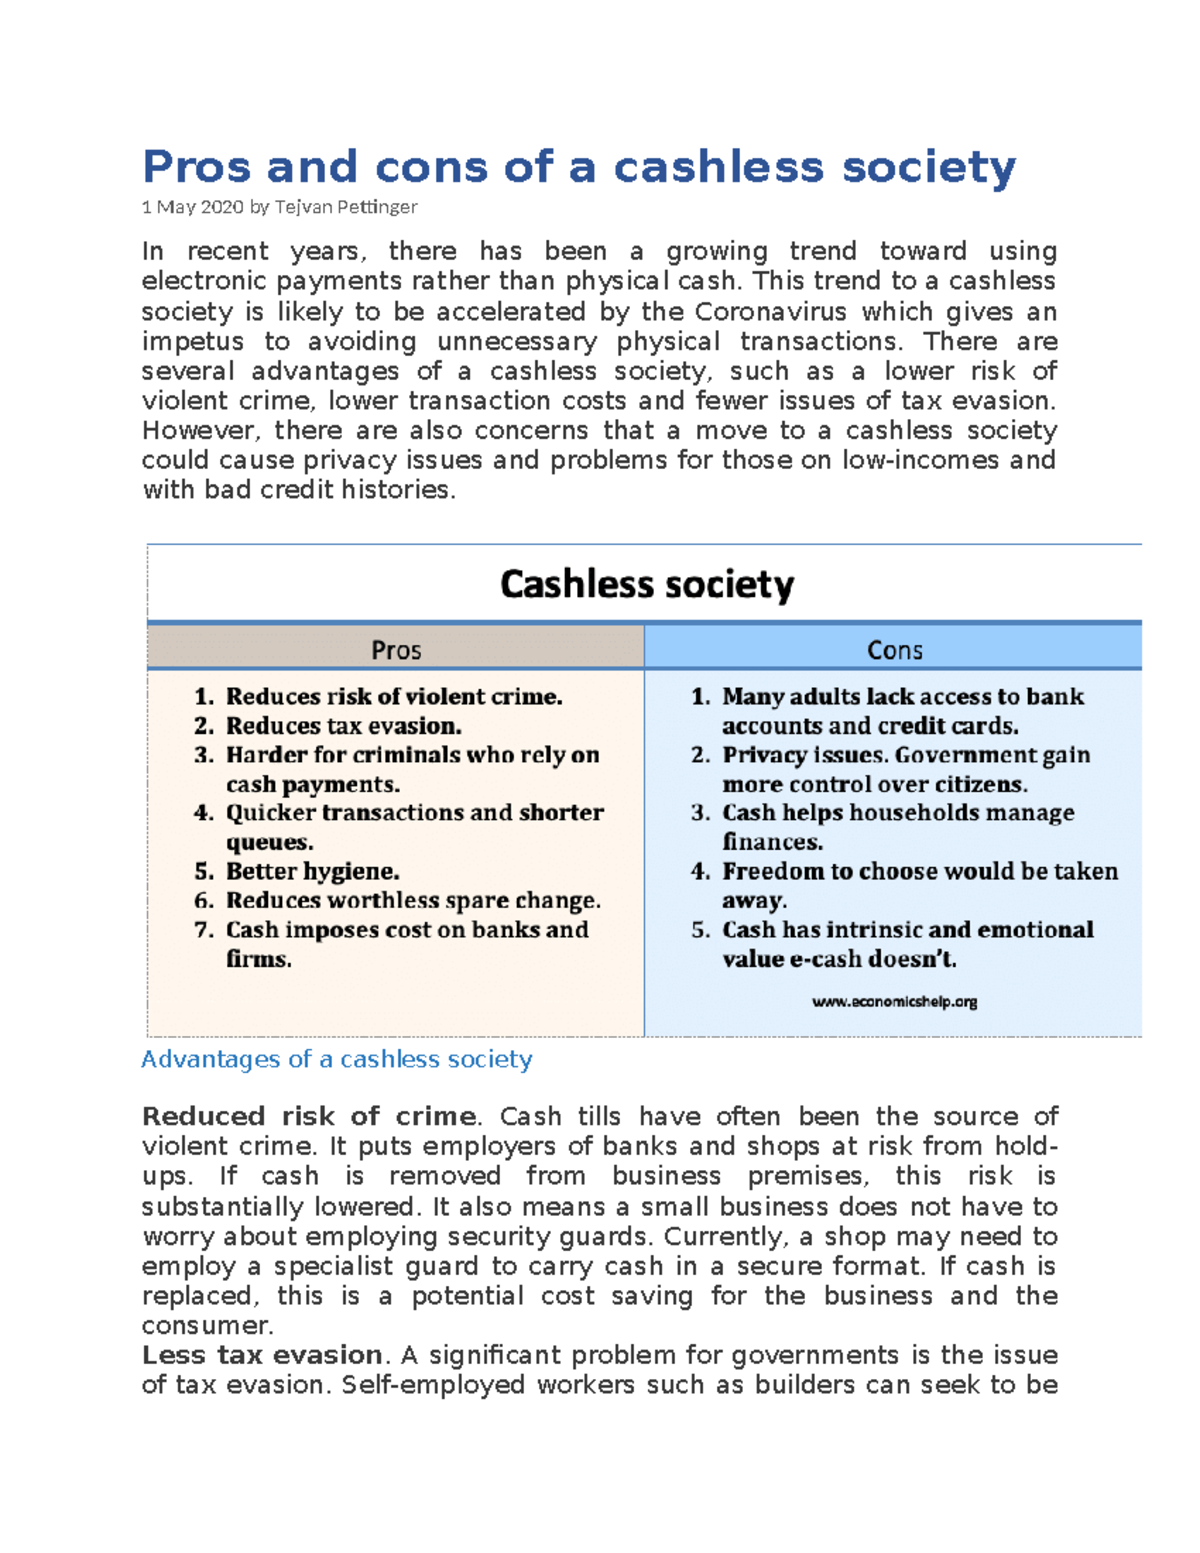
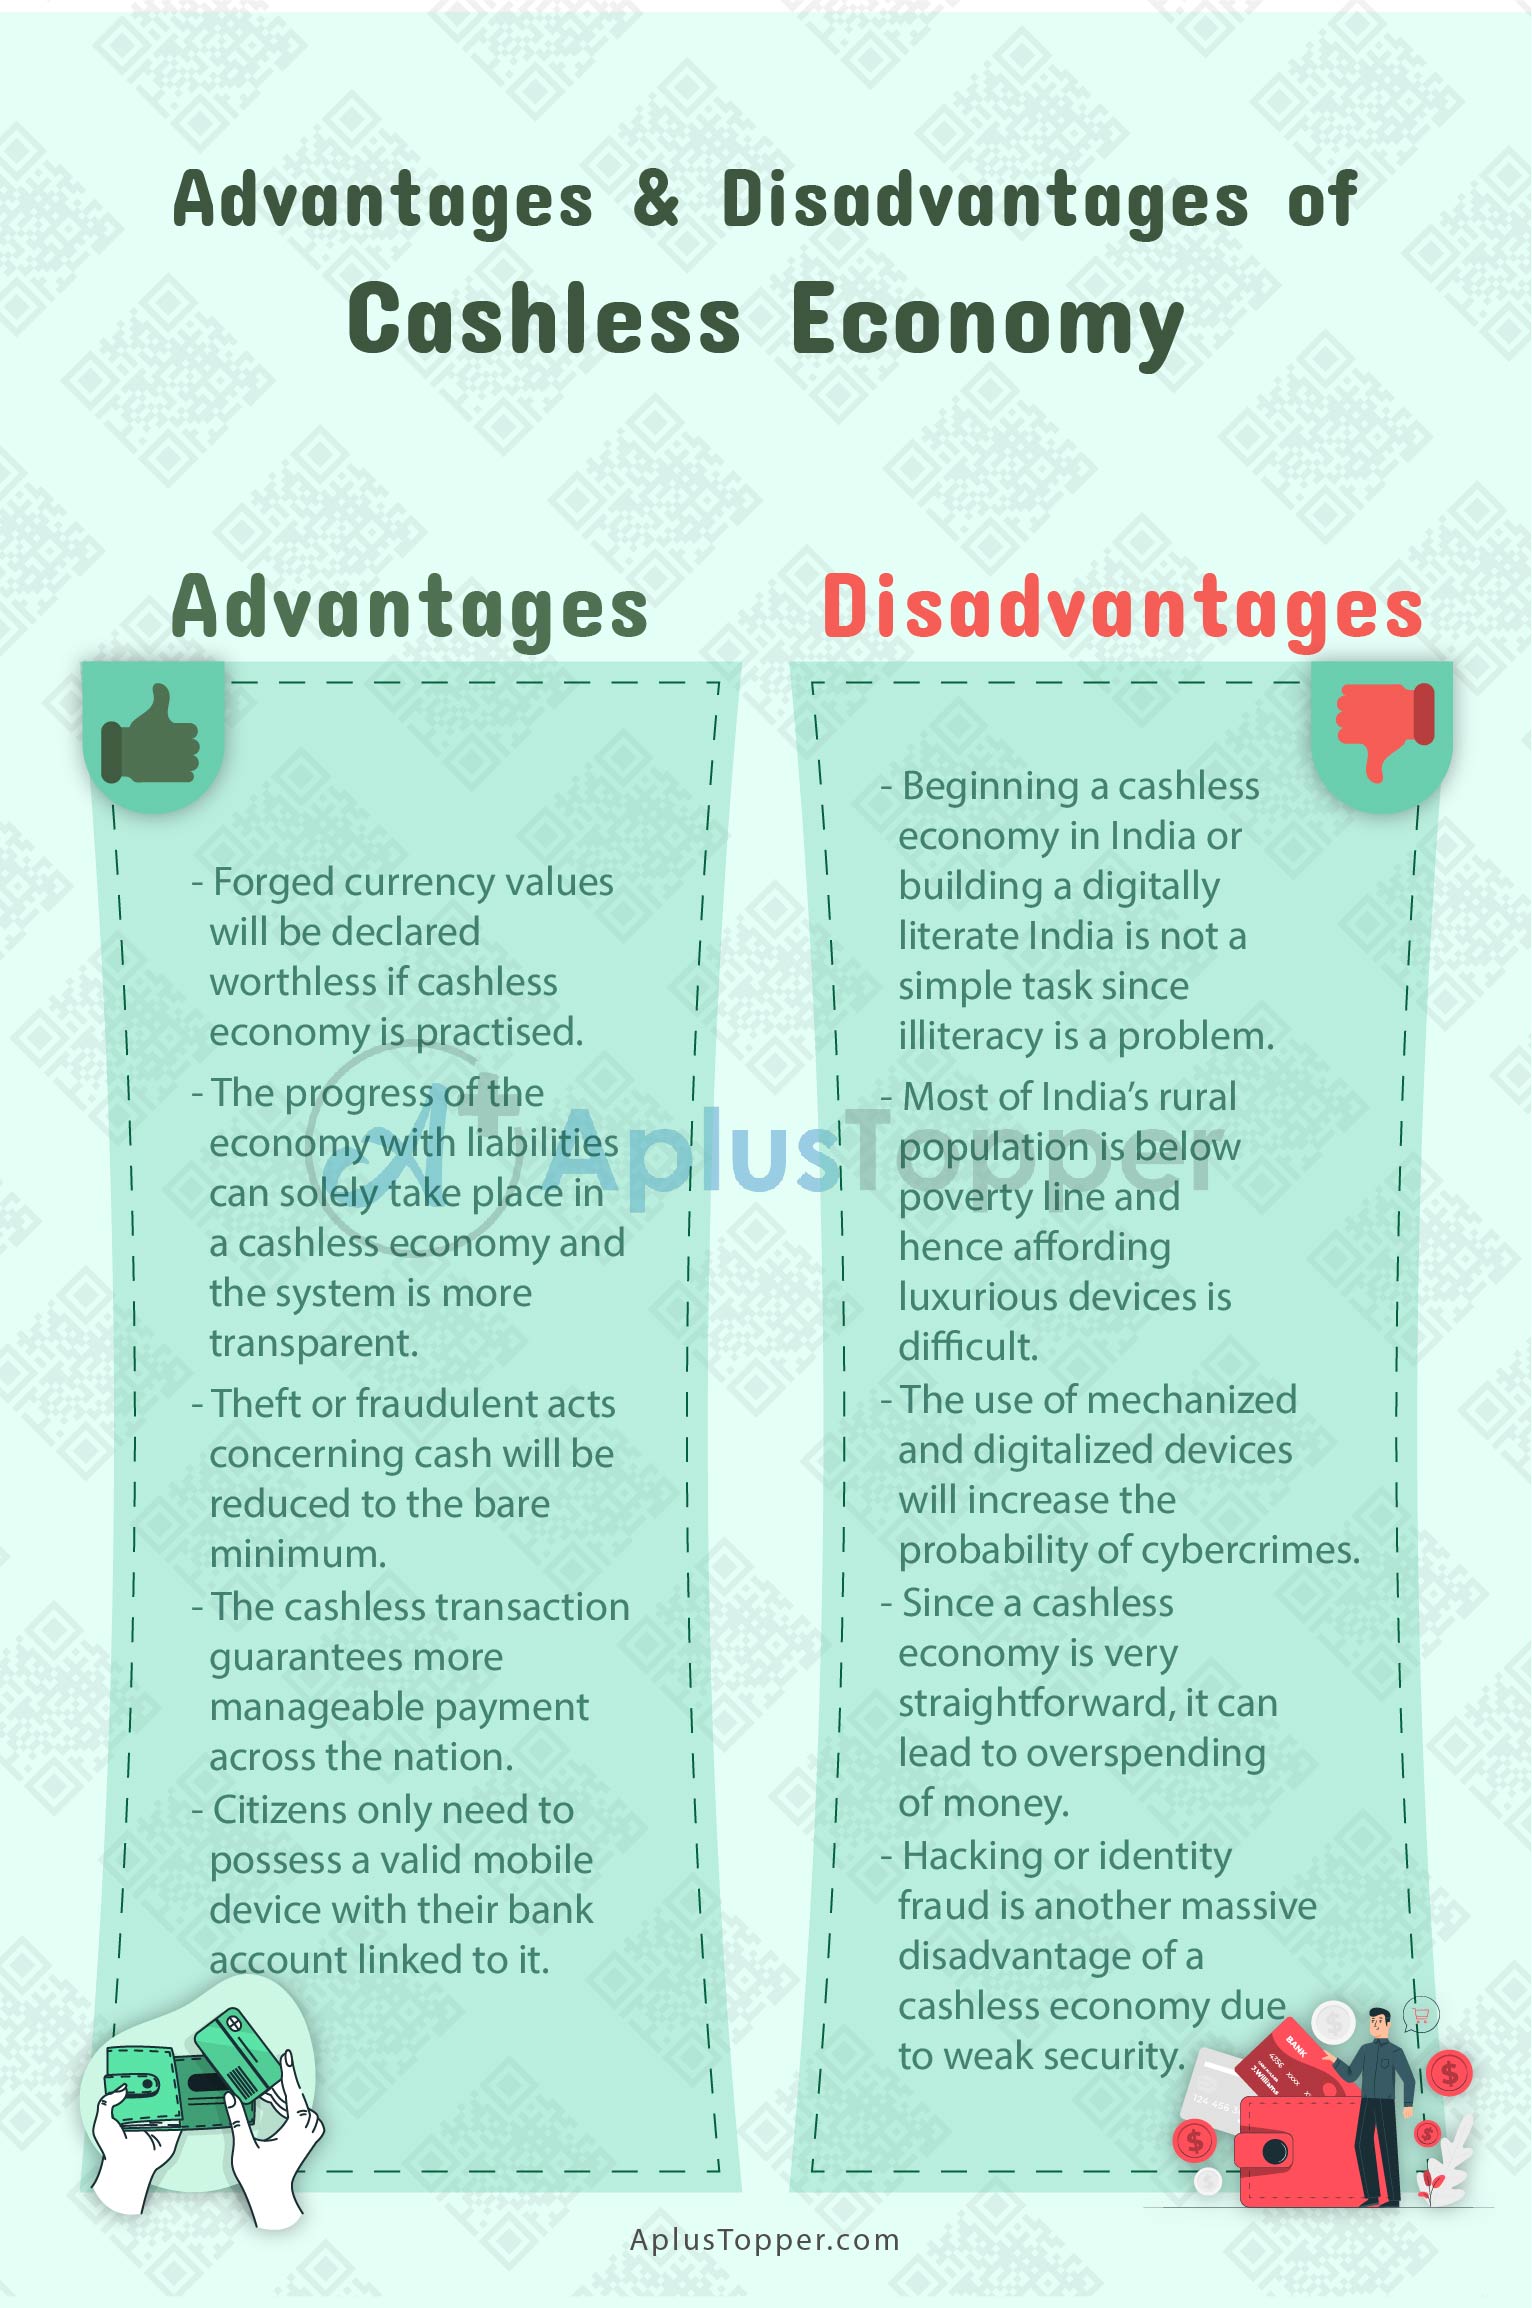
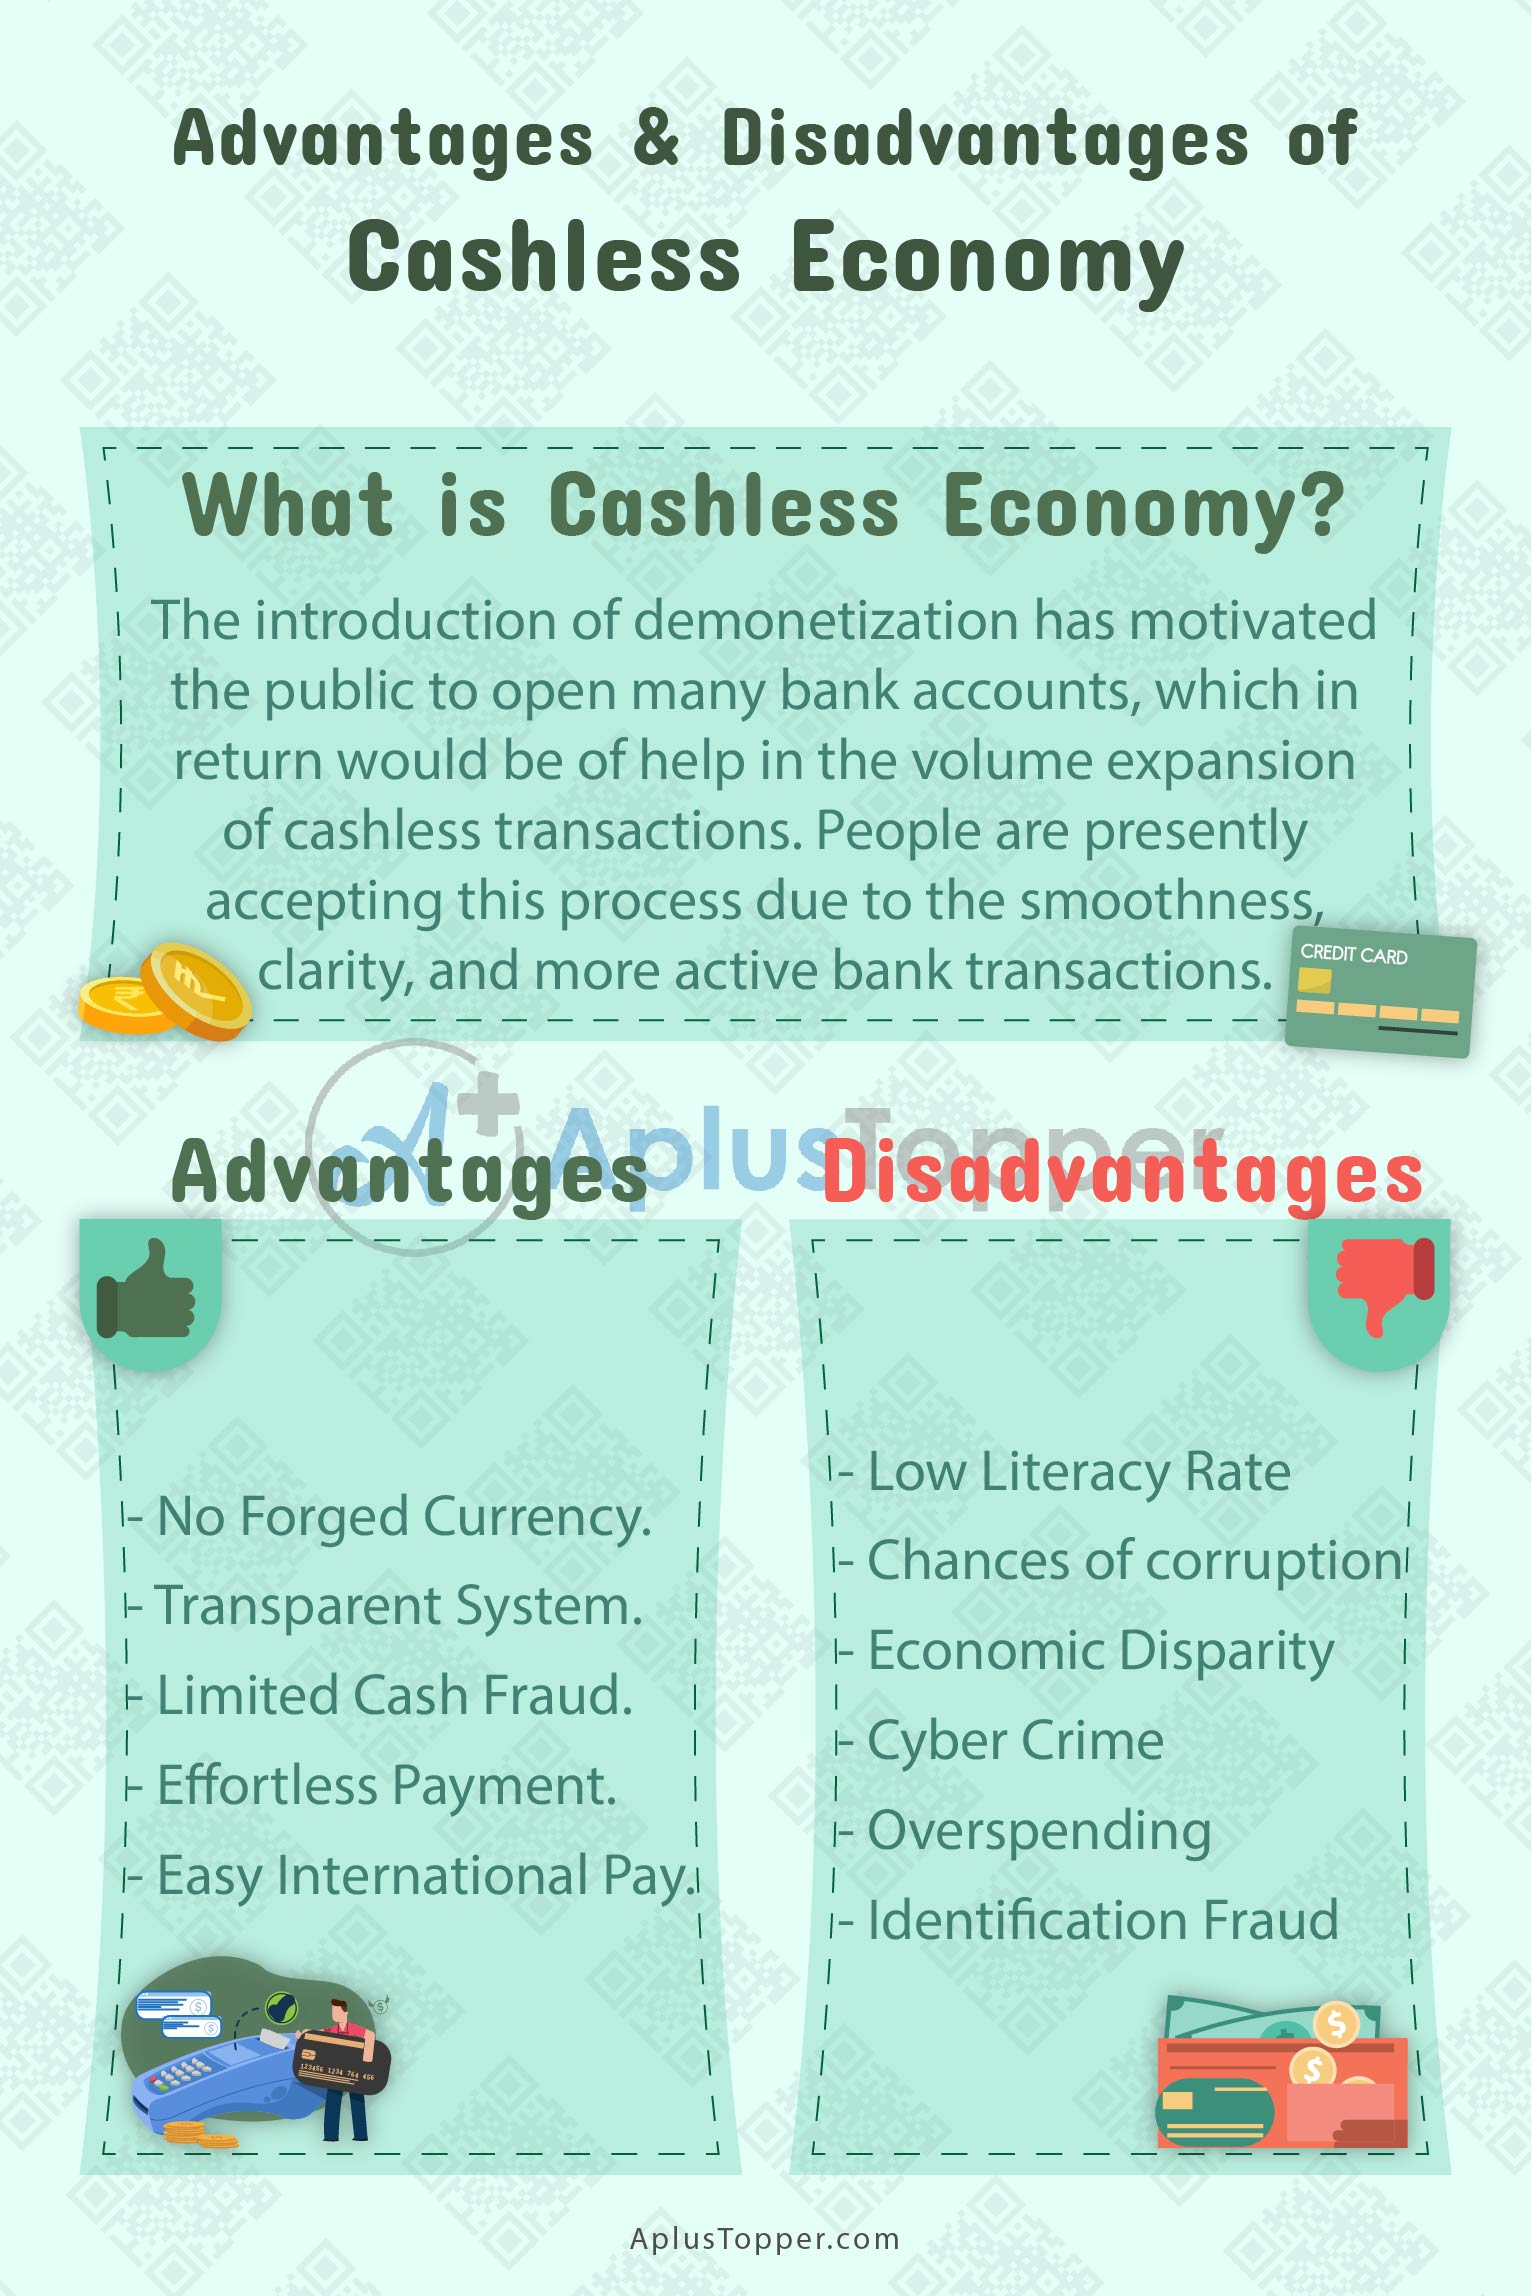
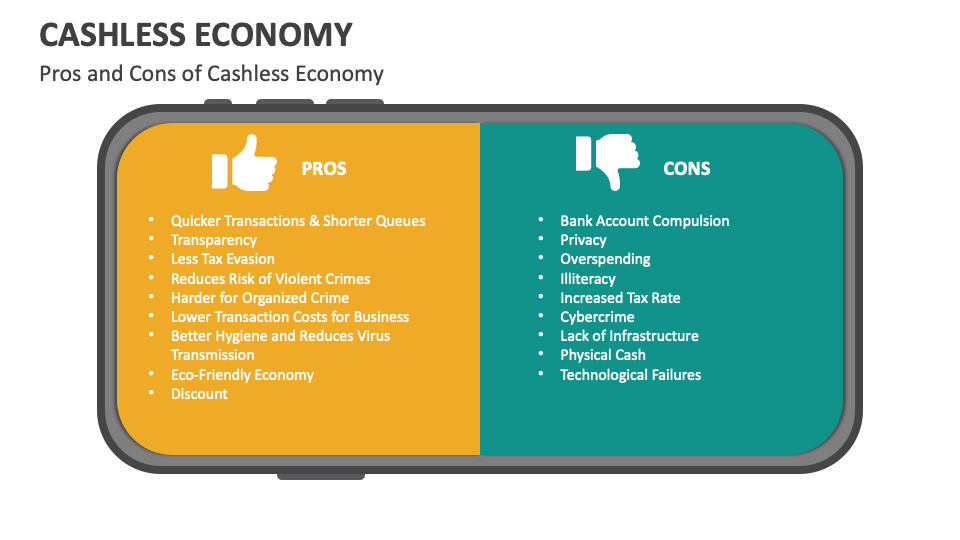
Most conversations about going fully cashless spin in circles. They rehash the same two bullet points for pros and cons without getting into what actually happens when you strip physical money from the system. I've spent years watching this play out at the infrastructure level, dealing with payment processors, bank integrations, and the real-world failures that never make it into opinion pieces. The pro argument usually centers on convenience and reduced crime. Both are real. The con argument tends to center on exclusion and surveillance. Also real. But neither captures the operational mess that shows up once a city or country crosses a certain threshold of cash adoption. When transactions go digital, the friction doesn't disappear. It moves. It shifts from your wallet to the payment rails underneath. That's where the actual story lives.
The Technical Side Nobody Warns About
Here's something most people miss: a cashless system doesn't reduce the cost of money movement. It restructures it. Every tap, swipe, or transfer goes through acquirers, issuers, networks, and gateways. Each layer takes a cut. In cash, that cut is zero. In digital, it averages between 1.5 and 3.5 percent per transaction depending on card type and region. I learned this the hard way when working with a mid-size merchant who switched their entire operation to card-only. On paper, they were saving on cash handling costs, armored transport, and teller time. In practice, those interchange fees ate most of the savings within six months. The owner thought they were losing money to "the bank." They were actually paying the payment ecosystem at every hop between their POS and the customer's issuer.
The Real Pro: Transaction Velocity
Speed is the legitimate advantage. Cash requires physical exchange, counting, and reconciliation. Digital payments are near-instant settlement in most modern systems. Point of sale reconciliation that used to take a store manager two hours at closing now takes maybe fifteen minutes because the batch report pulls directly from the processor's dashboard. This compounds at scale. A city that processes millions of digital transactions daily saves enormous hours in accounting, auditing, and dispute management. The numbers add up fast when you're not physically moving currency around.
Get the Full Details

The Real Con: Exclusion
Unbanked populations don't vanish when cash disappears. They get pushed further out. I've seen this firsthand in rural areas where bank branches closed and mobile coverage was unreliable. People who could manage with cash couldn't manage with a card terminal that dropped connections or an app that required a smartphone most residents couldn't justify buying. The workaround isn't ideological. It's practical infrastructure. Where I've worked on these transitions, the sites that succeeded kept a cash acceptance tier for essential services while nudging everyone else toward digital. Not as punishment. As a bridge.
The Privacy Question Is Not Simple Either
Digital payments create transaction records. That's the feature, not the bug. Governments and institutions see this as a tool for compliance and tax collection. Individuals see it as a surveillance risk. Both are correct. The counter-intuitive part is that privacy loss isn't evenly distributed. Wealthy individuals and corporations already operate digitally. Their transaction data is no more exposed than it would have been before cashless policies. The people who lose the most privacy are those who were previously invisible precisely because they used cash. A single purchase history can reveal more about someone than most people realize. Medical payments, religious donations, political contributions, substance purchases. All documented.
What Breaks When the System Stresses
I remember a specific incident during a regional power outage where ATMs went offline and card networks couldn't authenticate transactions. Small merchants had no way to accept payment and no way to get cash. Customers had no way to get money either. The whole system froze because it had no analog fallback. In cities with stronger cash infrastructure, people could walk to an ATM, withdraw bills, and complete transactions manually. The completely cashless environment had nothing. This isn't hypothetical. It happened in several European cities during storm-related outages in the late 2020s.
The Fraud Shift, Not Fraud Elimination
Cash eliminates certain types of fraud. It doesn't eliminate fraud. Skimming, card-not-present scams, account takeover, and chargeback abuse all grew significantly as cash usage declined. The fraud landscape changed shape. It didn't shrink. Merchants who went fully digital often underestimated chargeback exposure. A cash transaction is final. A card transaction can be reversed 90 days later with minimal explanation. That reversibility is both a consumer protection and a merchant vulnerability. I've seen businesses get hit with sustained fraudulent chargeback campaigns that totalled more than any cash theft they'd ever experienced.
The Currency Sovereignty Angle
This gets political quickly, but it deserves mention. A government that controls the payment rails controls the monetary policy transmission mechanism. Negative interest rates become technically feasible. Capital controls become automated. Emergency liquidity distribution becomes programmable. Some economists argue this is a feature. It allows faster stimulus delivery and tighter control over money supply. Others argue it removes a critical check on state power. Cash as an exit valve from the financial system is a structural constraint that keeps institutions honest. Remove it and the constraint disappears.
Practical Takeaway
If you're evaluating cashlessness for a business or community, don't treat it as binary. The most resilient setups maintain a partial cash layer while optimizing the digital flow for everything else. Keep a small float of bills. Accept cash at essential points. Push digital for volume. The hybrid model isn't idealistic. It's operational reality. The people who go all-in on cashless without contingency planning are the ones who panic when the network goes down. The ones who plan for overlap tend to barely notice the difference on normal days and survive the edge cases without crisis.