How to Actually Use the CBO Budget And Economic Outlook When You Need Real Answers
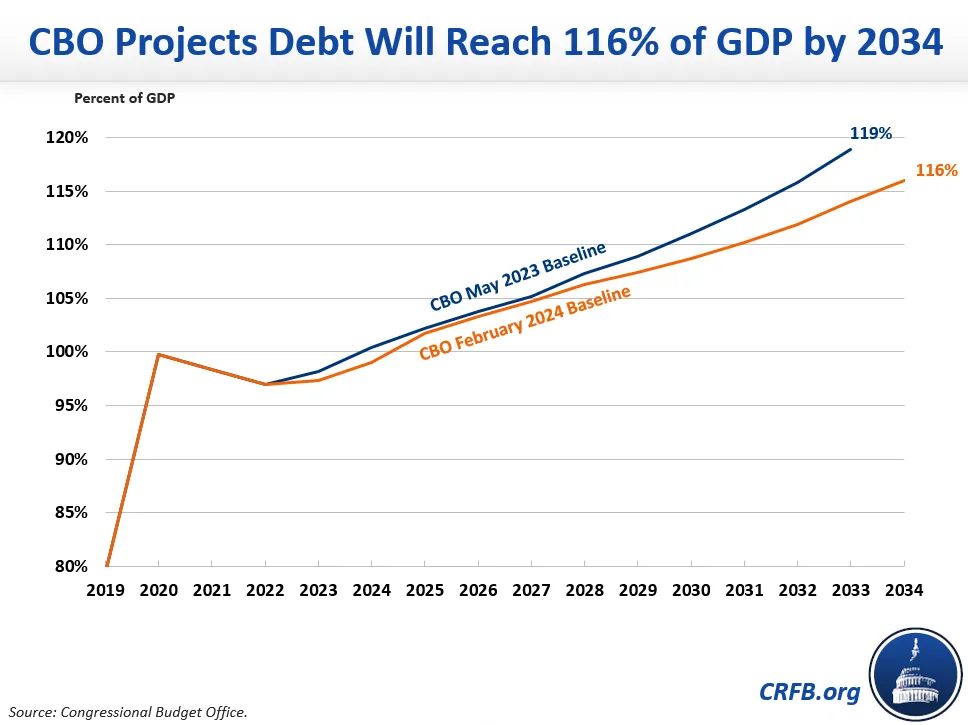
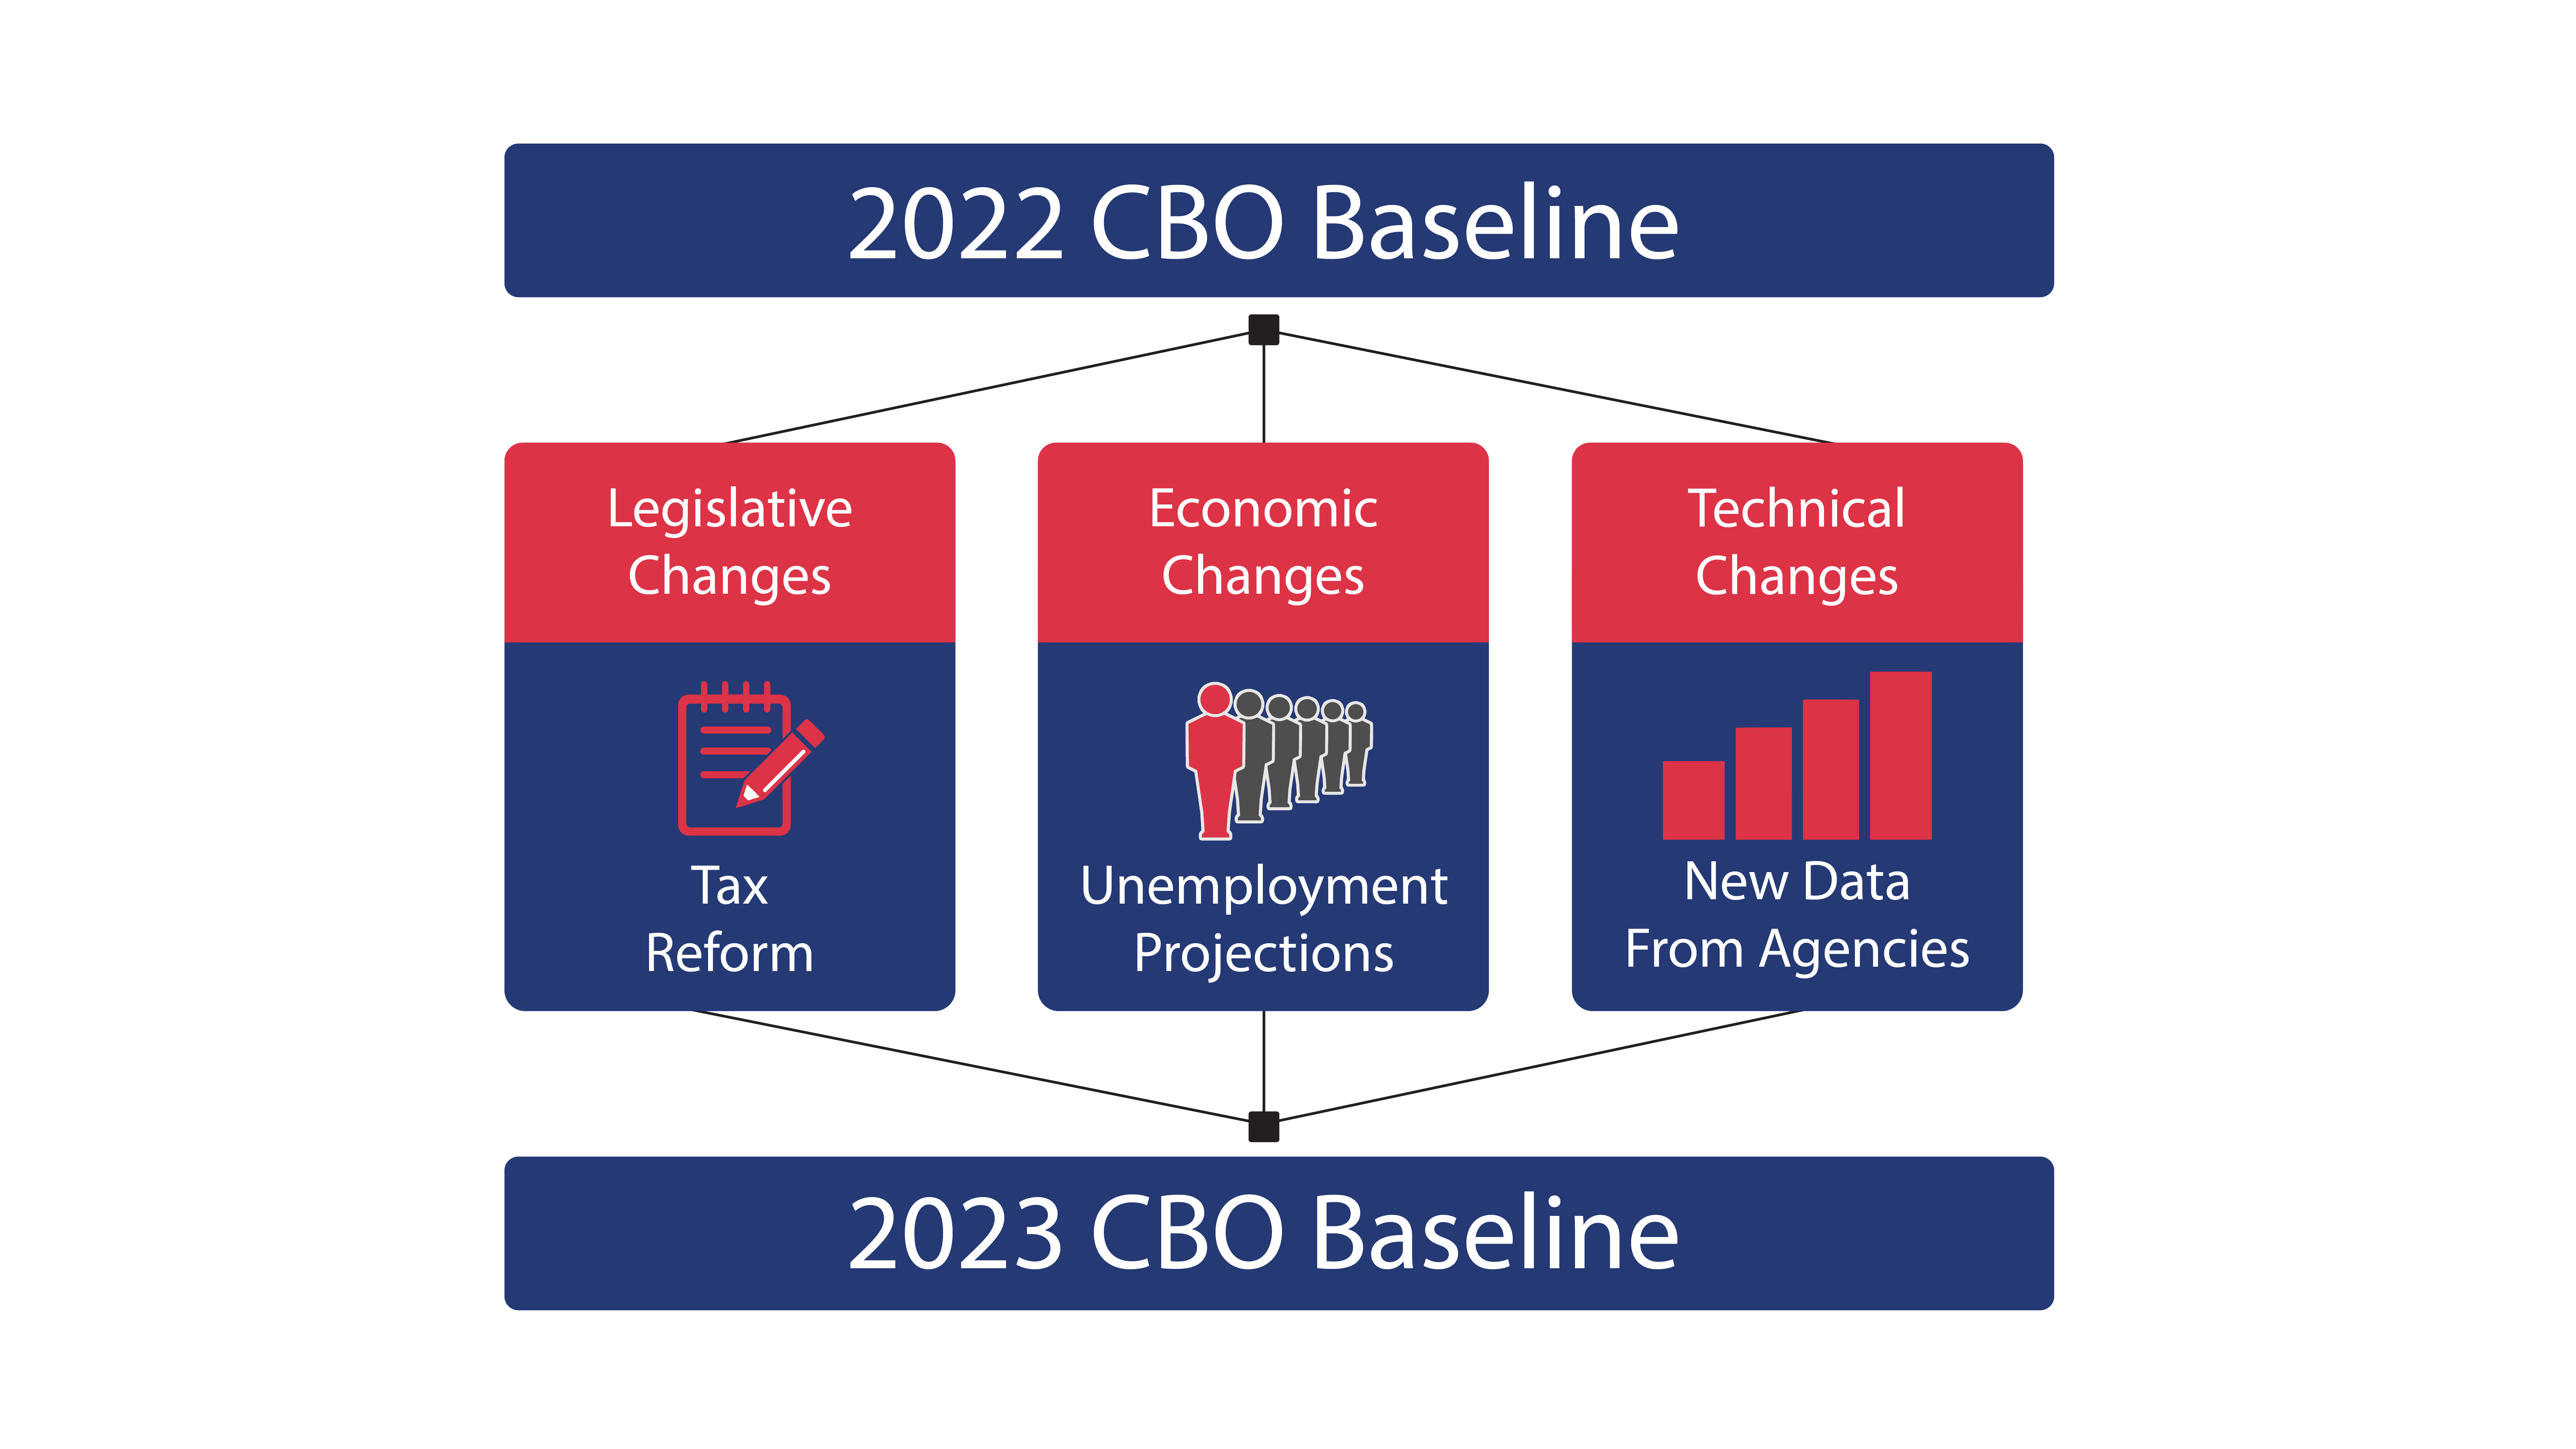
The Congressional Budget Office publishes its Budget and Economic Outlook roughly every two months, and most people skim the executive summary, note the deficit projection, and move on. That misses the part that actually matters if you're doing anything beyond casual reading. The raw numbers are easy to find. Understanding how the assumptions ripple through the projections takes a bit more work. It lives at cbo.gov. No subscription, no paywall, no registration required. The main report lands on the front page under "Publications," and the full package includes a PDF of the report, an accompanying data file, and a set of spreadsheets with the baseline numbers. I always grab the spreadsheet version first instead of working from the PDF. The PDF has the narrative and analysis, which is useful, but the data tables in the spreadsheets are editable and let you pull your own subtotals without doing mental math or opening a calculator app. The CBO Budget And Economic Outlook gives you a ten-year baseline projection of federal revenues, spending, and deficits under current law. It assumes no new legislation changes anything. That is the key word: baseline. It is not a forecast of what will happen if Congress acts. It is a snapshot of where the money goes if the laws on the books stay exactly as they are. The economic assumptions attached to it cover GDP growth, unemployment, inflation, interest rates, and population. Those assumptions drive everything else.
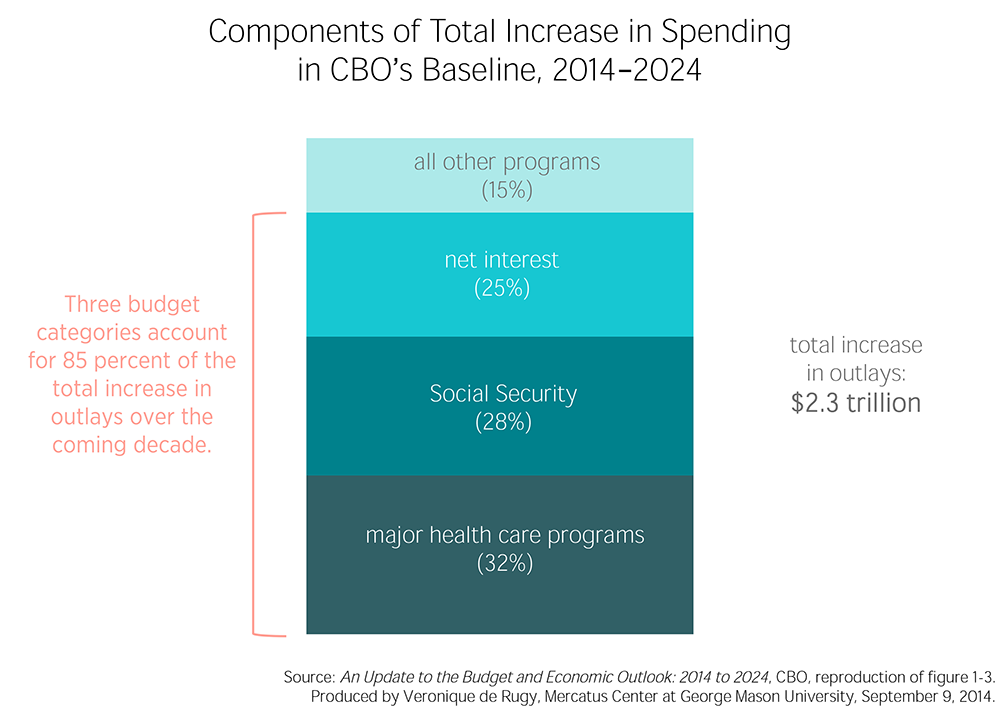
Download the latest report and the associated spreadsheet. Open the revenue and outlay tables. Cross-reference the interest cost section because that number changes every cycle based on revised debt projections. Most analysts forget to check whether the interest estimate rolled forward or got reset to zero when new debt data came in. I once spent twenty minutes chasing a discrepancy in the deficit line before realizing the CBO had updated the debt outstanding figure mid-cycle. The narrative didn't call it out in big bold letters. It was buried in a footnote on page 34 of the appendix. Last year I was reconciling a client's internal model against the CBO baseline and the numbers refused to line up on mandatory spending. Discretionary spending matched perfectly. Defense and nondefense were clean. But the mandatory side was off by roughly four billion dollars in year three of the projection. I went through the tables twice, then triple-checked the formula. Nothing added up. I ended up reading the methodology appendix for the scorekeeping section and found that the CBO had applied a different scoring rule for certain health program provisions that are tied to premium subsidies. The narrative summary had lumped those into a single line item without breaking them out. My workaround was to pull the individual program tables from the supplemental data and manually split the line item by matching the code references in the technical appendix. It took about forty-five minutes total but saved me from delivering a wrong number to someone who would have noticed immediately. The deficit number in the headline is not the same as the primary deficit. The headline figure includes net interest payments on the debt, which means the deficit can actually move against your intuition. If interest rates rise faster than growth, the deficit widens even if discretionary and mandatory spending stay flat. The CBO makes this clear in the data, but people reading quickly skip past the interest column and latch onto the total.
Another thing: the baseline assumes current law holds, which means provisions that are scheduled to expire do expire in the model. Sequestration levels, tax credit extensions, farm bill offsets — they all have built-in expiration clocks. The CBO does not project what policymakers will likely do. They project what the statute says. That distinction matters a lot if you are trying to use the report for actual planning.
Get the Full Details
Limitations You Should Accept Up Front
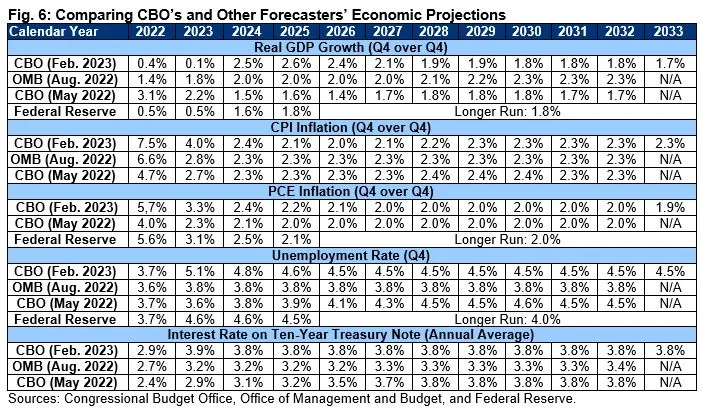
The CBO baseline is a useful reference point, not a crystal ball. It cannot account for legislative action, unexpected economic shocks, or changes in administrative policy. The economic assumptions are based on the Administration's forecast at the time of publication, which means there is already a layer of institutional bias baked in. If the Treasury Secretary releases a more dovish GDP estimate the week before the CBO publishes, the outlook shifts without any change in fiscal policy. That is just how the process works. The ten-year window is another constraint. If your planning horizon extends beyond a decade, you need to extrapolate. The CBO does not publish beyond ten years in the standard report. Some researchers build their own long-term models, but those require accepting that the assumptions will drift further from reality the longer the time horizon gets. There is no fix for that. You just document it.
When to Use It and When Not To
Use the CBO Budget And Economic Outlook when you need a legally grounded reference point for fiscal analysis, when you are comparing projected revenues against actual collections, or when you need an independent baseline to benchmark your own models against. Do not use it as a standalone forecast for investment decisions or lobbying strategy. The report is descriptive, not predictive. It tells you what would happen under current law. It does not tell you what will happen. If you need something that incorporates likely legislative outcomes, you have to layer in your own assumptions about what Congress might pass. The CBO produces separate cost estimates for specific bills, but those are case-by-case and not bundled into the baseline report. For rough scenario planning, the standard approach is to take the baseline, apply your own adjustment factors for expected legislation, and flag the adjustments transparently. That way anyone reading your work knows where the CBO data ends and your own judgment begins.