So You're Stuck on CAPM and Need It to Click
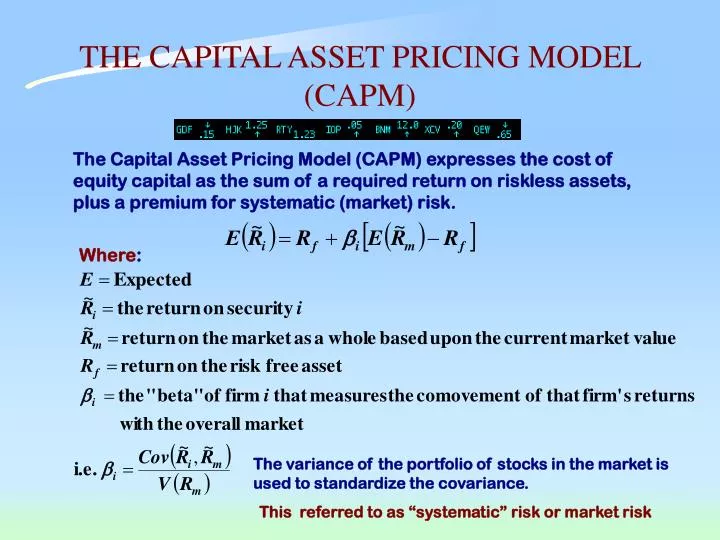
Most people blow through the basic formula without actually understanding what the output means or how it breaks down in real portfolio work. The Capital Asset Pricing Model itself is straightforward. R = Rf + (Rm - Rf). Expected return equals the risk-free rate plus the asset's beta times the market risk premium. That's it on paper. On paper. Here's the part nobody warns you about: the model assumes you can pin down a single, stable beta for any asset, and that the market portfolio is observable and efficient. Neither is true in practice, and that gap is where your grade or your actual return estimation goes sideways.
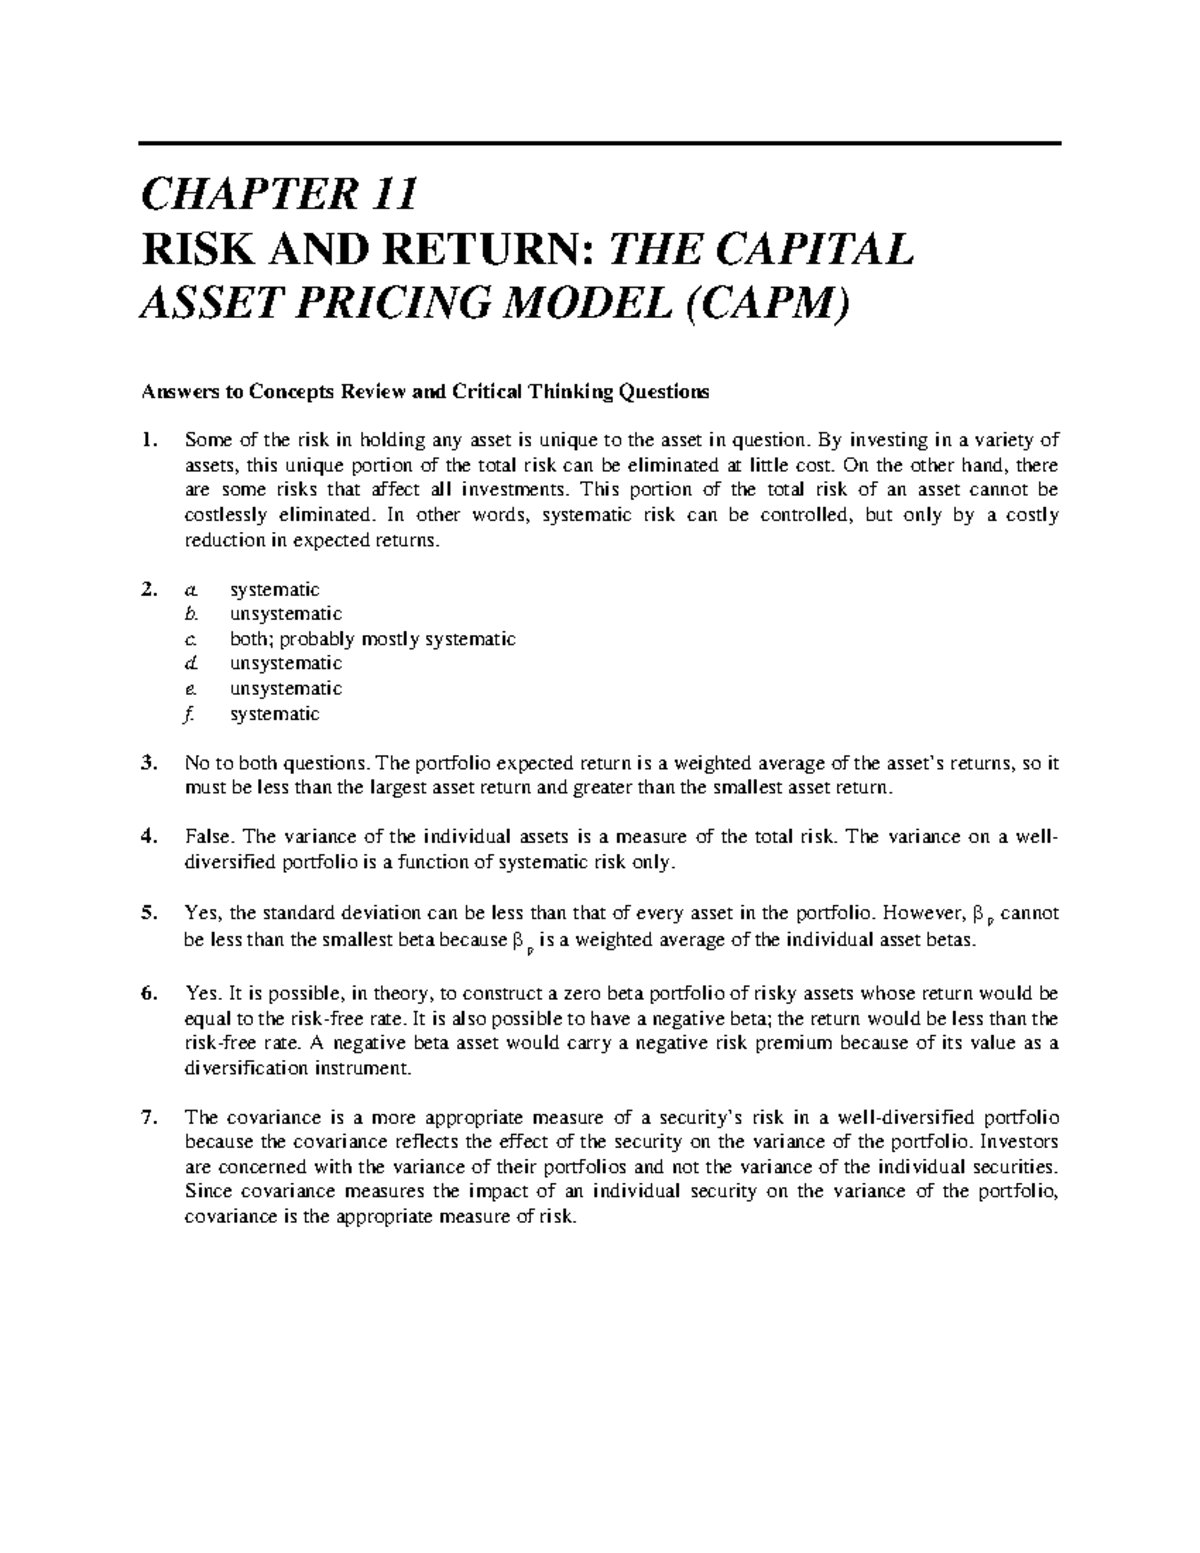
Chapter 11 Capital Asset Pricing Model Capm Yola
When I was working through Chapter 11 material, the Yola resources laid out the standard approach well enough. But the real friction shows up when you're expected to apply it beyond textbook numbers. I remember building a quick valuation for a mid-cap industrial stock where the textbook beta from Yahoo Finance was 1.24, but the company had just restructured its debt and shifted heavily into capital-intensive projects. A raw betas of 1.24 was clearly wrong for forward-looking expected returns. I adjusted it using the Hamada equation to unlever the beta, then relevered it at the firm's target capital structure. The difference between the unadjusted and adjusted beta shifted the cost of equity by roughly 1.8 percentage points. That's not a rounding error in any real decision. Here's what textbooks don't emphasize enough: beta is a backward-looking statistical estimate, not a forward-looking truth. It changes over time. It's sensitive to the lookback window you choose, the frequency of data points, and whether you use daily, weekly, or monthly returns. I typically run beta estimates using 2 to 5 years of monthly returns rather than daily, because daily data introduces microstructure noise that inflates estimation error without adding signal. The difference between a monthly and daily beta estimate for the same stock can easily be 0.15 to 0.30 in absolute terms. Another thing that trips people up: the market risk premium. Textbooks will tell you to use 5 to 7 percent depending on the source. But if you're valuing a stock in a emerging market or a regulated industry, that premium doesn't transfer cleanly. I once saw a student use the full US market risk premium for a utility company whose revenue was heavily tied to long-term government contracts with capped returns. The resulting cost of equity was way too high because the equity wasn't really exposed to full market swings. The workaround was using a sector-specific or country-specific risk premium adjustment, or even pulling implied equity risk premiums from CDS spreads and bond yields for that particular market segment.
The CAPM framework also breaks down when you try to apply it to assets with non-linear risk profiles. Options, convertible bonds, and companies with significant contingent value don't have a constant beta. Their effective beta changes with the underlying price movement. If you're doing corporate finance work or valuation, you need to recognize where the model's constant-beta assumption is quietly lying to you. That's not a reason to abandon CAPM entirely, but it is a reason to know when your output is unreliable.
Get the Full Details
How to Actually Use This in Practice
Start by getting your inputs right. The risk-free rate should match the maturity of your cash flows. If you're discounting a 10-year project, use a 10-year government yield, not the overnight rate. This alone fixes a lot of common student errors. For beta, run at least two estimates. One with a 2-year lookback and one with 5 years. If they differ by more than 0.20, flag it. Don't just pick one and move on. Check whether the firm's business mix changed during the lookback period. If it did, the raw regression beta is contaminated by structural shifts that have nothing to do with market risk. When adjusting levered to unlevered beta, make sure you're using the right formula. The standard Hamada approach is u = l / [1 + (1 - t)(D/E)], where t is the marginal tax rate. Some sources simplify by ignoring taxes, which understates the unlevered beta slightly. For textbook problems the difference is small. For actual work it matters.
After you relever, cross-check your cost of equity against comparable companies in the same sector. If your result is more than 2 percentage points away from the peer median, go back and check your inputs. Usually it's the D/E ratio or the tax rate that's off. The Yola Chapter 11 materials cover the mechanics well, but the assignments often skip the adjustments that separate a passing grade from something you could actually defend in a professional setting. Use the model. Understand its limits. That's the whole point.