Understanding Economic Growth: What Actually Moves the Needle
Chapter 12 Section 3 Guided Reading Review Economic Growth
Economic growth is really just one thing: an increase in the production of goods and services over time. That's it. But the mechanisms behind it are where things get messy, and most people gloss over that part because the textbook makes it look clean. I've graded enough guided reading responses to know where students consistently trip up, and it's not because the material is hard. It's because the way it's tested doesn't match how these concepts actually work in practice. Let me walk through this the way it should be understood, not the way it's usually presented.
Productivity Is the Core Metric
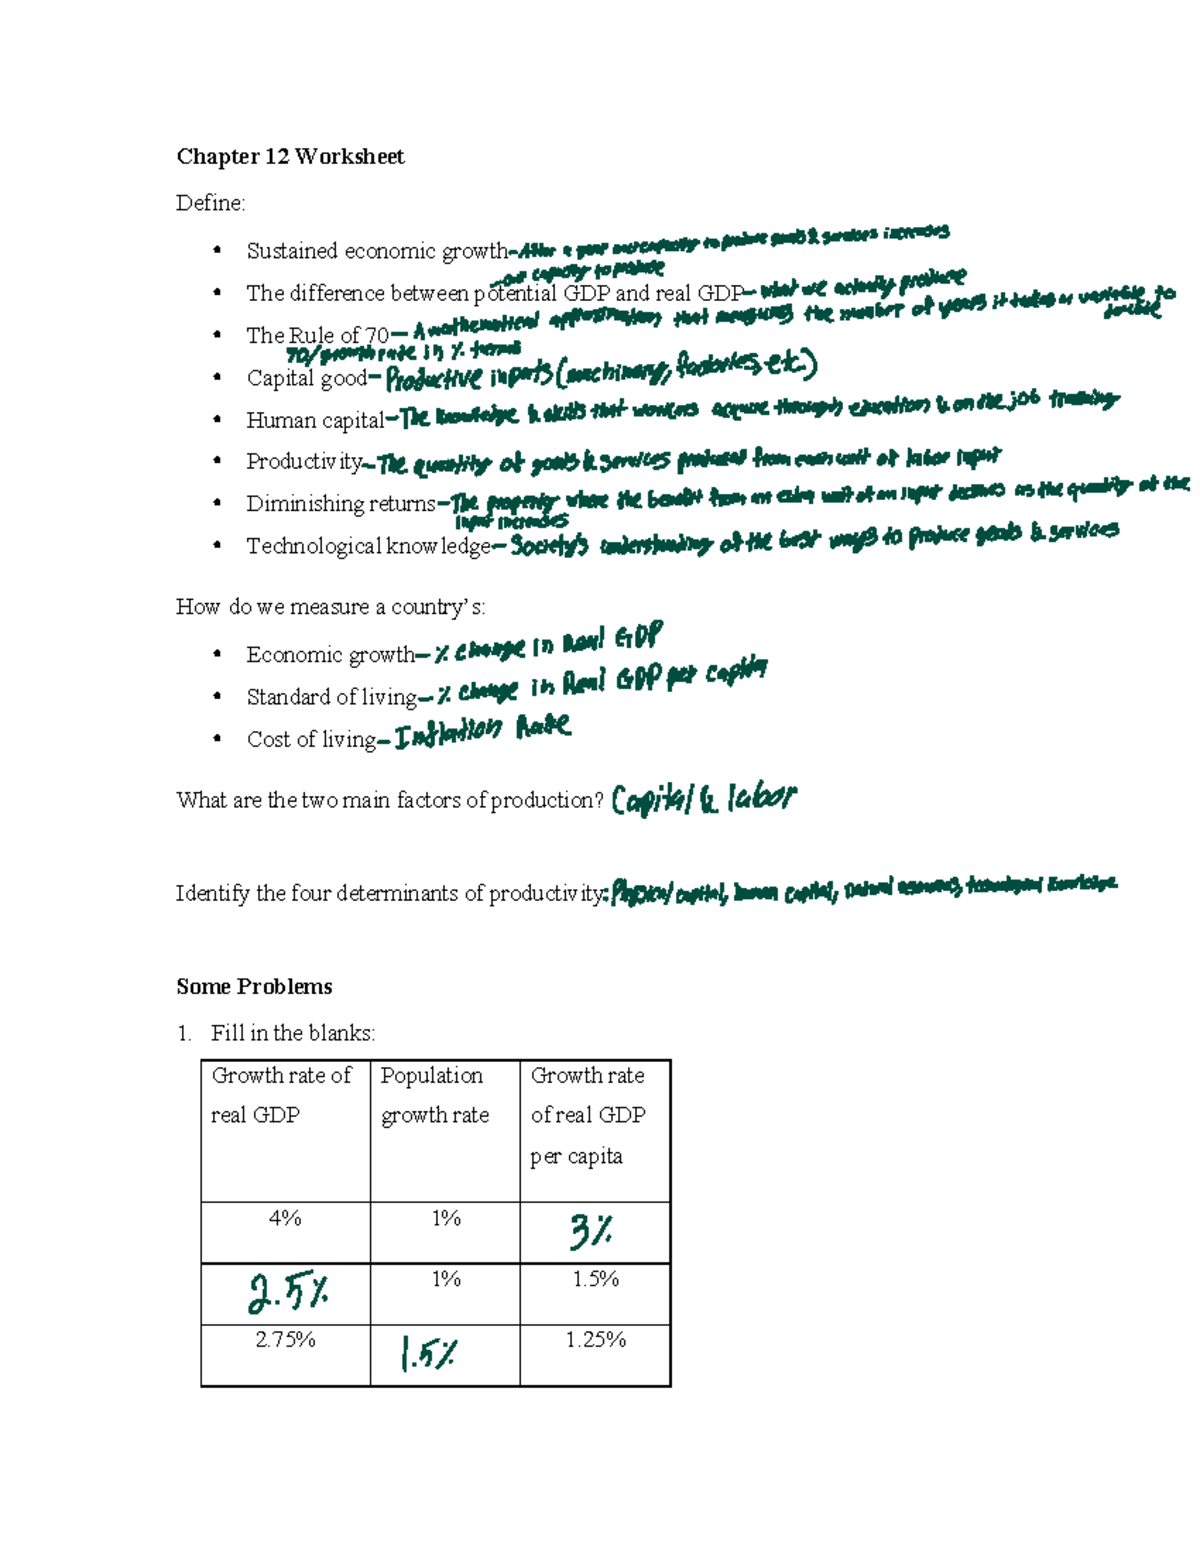
Productivity measures output per unit of input. That's the starting point for everything in this chapter. When productivity rises, the economy can produce more without requiring more resources. This is fundamentally different from just having more resources. I saw a student once confuse a resource boom with genuine productivity gains on a test. She lost points because she described the situation correctly but attributed it to the wrong driver. It's a common mistake. The formula itself is simple—total output divided by total input—but applying it correctly requires understanding what counts as input. Labor hours? Capital investment? Both? The answer depends on what you're measuring. In macroeconomics, we usually look at labor productivity (output per worker or output per hour worked) because it's the most tractable measure for comparing economies over time. Here's the thing textbooks don't emphasize enough: productivity growth is not linear. The United States experienced rapid productivity gains from roughly 1870 to 1970, driven by electrification, internal combustion, and mass production. Then there was a noticeable slowdown in the 1970s and early 1980s. Most economists attributed this to measurement difficulties and the transition from manufacturing to services. Since the late 1990s, IT and digital technologies have reignited productivity growth, though analysts debate whether we're in a sustainable trend or a temporary surge. Understanding these patterns matters because it changes how you interpret guided reading questions that ask about causes versus symptoms.
Factors That Drive Economic Growth
The guided reading typically breaks these into several categories. I'll go through them with the caveats that actually matter. This is machinery, buildings, infrastructure, and tools used to produce goods and services. More physical capital generally means higher productivity, but only up to a point. The principle of diminishing returns applies here. If a factory already has two forklifts and you add a third, the third one won't contribute as much additional output as the first one did. Students often miss this on exams because the textbook examples tend to assume you're working from a low base. In the real world, developed economies face diminishing returns on physical capital investment much more frequently than developing ones do. I ran into this exact issue when helping a colleague's daughter with her AP Economics homework. She was working through a problem set that asked students to calculate growth projections based on capital accumulation alone. The numbers worked out perfectly in the textbook. In reality, you'd need to account for depreciation, maintenance costs, and the fact that new capital is only useful if you have workers who know how to operate it. I told her to flag the assumption in her answer and move on. Teachers appreciate that kind of critical thinking even when it's not explicitly graded.
Get the Full Details
Human Capital
Education, training, experience, and health all feed into human capital. This is arguably the most important factor for long-run growth because it's the only one that doesn't suffer from diminishing returns in the same way. A worker who learns a new skill doesn't displace the old one—they add to it. This compounds over time. The counter-intuitive part here is that the quality of education matters more than the quantity. Years of schooling is an easy metric to measure, but a degree from an underfunded program with outdated curricula won't boost productivity the way targeted vocational training or on-the-job learning might. South Korea and Singapore invested heavily in education quality, not just enrollment rates, and that's a key reason their productivity trajectories diverged from other developing nations in the late twentieth century.
Natural Resources
Land, water, minerals, timber—these matter, but they matter less than most people think for advanced economies. The Netherlands has almost no significant natural resources and is one of the wealthiest countries per capita. Botswana has diamonds and still struggles with growth volatility. The resource curse is a real phenomenon where abundance of natural resources correlates with slower economic growth, usually because it distorts incentives away from education and institutional development. If your guided reading includes a question about why some resource-rich countries don't grow faster, the answer isn't in the resources. It's in the institutions that manage them.
Technological Knowledge
This is the big one. Technology doesn't mean gadgets. It means better ways of doing things. The printing press was technology. The assembly line was technology. Search algorithms are technology. What all of them share is that they allow the same inputs to produce more output, or the same output with fewer inputs. Technological progress is non-rivalrous. When I use a software program, that doesn't prevent you from using it too. This is fundamentally different from physical capital, which is rivalrous—a machine I'm operating can't simultaneously be operated by you. Non-rivalry is why technological knowledge can drive sustained growth without the diminishing returns that constrain physical capital accumulation.
Institutions and Incentives
Most introductory textbooks mention property rights and the rule of law in a single paragraph, but these are foundational. Without enforceable contracts and clear ownership, there's no incentive to invest in capital, acquire education, or innovate. This isn't a theoretical argument. It's observable in every economy that has experienced sustained growth. China's economic transformation since 1978 wasn't primarily about adding more factories. It was about allowing people to own the output of their labor. That incentive shift unlocked productivity that existed but was suppressed under the previous system. The physical capital followed the incentives, not the other way around.
Common Pitfalls on the Guided Reading
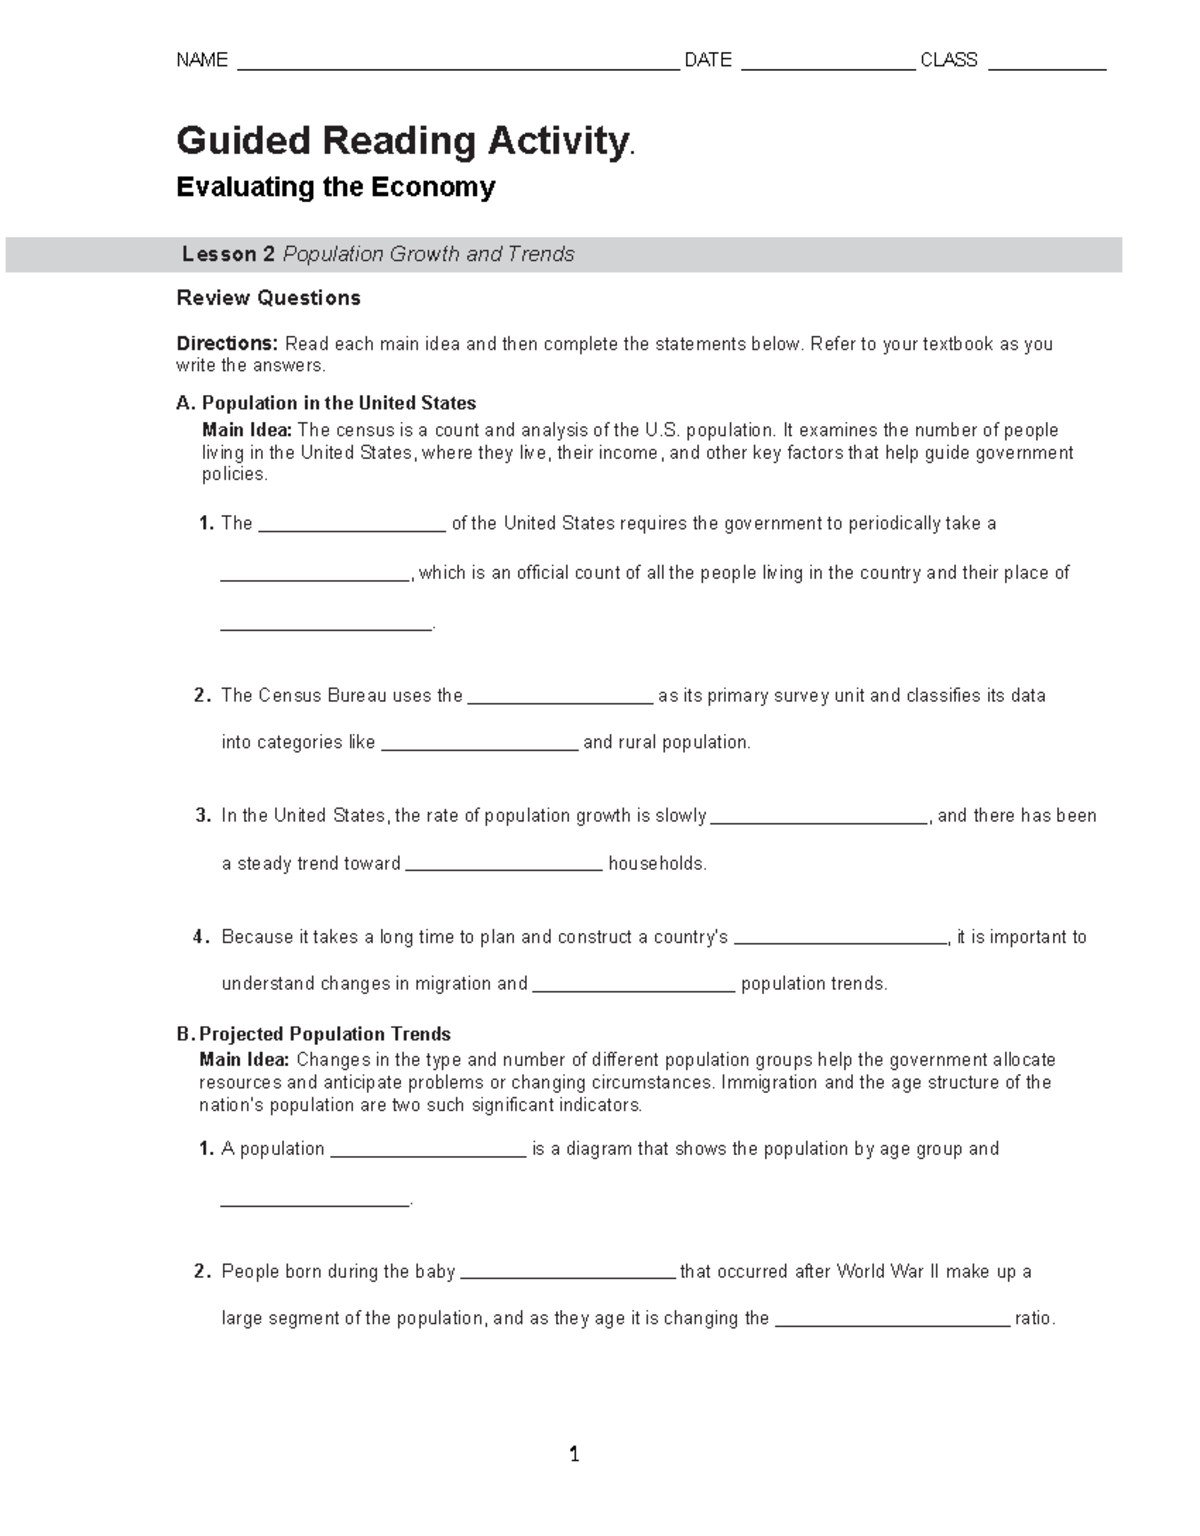
Students regularly mix up economic growth with economic development. Growth is quantitative—more output. Development is qualitative—better institutions, higher standards of living, improved health and education outcomes. You can have growth without development. Many countries have experienced GDP growth while inequality increased and human development indicators stagnated. Another trap is assuming that saving and investment automatically lead to growth. They can, but only if the investment is productive. If a country channels savings into unproductive projects—white elephant infrastructure, speculative bubbles, rent-seeking ventures—the investment doesn't translate into growth. The 2008 financial crisis is a recent example of massive investment that destroyed rather than created productive capacity. When answering guided reading questions, look for keywords. "Sustained" growth implies long-term trends, not short-term business cycle fluctuations. "Per capita" growth matters more than aggregate growth when discussing living standards. An economy can grow because its population is growing, but that doesn't mean individuals are better off.
A Practical Note on Studying This Material
If you're working through the Chapter 12 Section 3 Guided Reading Review Economic Growth material, don't just memorize definitions. The questions will test your ability to distinguish between factors and to apply them to specific scenarios. Practice identifying which growth driver is at work in a given passage. Is a country building more schools? That's human capital. Is it passing laws protecting intellectual property? That's institutional. Is it discovering a new oil field? That's natural resources, and you should note the potential for the resource curse. The most useful exercise I've found is to take any news headline about an economy and classify the growth factors involved. A story about Germany investing in renewable energy infrastructure involves physical capital and technological knowledge. A story about Vietnam attracting foreign manufacturing investment involves physical capital formation and institutional quality. Doing this consistently builds the pattern recognition that multiple-choice and short-answer questions require. One last thing. The chapter will likely present growth models—maybe the Solow model, maybe just a simplified framework. Understand what these models assume and what they leave out. They abstract from institutional change, from distributional questions, from the role of money and financial systems. That's fine for an introductory level. But don't mistake the model for the territory. Real economies are messier, and the guided reading questions sometimes test whether you remember that distinction.

If you hit a wall on a specific question from the review, the issue is usually a vocabulary problem. Make sure you can distinguish between productivity and production, between capital and capital goods, between technological knowledge and technology itself. These distinctions are small but they determine whether your answer is correct or incorrect.