What the Chapter 13 Bankruptcy Worksheet Actually Does
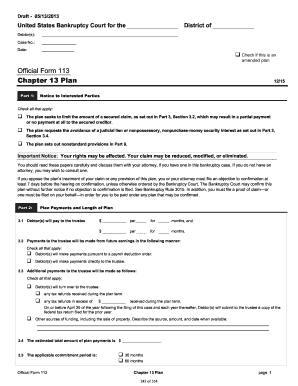
A Chapter 13 Bankruptcy Worksheet is a practical tool for working out the numbers before you file. It tracks your monthly income, your allowed expenses under the IRS standards or your actual spending, and your disposable income so you can figure out what a repayment plan would look like. The goal is simple: show the court that you can pay a certain amount every month for three to five years and come out the other side with a dischargeable balance. The problem is that most people treat it like a generic expense tracker. That approach will break down. The worksheet needs to mirror the logic of the bankruptcy code, the local rules, and the trustee's expectations. Get that wrong and you'll either propose a plan that fails confirmation or leave money on the table that could have been used to pay down secured claims more aggressively.
How to Fill Out a Chapter 13 Bankruptcy Worksheet
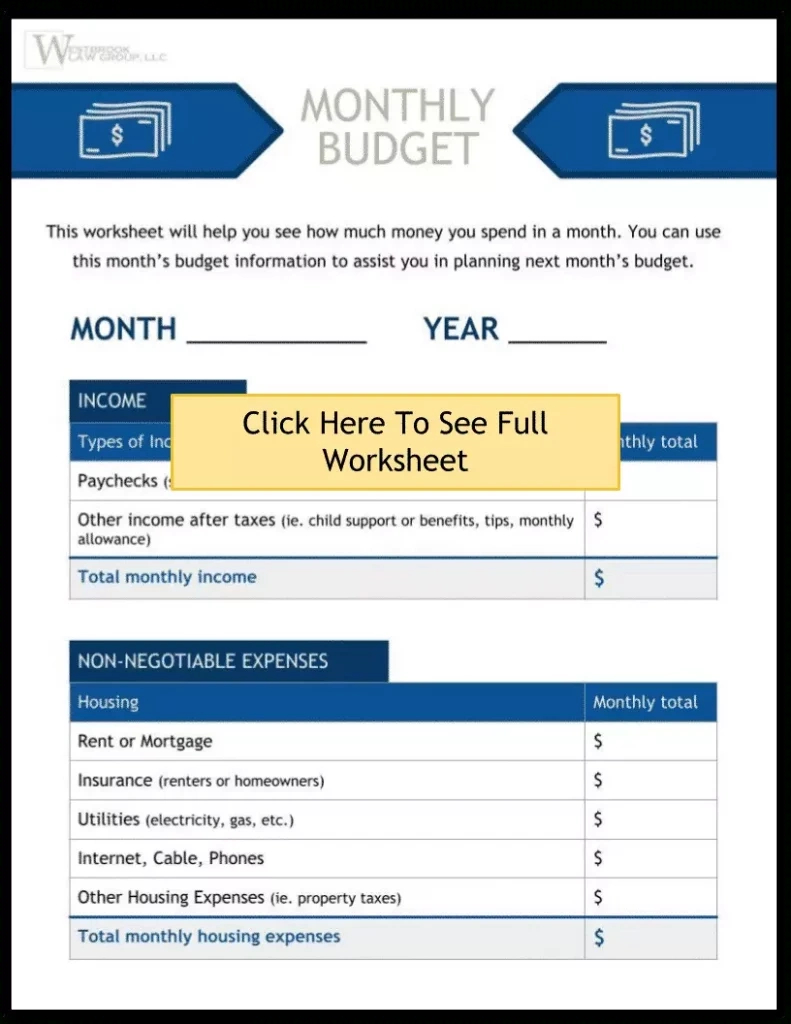
Start with your current monthly income. Not what you made last year. Not your average over the last three years. Your actual income right now, month by month. If your wages have fluctuated, take the higher of your most recent six months or your projected income for the next twelve months. The trustee will look at this closely, so don't guess. Pull your pay stubs. Include overtime if it's consistent. Exclude a spouse's income if you're filing individually and they're not a co-debtor, but include it if you're filing jointly or if their income factors into your means calculation. Next, work through your expenses. This is where people make mistakes. The standard approach is the IRS National and Local Expense Standards. You look up your county, your household size, and your income bracket, then fill in the allowable amounts for categories like food, clothing, housing, transportation, and healthcare. But here's the thing most worksheets don't emphasize enough: the IRS standards are minimums, not maximums. If your actual expenses exceed the standard for a category, you can use your actuals, but you need documented proof. Receipts, statements, anything verifiable. If you claim actual expenses without documentation, the trustee will disallow them during the means test analysis and your disposable income will look artificially low. That's a fast track to a motion to dismiss. There's an important nuance with car payments. If you have a secured car loan, the payment goes in the housing or transportation section depending on how your district structures it. But the value of the vehicle matters. If you owe more than the car is worth, you can sometimes cram down the loan to the collateral value and restructure the remainder as unsecured debt. This is called a "cramdown" and it only applies to vehicles purchased more than 910 days before your filing date. If the loan is newer than that, you're stuck with the full balance. I had a client once who didn't realize this and structured her entire plan around paying the full loan amount. We ended up having to modify it mid-confirmation because the 910-day rule wasn't in play. It added three months of extra paperwork and a hearing.
After income and expenses, the difference is your proposed monthly plan payment. Multiply that by the number of months in your plan — 36 or 60 depending on whether your income is above or below the median for your state — and you get the total commitment. Compare that to your unsecured debts. If the percentage you'd pay is less than what unsecured creditors would receive in a Chapter 7 liquidation, the plan might not be confirmable. The "best interests of creditors" test requires that unsecured creditors get at least as much as they would in Chapter 7. It sounds abstract but it's a hard requirement. Trustees check it. Once the numbers work, you build the plan itself. Priority debts like child support and recent taxes go first. Secured debts follow, with ongoing payments and any arrearages spread across the plan term. Unsecured debts get whatever is left. Medical bills, credit cards, personal loans — they all sit in the same bucket and receive a pro rata share. If your disposable income is low, unsecured creditors might get pennies on the dollar. That's the reality of Chapter 13 for people in deep financial trouble. It's not a total discharge. It's a structured payoff.
Get the Full Details
Where the Worksheet Falls Apart
The biggest limitation is that a worksheet doesn't account for everything the court cares about. It's a financial model, not a legal strategy. It won't tell you whether your local trustee prefers 36-month or 60-month plans, whether your judge has particular expectations about expense documentation, or whether your district allows certain deductions that another district wouldn't. These are the kinds of things that matter during actual confirmation hearings and that you only learn through experience or by talking to someone who practices in your jurisdiction. Another issue is timing. If your financial situation changes after you fill out the worksheet but before you file, the numbers are wrong. An unexpected medical bill, a job loss, a change in childcare costs. The worksheet becomes outdated immediately. People don't always realize this. They treat it like a static document rather than a snapshot. I've seen filings rejected because the debtor's income dropped significantly between the time they completed the worksheet and the actual filing date. The trustee noticed the discrepancy and requested a superseding worksheet. It delayed everything by weeks. If your situation is complex — self-employment income, multiple properties, business debts, or disputes over exempt assets — a simple worksheet won't cut it. You're better off working with a bankruptcy attorney who can handle the calculation and the legal strategy simultaneously. The worksheet is a starting point, not the final product. It gets you in the door. It doesn't guarantee confirmation.
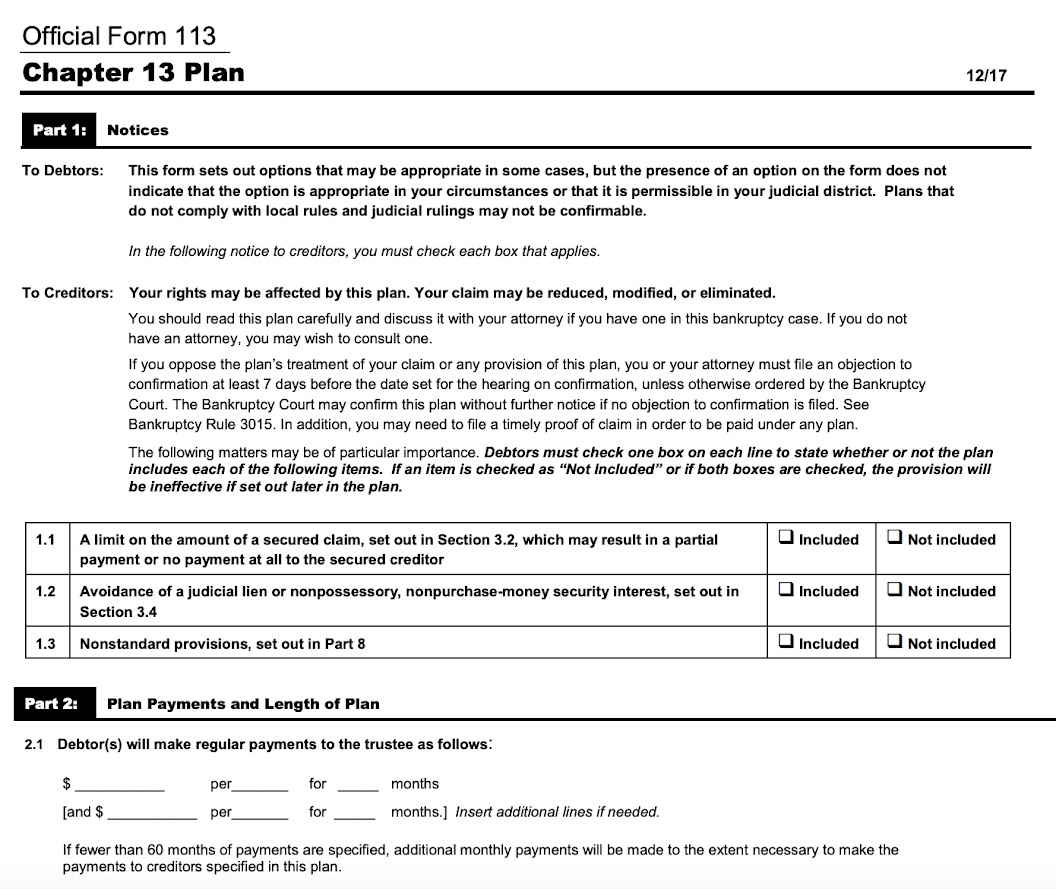
The IRS forms themselves have evolved. Form 122C-1 and Form 122C-2 are the official Chapter 13 means test forms that many worksheets are built around. If you're doing this pro se, you should be using those forms directly rather than relying on a third-party worksheet. Third-party tools often simplify the means test in ways that don't match your district's current interpretation. The official forms get updated periodically as the exemption amounts and expense standards change. Make sure whatever you're using is current. There's also the question of the commitment period. If your income is above the median, you're generally required to propose a 60-month plan. Below the median, you can do 36 months. But there are exceptions. If you're paying 100% of your unsecured claims within 36 months, the shorter plan is allowed even with above-median income. Conversely, if your plan pays less than 100% and you're below the median, the trustee may still require 60 months depending on local practice. The worksheet should reflect this logic, not just the default assumptions. One more thing worth noting: the worksheet doesn't handle post-confirmation modifications well. Life happens during a five-year plan. Divorce, relocation, job changes, additional medical issues. If you need to modify your plan after confirmation, the original worksheet numbers won't help you. You'll need to go back and recalculate based on your current situation and file a motion to modify. Having a clean, accurate initial worksheet makes this process faster, but it doesn't prevent the need for it entirely.
Practical Takeaway
Use the Chapter 13 Bankruptcy Worksheet as a preliminary tool to get your numbers organized and your plan structure clear. Don't treat it as a substitute for professional guidance if your case has any complexity. The differences between districts, the nuances of the means test, and the procedural requirements of confirmation hearings are the kind of things that make or break a filing. A worksheet gets you the math right. Getting the rest right takes more than a spreadsheet.